

Can Life Insurance Be Canceled
As an Insurance Agent and Broker with many years of experience helping Tampa, Saint Petersburg, and Clearwater Area Residents solve their most daunting financial and health care challenges, I’ve heard one question more than almost any other: “Can my life insurance be canceled?”
It is a valid concern. Whether you live in a historic bungalow in Old Northeast St. Pete, a modern condo in Downtown Tampa, or a quiet neighborhood in Clearwater, your life insurance policy is often your family’s primary safety net. The idea that this protection could disappear—either because you no longer want it or because the insurance company made a move—can be unsettling.
Can Life Insurance Be Canceled
In this deep-dive analysis, we will explore the mechanics of policy cancellation from both sides of the coin. We will look at your rights as a consumer in the Tampa-Saint Petersburg-Clearwater Metro Area, the strict regulations that govern insurance companies in Florida, and the pros and cons of comparing different insurance plans to ensure you never find yourself without the coverage you need.
Part 1: When You Want to Cancel Your Policy
Tampa-Saint Petersburg-Clearwater Metro Area residents may have many reasons to consider canceling their life insurance. Perhaps your children have graduated from USF and are now financially independent, or maybe you’ve finally paid off the mortgage on your home in Palm Harbor. Whatever the reason, you have the absolute right to cancel your policy at any time. However, how you do it depends entirely on the type of policy you own.
The “Free-Look” Period: Your First Safety Net
Under Florida law, every life insurance policy comes with a “Free-Look Period.” In the Tampa, Saint Petersburg, and Clearwater Area, this is typically a 14-day window (though some carriers offer up to 30 days) starting from the day you receive the physical policy.
- How it works: If you change your mind within this timeframe, you can cancel the policy for any reason and receive a 100% refund of all premiums paid.
- Pro Tip: As your broker, I always encourage my clients to use this time to do a “deep analysis” of the contract. Does the death benefit match what we discussed in my office? Are the beneficiaries correctly listed in your St. Pete estate plan?
Canceling Term Life Insurance
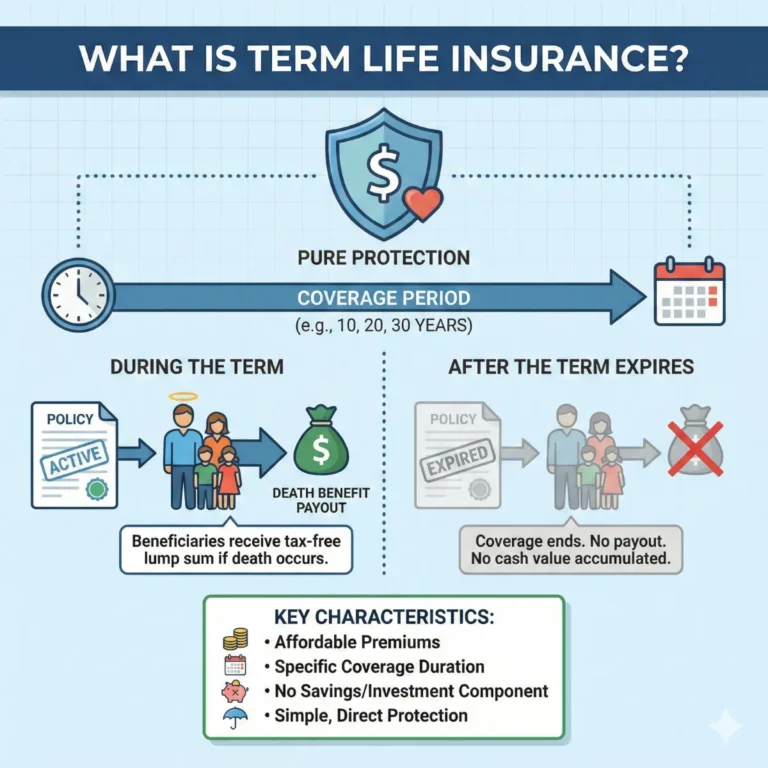
Term life insurance is the most straightforward to cancel. Since it doesn’t build cash value, canceling is usually as simple as stopping your premium payments.
- The Pro: It’s immediate and stops the monthly drain on your bank account.
- The Con: You receive no money back. All the premiums you paid over the years in Tampa were for the “protection” during those years, much like car insurance.
Surrendering Whole Life or Universal Life Insurance
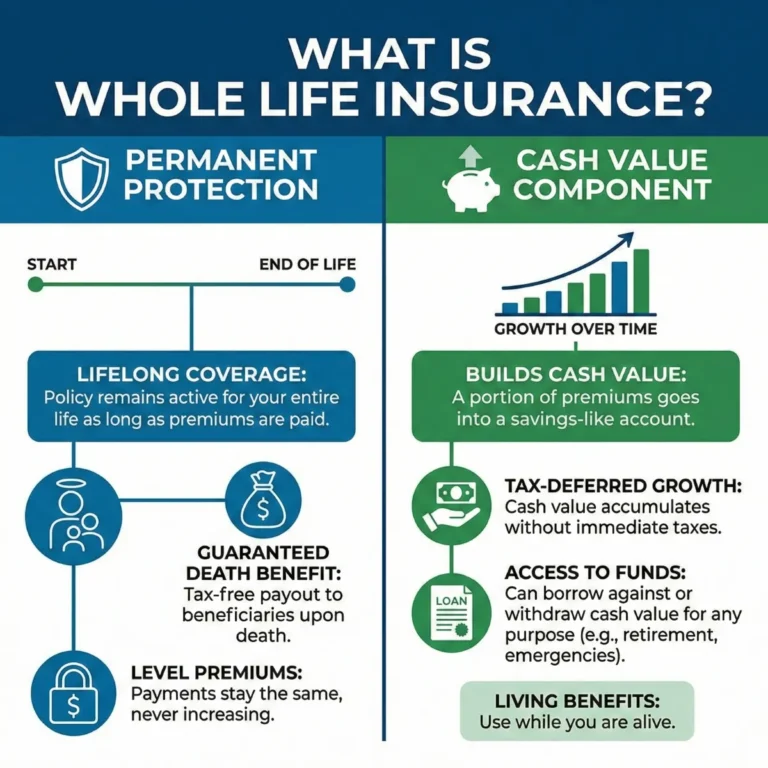
This is where the math gets interesting. Permanent policies build cash value. When you “cancel” (or “surrender”) these policies, you are entitled to the equity you’ve built up.
- Surrender Charges: Many policies in Florida have a “surrender charge” period, often lasting 10 to 15 years. If you cancel too early, the company may take a significant portion of your cash value as a penalty.
- Tax Implications: If the cash you receive exceeds the total premiums you paid while living in Clearwater, the IRS considers that “profit” taxable as ordinary income.
Part 2: When the Insurance Company Can Cancel Your Policy
One of the biggest misconceptions I hear from Tampa-Saint Petersburg-Clearwater Metro Area Residents is that an insurance carrier can cancel your policy just because you got sick. This is 100% false. Once you have a policy in place, the company cannot cancel it due to a change in your health. However, there are three specific scenarios where they can cancel it.
1. Non-Payment of Premiums (The Grace Period)
This is the most common reason for policy cancellation in the Tampa Bay Metro. If you miss a payment, the policy doesn’t vanish instantly. Florida Statute § 627.453 mandates a 30-day grace period.
Expert Note: If you pass away during the grace period, the company must still pay the death benefit to your beneficiaries in Clearwater, though they will deduct the overdue premium from the payout.
2. Material Misrepresentation (The Contestability Period)
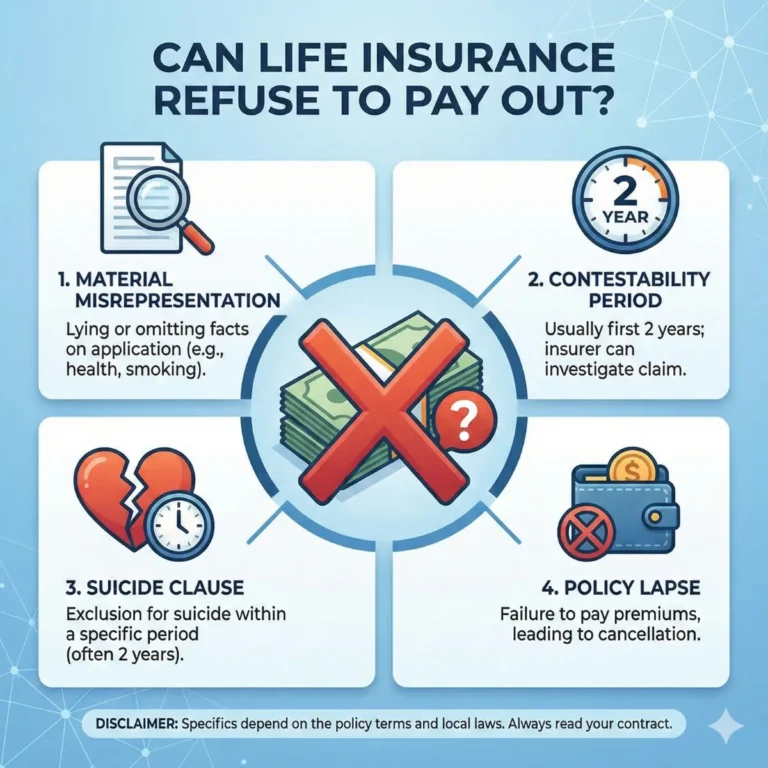
Florida law provides a 2-year Contestability Period. If you pass away within the first 24 months of the policy, the insurance company will double-check your original application against medical records from facilities such as Tampa General or BayCare.
- The Risk: If they find you lied about a major health issue (like a heart condition or tobacco use), they can rescind (cancel) the policy and refuse the claim.
- The Protection: After two years, the policy is generally “incontestable,” meaning they can’t cancel it even if they find an error later.
3. Fraud
While misrepresentation is often an accident or omission, outright fraud (like having someone else take your medical exam in St. Pete) allows the company to cancel the policy at any time, even after the 2-year window.
Part 3: Comparing Insurance Plans in the Tampa Bay Metro
When we look at the best life insurance companies for Metro Area residents, we aren’t just looking at price. We are looking at the “safety features” that prevent accidental cancellation.
Pros and Cons Analysis
| Feature | Term Life Insurance | Whole Life Insurance | Universal Life Insurance |
| Risk of Cancellation | High (if you miss a payment) | Low (Cash value can pay premiums) | Moderate (Requires monitoring) |
| Recovery Options | Reinstatement within limits | Excellent (Automatic Premium Loans) | Flexible |
| Pros for Residents | Lowest cost for Tampa families | Guaranteed for life in St. Pete | Adjustable for Clearwater business owners |
| Cons for Residents | No value if canceled | High initial cost | Complexity of internal costs |
Part 4: SEO Insights and Long-Tail Keywords for Your Search
If you are researching this topic online, you might be using specific “SEO long-tail keywords” to find the most relevant information. As an expert, I know that your search terms often reflect your specific anxiety or stage of life.
- “How to cancel life insurance without penalty Tampa”: This usually applies to people within their free-look period or those surrendering a policy past the surrender-charge window.
- “Life insurance reinstatement rules St. Petersburg, Florida”: If your policy has already lapsed, you typically have 3 to 5 years to “reinstate” it by paying back premiums and interest, often without a new medical exam if you act fast.
- “Florida life insurance grace period explained”: This is for the resident who may have missed a payment due to a temporary job loss or medical emergency.
Deep Analysis: The Mathematics of Cancellation
When deciding whether to cancel, we must look at the Net Cost of Insurance. For a permanent policy, we can use a simple formula to see if the “equity” makes it worth keeping:
$$Surrender Value = Cash Value – Surrender Charges – Outstanding Loans$$
If you are a Clearwater resident and your surrender value is significantly higher than your total premiums paid, you are essentially walking away from a profitable asset. Conversely, if you have a term policy, the math is simpler: if you no longer have a debt to cover, the premium cost is the only variable.
Conclusion: Should You Cancel Your Policy?
Canceling a life insurance policy is a major decision that should never be made in a vacuum. Whether you want to save money in Downtown Tampa, simplify your estate in Saint Petersburg, or pivot your strategy in Clearwater, you need a partner who can deeply analyze your current coverage.
The question isn’t just “can” life insurance be canceled—it’s whether it should be. Sometimes, you can “reduce” or “convert” a policy instead of canceling it, keeping some protection while lowering your costs.
Steve Turner, Insurance Specialist, is an agent and broker here to answer all your questions. With years of experience helping Tampa-Saint Petersburg-Clearwater Metro Area Residents navigate these exact choices, Steve brings expertise and local knowledge you won’t find on a generic website.
The best part? His services are 100% free. Like all independent agents and brokers, he is paid by the insurance company that you choose. This means you get a professional advocate who will double-check your policy, compare all your options, and provide an unbiased recommendation without ever billing you.
Would you like me to review your current policy and see if we can find a more affordable option that better fits your lifestyle in the Tampa Bay area today?
Finding Your Trusted Advisor in the Florida Health Insurance Market
We took a detailed look at the Tampa-Saint Petersburg-Clearwater metro area health insurance market for 2026. We’ve seen how its clever design offers a modern solution for today’s retirees. We’ve also seen that while the plan’s benefits are stable and reliable, its monthly cost can vary significantly from one insurance company to another. Choosing the right company at the right price is the key to maximizing the value of Health Insurance in 2026.
This is where the independent, licensed insurance agent’s guidance becomes invaluable. A Health Insurance specialist acts as your personal shopper and advocate. They can instantly compare these options for the same Health Insurance plan across different carriers in your state. They can also provide insight into a company’s history of rate increases, which is a crucial factor in your long-term satisfaction.
This expert guidance comes at absolutely no extra cost. The insurance industry is regulated, so the plan costs the same whether you buy it through an agent or directly from the company. When you enroll with an agent’s help, the insurance company pays them a commission. This system gives you unbiased, professional advice to help you make the best possible choice.
To ensure you get the best value, it is usually best to use a licensed insurance agent, such as Steve Turner at SteveTurnerInsuranceSpecialist.com. Steve Turner is a licensed Agent/Broker contracted with most Insurance Carriers. An expert like Steve can help you navigate the 2026 Health Insurance market, find the most competitively priced Health Insurance plans for you, and ensure you have a Health Insurance plan that provides both financial security and true peace of mind.
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
Richard Steven Turner’s official Florida state insurance license number (operating as Steve Turner Insurance Specialist) is W333468
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
LIFE INSURANCE POSTS




INSURANCE OFFERINGS
Can You Cancel Life Insurance in Florida?
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please get in touch with Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can use the Medicare Plan Finder at Medicare.gov to research plans available in your Florida county, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.
Steve Turner
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® (REBC®) designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.