
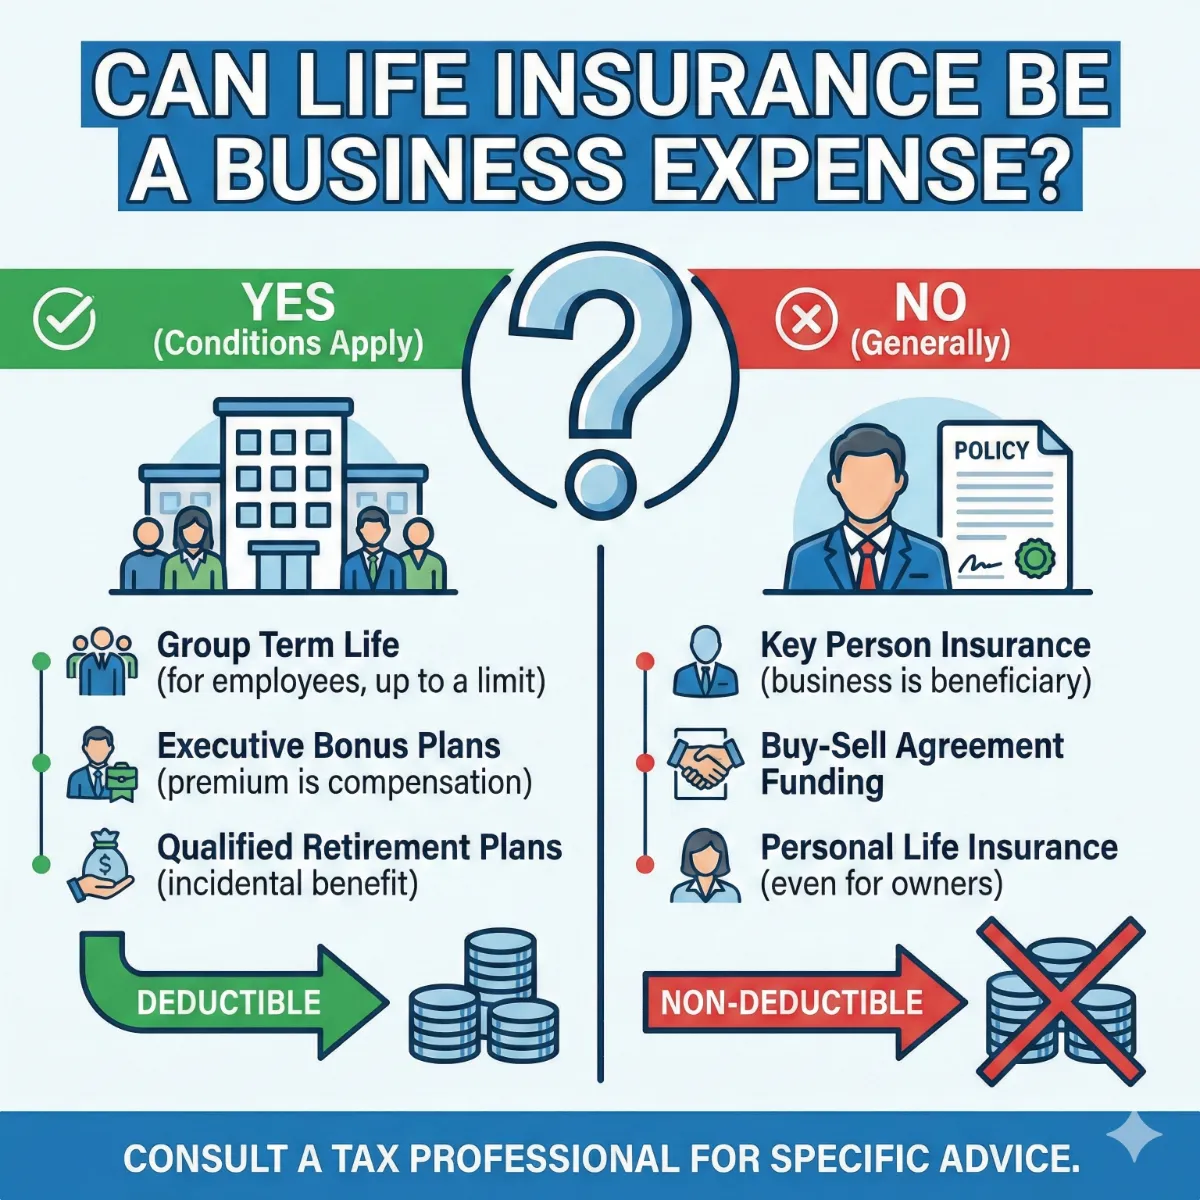
Can Life Insurance Be A Business Expense?
As an Insurance Agent and Broker with years of experience helping Tampa, Saint Petersburg, and Clearwater Area Residents solve complex health care and financial challenges, I have sat across the desk from hundreds of business owners. Whether you run a boutique law firm in Downtown St. Pete, a medical practice in the Westshore District, or a high-tech startup in Clearwater, the goal is the same: maximize protection while minimizing the tax bite.
One of the most frequent questions I receive during our annual reviews is: “Can life insurance be a business expense?” In the 2026 tax landscape, the answer is a nuanced “sometimes.” For most Tampa-Saint Petersburg-Clearwater Metro Area Residents, life insurance is a personal expense paid with after-tax dollars. But when you step into business ownership, the rules change. Under the right circumstances, life insurance isn’t just a safety net; it becomes a powerful, tax-advantaged business tool you can deduct as a legitimate expense.
Can Life Insurance Be A Business Expense?
In this deep-dive analysis, we will explore IRS regulations, the specific plans available to our local business community, and the strategic “pros and cons” of incorporating life insurance into your corporate ledger.
1. The General Rule: Personal vs. Business
For the average resident in Hillsborough or Pinellas County, life insurance premiums are a personal expense. The IRS generally views these as “personal, living, or family expenses” under Internal Revenue Code Section 262. Just as you cannot deduct your personal grocery bill at the local Publix, you cannot deduct the premium on a policy intended to protect your spouse and children.
However, the game changes when the policy is used as a tool for recruitment, retention, or risk mitigation within a business. To be deductible, the policy must qualify as a “necessary and ordinary” business expense, and—most critically—the business must not be a direct or indirect beneficiary of the policy.
2. When It IS a Deductible Business Expense
For businesses in the Tampa, Saint Petersburg, and Clearwater Metro Area, three primary scenarios generally make premiums tax-deductible.
A. Group Term Life Insurance (Section 79)
This is the most common way Tampa Bay Metro Area businesses utilize life insurance as a deduction. Under IRC Section 79, an employer can provide up to $50,000 of group term life insurance to employees, and the business can deduct the premiums.
- The Benefit to the Employee: For the first $50,000 of coverage, the employee pays no income tax on the “value” of the benefit.
- Excess Coverage: If the business provides more than $50,000 in coverage, the business can still deduct the full premium. However, the employee must report the “imputed cost” of the excess coverage as taxable income (using the IRS “Table I” rates).
B. Executive Bonus Plans (Section 162)
Often used by high-end firms in Downtown Tampa to attract top talent, a Section 162 plan lets a business pay premiums on a life insurance policy owned by a key employee.
- The Structure: The business pays the premium directly to the insurance company.
- The Tax Treatment: The business deducts the premium as “compensation.” The employee reports the premium amount as a taxable bonus.
- The Advantage: It is a “selective” benefit. Unlike group plans, you don’t have to offer this to everyone. You can choose to bonus only your top performers in St. Pete or Clearwater.
C. Life Insurance as Alimony (Pre-2019 Agreements)
While not strictly a “business expense” for a corporation, self-employed individuals or sole proprietors in the Tampa-Saint Petersburg-Clearwater Metro Area with divorce agreements finalized before December 31, 2018, may still deduct premiums paid for a policy required by the court as alimony. (Note: This does not apply to agreements finalized after that date due to the Tax Cuts and Jobs Act changes.)
3. When It Is NOT a Deductible Business Expense
As an expert who double-checks every data point, I must warn you: the IRS is very strict on “double-dipping.” If the policy payout is tax-free to the business, the premiums are rarely deductible.
A. Key Person Insurance
If your Clearwater-based business buys a policy on a “Key Person” (like a lead engineer or a founding partner) and the business is the beneficiary, the premiums are not deductible.
- Why? Under IRC Section 264(a)(1), you cannot deduct premiums if the taxpayer is a beneficiary.
- The Silver Lining: When the key person passes away, the death benefit flows into the business income tax-free, providing the liquidity needed to find a replacement or pay off business debts.
B. Buy-Sell Agreement Funding
In a “stock redemption” or “entity purchase” agreement, the business retains ownership of the partners’ policies. When a partner dies, the business uses the insurance money to buy back their shares.
- Tax Status: Non-deductible. The business is the beneficiary.
C. Collateral for a Business Loan
If your bank in Tampa requires life insurance to secure a business loan, many owners assume those premiums are deductible. They are not. Even though the insurance is a requirement for the “business loan,” the IRS still views it as a personal asset used as collateral.
4. Comparing Insurance Plans: A Deep Analysis for Business Owners
When we compare insurance plans available to Tampa, Saint Petersburg, and Clearwater Area Residents, we have to look at the “Net Cost” of each policy. This involves calculating the After-Tax Cost.
If a business in Hillsborough County is in the 21% federal corporate tax bracket, the math for a deductible premium looks like this:
$$Net Cost = Premium \times (1 – Tax Rate)$$
For a $10,000 deductible premium, the business’s actual out-of-pocket cost is $7,900. If the premium is not deductible, the cost remains $10,000. This 21% “discount” is why structuring your plan correctly is vital.
5. Pros and Cons: Using Life Insurance in a Business Context
The Pros:
- Tax Efficiency: Deductible premiums (where allowed) lower the corporate tax bill.
- Retention: “Golden Handcuffs” like Section 162 plans keep your best employees from jumping ship to competitors in Orlando or Miami.
- Liquidity: Provides immediate cash to a St. Petersburg business during a crisis, preventing a “fire sale” of assets.
- Asset Protection: Under Florida law, the cash value in life insurance is generally protected from creditors—a massive “pro” for entrepreneurs.
The Cons:
- Complexity: Requires coordination between your Insurance Broker, CPA, and Attorney.
- Compliance: Failing to follow IRC Section 101(j) (Employer-Owned Life Insurance rules) can make the death benefit taxable—a catastrophic error.
- Cost: Permanent policies (Whole Life/Universal Life) have higher initial costs than term insurance.
6. The 2026 “Connelly” Impact: A Warning for Tampa Bay Business Owners
In 2026, we are still dealing with the fallout of the Supreme Court’s Connelly v. United States decision. This ruling changed how “Entity Purchase” buy-sell agreements are valued for estate taxes.
Expert Analysis: If your business in Tampa owns a life insurance policy to buy back your shares, the Supreme Court ruled that the insurance proceeds increase the value of the company for estate tax purposes. This can lead to a massive, unexpected estate tax bill for your heirs.
As a broker who stays on the cutting edge, I am currently helping my Clearwater and St. Pete clients pivot toward “Cross-Purchase” or “Trust-Owned” arrangements to avoid this “Connelly Trap.”
7. Strategic Advice for Tampa-Saint Petersburg-Clearwater Residents
If you are considering making life insurance a business expense, follow this local “Success Checklist”:
- Define the Goal: Are you trying to save on taxes today (Deductible Group Term) or protect the business for tomorrow (Non-deductible Key Person)?
- Select Local Carriers: While we examine national titans like Mutual of Omaha and MassMutual, we also assess how carriers navigate Florida’s specific regulatory environment.
- Audit Your Current Buy-Sell: If you haven’t updated your buy-sell agreement since 2024, you are likely at risk due to the Connelly decision.
- Use “Notice and Consent”: Under IRC 101(j), you must get an employee’s written consent before you buy a policy on their life. If you miss this step, the IRS will tax the death benefit.
8. Summary Table: Deductibility at a Glance (2026)
| Insurance Type | Is it Deductible? | Who is the Beneficiary? | Best For… |
| Group Term (first $50k) | Yes | Employee’s Family | Employee Benefits |
| Section 162 Bonus | Yes | Employee’s Choice | Executive Retention |
| Key Person | No | The Business | Business Continuity |
| Buy-Sell (Entity) | No | The Business | Ownership Transfer |
| Collateral Assignment | No | The Lender | Securing an SBA Loan |
9. SEO Long Tail Keywords for Local Business Searches
To find the best solutions in our metro area, residents often search for these specific terms:
- “Best group life insurance rates for small businesses in Tampa“
- “Tax-deductible life insurance for Clearwater law firms“
- “Key man insurance quotes Saint Petersburg, Florida.“
- “Executive bonus plan life insurance Hillsborough County“
- “Buy-sell agreement funding strategies for St. Pete entrepreneurs“
10. Frequently Asked Questions (Expert Double-Check)
“Can I deduct my own life insurance as a self-employed person in Tampa?”
Generally, no. The IRS treats your own life insurance as a personal expense, even if you pay for it from your business account. The exception is if you are paying employee premiums.
“Does Florida have a state tax on life insurance premiums?”
Florida does not have a state income tax, so there is no “state-level” deduction to worry about. However, insurance companies pay a 1.75% Premium Tax to the state, which is usually factored into your quoted rate.
“What if I use my life insurance to fund my retirement?”
Many business owners in Clearwater use Cash Value Life Insurance (like IUL or Whole Life) to build a “supplemental retirement fund.” While the premiums are not deductible, the cash grows tax-deferred, and the income you take out in retirement is generally tax-free through policy loans.
Conclusion: Turning a Cost into a Catalyst
So, can life insurance be a business expense? In the Tampa, Saint Petersburg, and Clearwater Metro Area, it absolutely can—provided you have the right architecture in place. It can be the “Golden Handcuffs” that keep your best employees in St. Pete, the shield that protects your practice in Tampa, or the tax-deductible benefit that secures your family in Clearwater.
However, the difference between a “Tax-Deductible Tool” and a “Tax Trap” is found in the details. You need a deep analysis of your corporate structure, your long-term goals, and the latest IRS rulings.
Steve Turner, Insurance Specialist, is here to answer all your questions. As a dedicated agent and broker who has spent many years helping Tampa-Saint Petersburg-Clearwater Metro Area Residents solve their biggest health care and financial challenges, Steve knows that business ownership is hard enough without having to guess at insurance regulations. He double-checks, runs side-by-side comparisons, and works with your CPA to ensure your plan is airtight.
The best part? Steve’s services are 100% free. Like all independent agents and brokers, he is paid by the insurance company that you choose. This means you get expert, unbiased analysis and a localized strategy for your business at no out-of-pocket cost.
Would you like me to run a customized “Tax-Efficiency Audit” of your current business life insurance policies to see if we can unlock any new deductions for your Tampa Bay company today?
Finding Your Trusted Advisor in the Florida Health Insurance Market
We took a detailed look at the Tampa-Saint Petersburg-Clearwater metro area health insurance market for 2026. We’ve seen how its clever design offers a modern solution for today’s retirees. We’ve also seen that while the plan’s benefits are stable and reliable, its monthly cost can vary significantly from one insurance company to another. Choosing the right company at the right price is the key to maximizing the value of Health Insurance in 2026.
This is where an independent, licensed insurance agent’s guidance becomes invaluable. A Health Insurance specialist acts as your personal shopper and advocate. They can instantly compare rates for the same Health Insurance plan options across different carriers in your state. They can also provide insight into a company’s history of rate increases, which is a crucial factor in your long-term satisfaction.
This expert guidance comes at absolutely no extra cost. The insurance industry is regulated, so a plan costs the same whether you buy it through an agent or directly from the company. When you enroll with an agent’s help, the insurance company pays them a commission. This system gives you free, unbiased, professional advice to help you make the best possible choice.
To ensure you get the best value, it is usually best to use a licensed insurance agent, such as Steve Turner at SteveTurnerInsuranceSpecialist.com. Steve Turner is a licensed Agent/Broker contracted with most Insurance Carriers. An expert like Steve can help you navigate the 2026 Health Insurance market, find the most competitively priced Health Insurance plans for you, and ensure you have a Health Insurance plan that provides both financial security and true peace of mind.
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, LICENSED INSURANCE AGENT & BROKER
Questions? Call, text, or book a time below; I answer calls and emails 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
EMAIL STEVE
OFFICE LOCATION
Address: 14502 N Dale Mabry Hwy, Suite 200, Tampa, FL 33618
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
LIFE INSURANCE POSTS
-

Can Medicare Take Life Insurance From a Beneficiary?
By Steve Turner
• 2026-05-04
Can Medicare take life insurance from a beneficiary? Learn when recovery applies, what’s protected, and how to safeguard your loved ones’ benefits. -
Can Life Insurance Be Taxed in Florida?
By Steve Turner
• 2026-03-16
While life insurance payouts are generally tax-free, specific rules apply to cash value and interest. Learn how to protect your legacy. Tap to Learn Now! -
Can Life Insurance Payout Go Into A Trust in Florida?
By Steve Turner
• 2026-03-07
Can a life insurance payout go into a trust? Learn how trusts protect heirs, bypass probate, and offer tax advantages for your family. Tap to Learn Now! -
Can You Cancel Life Insurance in Florida?
By Steve Turner
• 2026-03-04
Can your life insurance be cancelled? Discover the truth about non-payment, fraud, and how to protect your policy today with Steve Turner. Tap to Learn Now! -
Can a Life Insurance Beneficiary Be A Minor in Florida?
By Steve Turner
• 2026-03-02
Naming a minor as a beneficiary? Learn the legal risks, from court delays to custodial accounts, and how to protect your child’s future. Tap to Learn Now! -
Are Life Insurance Premiums Tax Deductible?
By Steve Turner
• 2026-03-01
Are Life Insurance Premiums Tax Deductible? Call Steve Turner, your Licensed Insurance Agent & Broker for FREE HELP! -
Can a Life Insurance Beneficiary Be A Trust in Florida?
By Steve Turner
• 2026-02-27
Naming a trust as your life insurance beneficiary can protect assets and control distributions. Explore the legal benefits today. Tap to Learn Now! -
Can Life Insurance Be Denied? Florida Guide for 2027
By Steve Turner
• 2026-02-25
Life insurance can be denied at application or at claim. A Tampa Bay agent explains Florida’s 2-year contestability rule and how to protect your payout. -
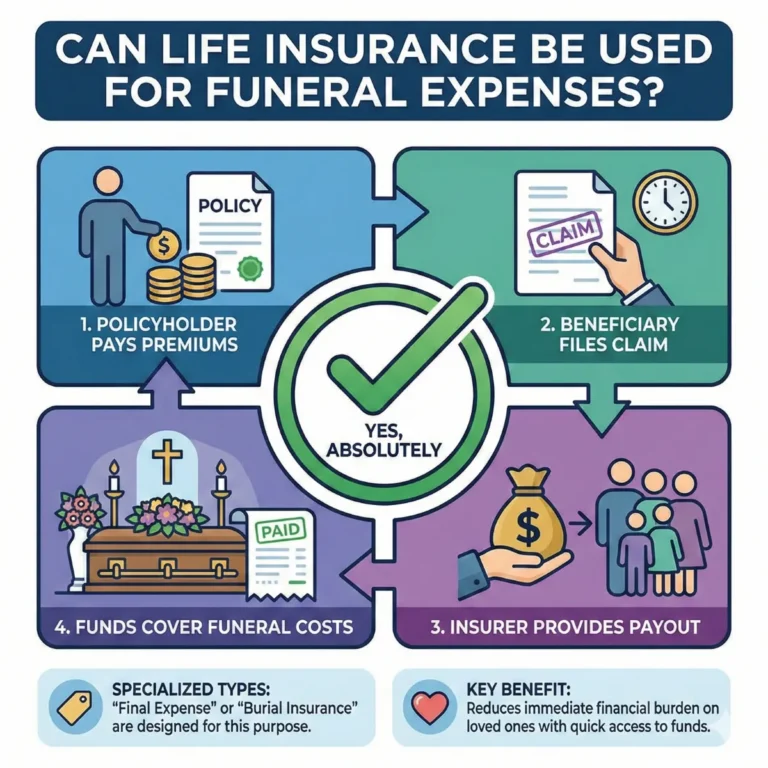
Can Life Insurance Pay for a Funeral? 2027 Tampa Bay Guide
By Steve Turner
• 2026-02-23
Yes, life insurance can pay for a funeral. A Tampa Bay broker compares term, final expense and Florida pre-need plans, 2027 costs, and Medicaid rules. -
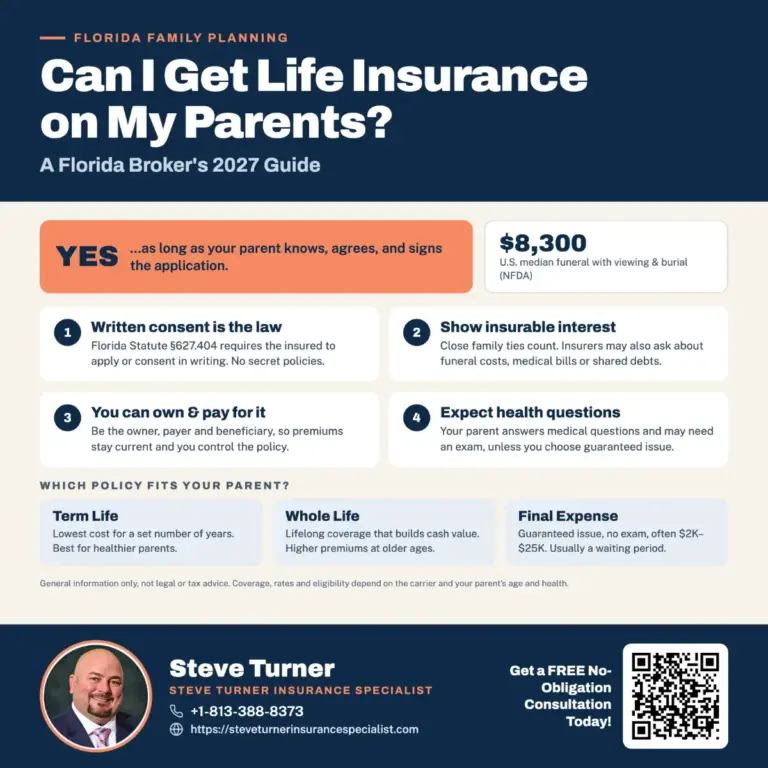
Life Insurance on Your Parents in Florida: 2027 Guide
By Steve Turner
• 2026-02-21
Yes, you can insure a parent in Florida with their consent. A licensed Tampa Bay broker explains 2027 costs, policy types, Medicaid rules and next steps. -
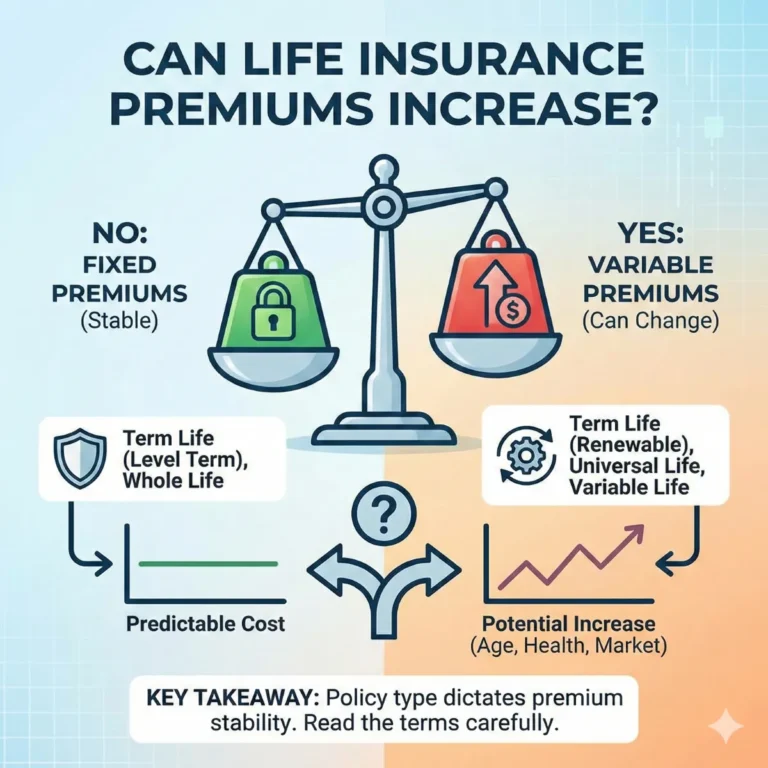
Can Life Insurance Premiums Increase in Florida?
By Steve Turner
• 2026-02-10
Do life insurance premiums increase over time? Learn about fixed vs. variable rates, policy renewals, and age-related costs. Tap to Learn Now! -
Can Life Insurance Policies Be Placed in a Trust in Florida?
By Steve Turner
• 2026-02-10
Learn how placing life insurance in a trust protects assets, avoids probate, and reduces estate taxes. Secure your legacy. Tap to Learn Now! -
Can Life Insurance Refuse To Pay Out in Florida?
By Steve Turner
• 2026-02-10
Can life insurance refuse to pay? Learn about the contestability period, policy lapses, and common exclusions that affect your claim. Tap to Learn Now! -
What Types of Life Insurance Can You Borrow From in Florida?
By Steve Turner
• 2026-02-10
Learn which permanent life insurance policies build cash value for tax-free loans. Compare whole and universal life options. Tap to Learn Now! -
Can Anyone Be a Life Insurance Beneficiary in Florida?
By Steve Turner
• 2026-02-10
Choosing a life insurance beneficiary involves specific rules and tax impacts. Learn who you can name and how to protect your legacy. Tap to Learn Now! -
How Can I Compare Life Insurance Quotes Online Fast in FL?
By Steve Turner
• 2026-02-10
Looking for the best life insurance rates? Easily compare top-rated quotes and find the right coverage for your family’s needs. Tap to Learn Now! -
Whole Life Insurance in Tampa Bay (2027): Costs, Pros, Cons & Top Carriers
By Steve Turner
• 2026-02-10
What is whole life insurance? A Tampa Bay agent explains 2027 costs, cash value, dividends, Florida creditor protection, and when term is the better buy. -
What Are The Best FL Term Policy Life Insurance Companies?
By Steve Turner
• 2026-02-10
Compare top-rated 2026 term life insurance from Pacific Life, Protective, and New York Life. Find affordable, reliable coverage. Tap to Learn Now! -
What Is Term Life Insurance? Low Cost for Floridians!
By Steve Turner
• 2026-02-10
Understand term life insurance basics, affordable rates, and how it protects your family for a set period. Get expert advice. Tap to Learn Now! -

What Type of Insurance Pays Off a Home Loan Upon Death in FL?
By Steve Turner
• 2026-02-10
Protect your home with Mortgage Protection Insurance (MPI) or Term Life. Learn how Steve Turner helps you secure a debt-free future. Tap to Learn Now! -
Family Life Insurance | Floridians Learn Here!
By Steve Turner
• 2025-05-30
Protect your loved ones with affordable family life insurance. Compare custom plans for security and peace of mind with Steve Turner. Tap to Learn Now! -
10 Cheap Life Insurance for Couples
By Steve Turner
• 2025-05-28
Looking for affordable life insurance for couples? Compare the best joint and individual rates to secure your family’s future today. Tap to Learn Now! -

Save 6 Ways: Cheap Senior Life Insurance in Florida
By Steve Turner
• 2025-05-26
Discover 6 ways to secure affordable senior life insurance. Save on premiums, compare top 2026 rates, and protect your family today. Tap to Learn Now! -

Affordable Life Insurance | What Floridians Must Know!
By Steve Turner
• 2023-03-07
Finding affordable life insurance is easy with Steve Turner. Compare top-rated plans for families and businesses to save money. Tap to Learn Now! -

Whole Life Vs Term Life Insurance in Florida
By Steve Turner
• 2023-03-03
Compare Whole Life vs Term Life insurance to find the best coverage for your family’s future. See costs, benefits, and cash value. Tap to Learn Now!
INSURANCE OFFERINGS
Can Life Insurance Be A Business Expense in Florida?
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS COVERAGE UNDER 65
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
Medicare plan availability differs by state and county. Steve Turner is licensed in AL, CO, FL, GA, NC, SC, TN, and TX.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
MEDICARE DISCLAIMER
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
Steve Turner
Steve Turner, CLU®, REBC® is licensed in AL, CO, FL, GA, NC, SC, TN, and TX · NPN 18030539 · Florida License W333468
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals NABIP®. Steve holds the Registered Employee Benefits Consultant® (REBC®) designation. Steve also holds the “Chartered Life Underwriter” designation (CLU®), a professional credential for individuals specializing in life insurance and estate planning, conferred by the American College of Financial Services. Since 2016 (over 10 years), Steve has helped individuals, families, Medicare beneficiaries, and small businesses find the right coverage to meet their needs. Steve has earned 180+ Google reviews from happy clients.
Steve Turner is a licensed agent appointed by Florida Blue in Florida.