
Tap the button below to get your FREE Medicare Advantage & Medicare Supplement Quote from Steve Turner.
Medicare Supplement Insurance
Steve Turner Insurance Specialist offers you, your family, and your business the complete array of Insurance Services you need to protect and provide for your Medicare Supplement Insurance needs.
My goals are to (1) listen to you tell me about your insurance needs, budget, and the outcome you require, (2) educate you on your various options, and (3) set up the insurance plans you have selected and get your insurance coverage established.
Not sure what type of insurance is best for your Personal, Family, or Business? No worries! Most of my clients aren’t sure when they first reach out. I’ll discuss all your insurance options with you, including the pros and cons, so YOU can make the choices that fit your budget.
Tap the “+1.813.388.8373” button to call me now, or the “Book-A-Call” button to pick a time on my calendar for a chat. I look forward to answering your questions and helping you find the right insurance to fit your needs.
OUR RESULTS
LISTENING SKILLS
SCORE = 100
PLAN CHOICES
SCORE = 100
BUDGET FIT
SCORE = 100
Medicare Supplement Insurance
As a Florida-based independent insurance agent with extensive experience, we help you navigate the world of Medicare Supplement (or “Medigap”) Plans. Medicaid doesn’t offer these plans; they’re private insurance policies designed to work with Original Medicare. We offer a comprehensive portfolio of plans from top-rated carriers in Florida, including popular options like Plan G, Plan N, and High-Deductible Plan G. Our service begins with a no-cost, educational consultation to help you understand how these plans provide predictable costs and unparalleled freedom of choice in your Healthcare. We then conduct a detailed market and rate-stability analysis to find you the most cost-effective plan from a reputable carrier.
When choosing an agent for a Medigap plan, the most critical question you can ask is: “Since Medigap plans are standardized, how do you help me choose the best company for my needs?” An expert agent will explain that because a Plan G from one company is medically identical to a Plan G from another, you should choose based on three factors: the company’s current price, its historical rate-increase stability, and its financial strength rating. You should also ask whether they are an independent agent who can provide quotes from a wide variety of carriers, not just one or two.
Medicare Supplement Insurance Plans We Offer: A Florida Expert’s Guide to Freedom of Choice and Predictable Healthcare Costs
When you retire, the last thing you want is to worry about unexpected medical bills or to discover that your trusted doctor is suddenly “out-of-network.” For many Florida residents, the key to true peace of mind and control over their Healthcare is a Medicare Supplement Insurance Plan, also known by the popular nickname, Medigap.
As an independent insurance agent who has spent many years specializing in these plans for Florida residents, I’ve seen the confidence and security they provide. A Medigap plan is for the individual who values predictability and freedom above all else. It answers the uncertainty of Original Medicare’s out-of-pocket costs and the network restrictions of managed care.
However, Medigap has its own complexities. With dozens of insurance companies offering seemingly identical plans at different prices, how do you choose? This guide is your comprehensive blueprint. It’s designed to demystify Medigap, explain the specific plan options we offer, and arm you with the critical questions you must ask to choose not just the right plan. It’s also about finding the right long-term insurance carrier and the right expert agent to guide you.
Part 1: What is a Medicare Supplement (Medigap) Plan? – The Foundation of Predictable Coverage
Before we explore the specific plans, it’s crucial to understand what a Medigap plan is and how it works. A Medigap plan is a private insurance policy that you purchase to work alongside your Original Medicare (Part A and Part B). Its sole purpose is to pay for the “gaps” in coverage that Original Medicare leaves behind.
How It Works: The “Pays Second” Model
The process is seamless. You will have your red, white, and blue Medicare card and a separate ID card from your Medigap insurance company. When you visit any doctor or hospital in the U.S. that accepts MediU.S.:
- You show both cards.
- The provider bills Medicare first.
- Medicare pays its share (typically 80% of the medical bill).
- Medicare then automatically forwards the remaining bill to your Medigap plan.
- Your Medigap plan pays its share (often the remaining 20%).
The “Gaps” a Medigap Plan Fills:
Original Medicare has high out-of-pocket costs with no annual limit. Medigap plans are designed to cover these specific costs, including:
- The large Part A hospital deductible (approximately $1,680 in 2025).
- Daily hospital coinsurance for extended stays.
- The 20% coinsurance for virtually all Part B doctor’s services and outpatient care.
- Skilled Nursing Facility coinsurance.
- Foreign travel emergency care.
The Power of Standardization: A Plan G is a Plan G
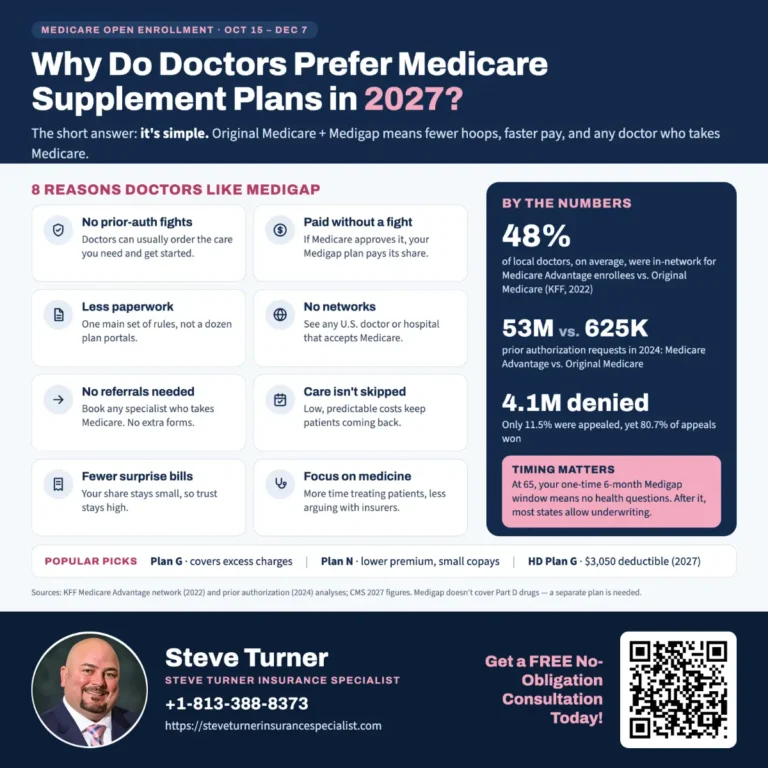
This is the most important concept to understand about Medigap. The federal government standardizes the plans and identifies them by letters (A, B, C, D, F, G, N). This means that a Plan G from one insurance company has the same medical benefits as a Plan G from any other company. This makes it easy to compare plans, because if you’ve decided on a Plan G, your decision comes down to choosing the best company.
Part 2: A Deeper Dive into the Medigap Plans We Offer in Florida
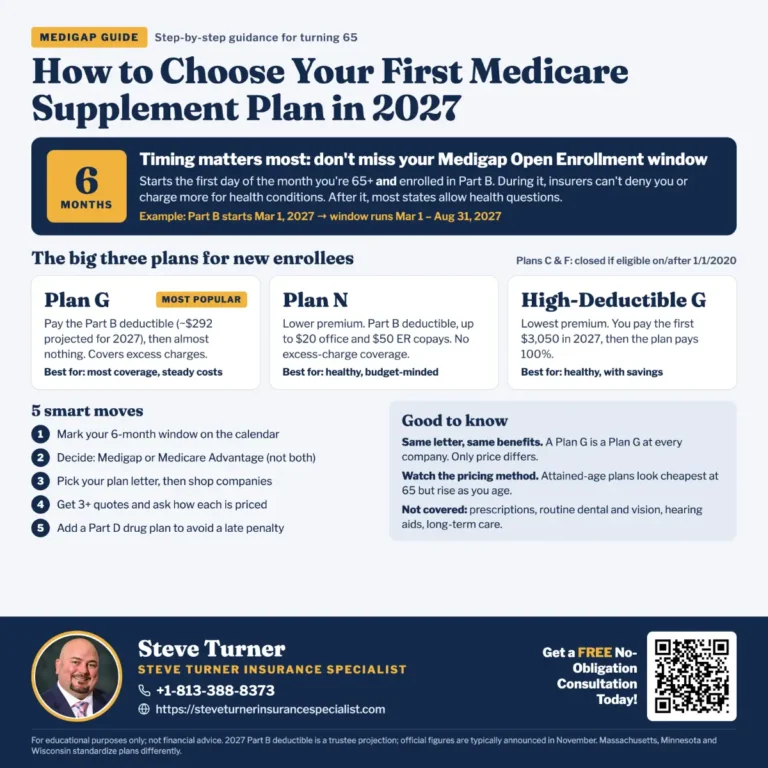
As an independent agency, we are appointed with dozens of top-rated Medigap carriers in Florida. This allows us to find the best value for you. While there are several plan letters, for new Medicare beneficiaries in 2025, the conversation almost always centers on three excellent options.
A. Plan G: The Gold Standard
Plan G has become the most popular and comprehensive plan for new Medicare beneficiaries.
- What It Covers: Plan G covers every gap in Original Medicare, except the small annual Part B deductible (approximately $250 in 2025). Once you pay that deductible once per year out of pocket, Plan G covers 100% of your Medicare-approved expenses for the rest of the year. This includes the Part A deductible and all of the 20% coinsurance for your doctor bills.
- Best For: Individuals who want the highest level of coverage, the most predictable costs, and virtual elimination of medical bills. You pay a higher monthly premium in exchange for this comprehensive peace of mind.
B. Plan N: The Smart Cost-Sharing Option
Plan N is a fantastic option for those who want excellent coverage but are willing to share a small, predictable portion of their costs in exchange for a lower monthly premium.
- What It Covers: Plan N provides the same coverage as Plan G for major hospital costs. For outpatient services, it still covers the 20% coinsurance. Still, you agree to pay a small copayment for doctor and emergency room visits (up to $20 for an office visit and up to $50 for an ER visit that doesn’t result in an inpatient admission). It also does not cover Part B excess charges (which are rare in Florida).
- Best For: Relatively healthy individuals who want to save on monthly premiums and are comfortable with small, predictable copayments for routine medical care.
C. High-Deductible Plan G: The Catastrophic Coverage Option
This plan offers the same comprehensive benefits as a standard Plan G, but with a key difference.
- How It Works: You must first pay a higher annual deductible out of pocket (approximately $2,800 in 2025). This deductible includes all of your Medicare Part A and B deductibles and coinsurance. After you meet that deductible, the plan pays 100% of all your Medicare-approved costs for the rest of the year.
- Best For: Healthy, savvy consumers who can comfortably afford the deductible and want a much lower monthly premium while still having a rock-solid safety net against a catastrophic health event.
What About Plan F?
You may have heard about Plan F, which was formerly the most popular plan. Due to a federal law change (MACRA), Plan F is only available to individuals who were eligible for Medicare before January 1, 2020. If you are turning 65 in 2025, you are not eligible to purchase Plan F.
Part 3: Our Service Process – A Data-Driven Approach to Choosing Your Carrier
Since Medigap plans are standardized, choosing the right company is a critical financial decision. Our experts help you make the best long-term choice.
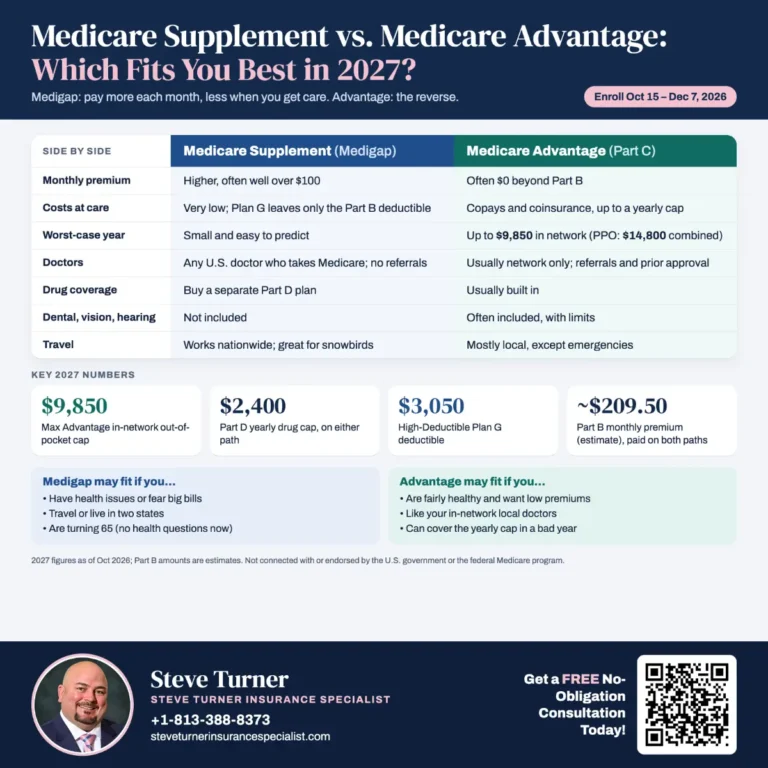
- The Educational Consultation: We start with a no-cost, no-obligation meeting to explain your options, focusing on a clear comparison between the Medigap and Medicare Advantage paths.
- The Comprehensive Needs Analysis: We take the time to listen to your health needs, your budget, and your risk tolerance to help you decide which plan letter (G, N, etc.) is the best fit for you.
- The Unbiased Market & Rate Analysis: This is our core service. We use our specialized software to instantly compare the current monthly premiums for your chosen plan from dozens of top-rated insurance carriers in your specific Florida ZIP code.
- The Rate Stability Consultation: We don’t just show you the lowest price today. A low introductory rate is meaningless if large year-over-year increases follow it. We provide historical rate-increase data for the top carriers, helping you choose a company known for stable, predictable pricing. We also review each company’s financial strength ratings (from A.M. Best).
- Seamless Enrollment Assistance: Once you’ve made a choice, we handle the entire enrollment process, ensuring all paperwork is submitted correctly and on time.
- Lifelong Support: Our relationship doesn’t end there. We are your advocate. If rates increase significantly in the future, we can help you shop the market again to find a better value.
Part 4: The Ultimate Vetting Checklist – 10 Questions to Ask Any Medicare Agent
Choosing the right agent is crucial. Here are 10 essential questions to ask.
1. “Since Medigap plans are standardized, what is your specific process for helping me choose the best company for my Plan G?”
- Why it matters: This is the #1 expert question for Medigap. A great agent will immediately start comparing carriers based on price, rate-increase history, and financial ratings. A less experienced agent will not have a good answer.
2. “Are you an independent agent, and how many different Medigap carriers are you appointed with in Florida?”
- Why it matters: An independent agent can provide you with quotes from across the entire market to find the best price. A captive agent can only offer you their company’s product, which may not be the most competitive.
3. “Can you provide me with the historical rate increase data for the top 2-3 carriers you are recommending?”
- Why it matters: This tests their commitment to your long-term financial health. An agent who is truly looking out for you will want you to choose a company with a history of stable rates.
4. “What is the ‘guaranteed issue’ right, and how does it apply to me during my Medigap Open Enrollment Period when I first turn 65?”
- Why it matters: This tests their knowledge of the most important Medigap enrollment rule. They should clearly explain that during this one-time, six-month window, you can buy any Medigap plan from any company, regardless of your health history.
5. “Is there any cost for your services, either now or in the future?”
- Why it matters: The answer must be “no.” Agents are compensated directly by the insurance companies. You should never be charged a fee for an agent’s help.
6. “How do you help me choose a separate Part D prescription drug plan to go with my Medigap policy?”
- Why it matters: A Medigap plan does not include drug coverage. A great agent will have a meticulous, data-driven process for finding the most cost-effective standalone Part D plan based on your specific medication list.
7. “What is your experience with the different household discounts that various carriers may offer?”
- Why it matters: This is a nuanced, expert question. Many companies offer a discount (typically 5-12%) if you and your spouse both enroll. A knowledgeable agent will factor this into their cost analysis.
8. “What ongoing support do you provide after I’m enrolled, especially if my plan’s rates increase significantly in a few years?”
- Why it matters: This tests their commitment to a long-term relationship. A great agent will proactively help you shop the rate again in the future to ensure you always have the best value.
9. “Can you explain the difference between ‘attained-age,’ ‘issue-age,’ and ‘community-rated’ policies and which are most common in Florida?”
- Why it matters: This advanced question tests deep product knowledge. They should be able to explain how the different rating methods affect your future premiums.
10. “Why should I work with you instead of just calling a big insurance carrier directly?”
- Why it matters: This asks them to state their value proposition directly. A great agent will explain that a carrier can only sell you their own product, while they can act as your unbiased advocate and comparison shopper across the entire market.
Part 5: Red Flags vs. Green Lights – Making Your Final Choice of Agent
🚩 Major Red Flags to Run From 🚩
- Pushes One Specific Company: They are likely a captive agent or are pushing the product with the highest commission.
- Doesn’t Mention Rate Increase History: They focus on making the easiest sale today, not your long-term costs.
- Can’t clearly explain why a Plan G is a Plan G, regardless of the company.
- Doesn’t have a Clear Process for helping you with your separate Part D drug plan.
✅ Bright Green Lights to Look For ✅
- Takes an Educational Approach, focusing on teaching you your options.
- Their analysis is focused on rate stability and company ratings, not just the initial price.
- Represents a Wide Range of Top-Rated Carriers and provides you with a full market comparison.
- Acts as a true long-term advisor, committed to helping you manage your coverage for years to come.
Your Final Decision
A Medicare Supplement plan offers the ultimate in predictability, financial security, and freedom of choice for your Healthcare and Retirement. It lets you budget for your healthcare needs, have confidence, and see any doctor you choose, anywhere in the country.
While plan benefits are standardized, the quality and long-term cost of the insurance companies that offer them are not. By partnering with a knowledgeable, independent agent who is dedicated to your best interests, you gain a powerful advocate. You get an expert who can not only help you find the best value today but also help you manage your coverage to ensure it remains the best value for years to come. Your retirement should be worry-free; we’re here to help make sure your Healthcare is also.
Medicare SUPPLEMENT INSURANCE AGENT AND BROKER NEAR ME
Medicare Supplement Insurance
As your Medicare Supplement Insurance Agent and Broker serving you, my goal is to “help you” and ensure, without a shadow of a doubt, that you and your family are secure and protected from risk. As a licensed Medicare Supplement Agent, I take the burden off your shoulders by doing a thorough needs analysis and researching the benefits best suited to you.
I can help you find a Medicare Supplement plan that gives you peace of mind with predictable out-of-pocket expenses and lets you choose any doctor or specialist that accepts Medicare Nationwide.
Medicare is constantly changing, and I work tirelessly to stay informed about the latest market developments. Every year brings new government regulations, new or modified coverages, and new techniques for controlling benefit costs. To best serve their clients, professionals must understand each benefit or program’s provisions, advantages, and limitations to support economic security.
I am a long-standing National Association of Benefits and Insurance Professionals® (NABIP.ORG) member and hold the prestigious Registered Employee Benefits Consultant® designation (https://nabip.org/professional-development/rebc-designation). I can provide information on your market’s availability and any expected changes.
After you choose your Medicare Supplement Insurance plan, I provide ongoing support year-round; you won’t have to call an (800) number anymore.
If you have any questions, issues, or concerns about your plan’s benefits, you can contact me via phone, text, or my simple-to-use email contact form using the buttons below.
Steve Turner, your Helpful Licensed Agent and Broker
Medicare Supplement Insurance FAQ
OUR CLIENT REVIEWS


CONTACT STEVE TURNER INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
Richard Steven Turner’s official Florida state insurance license number (operating as Steve Turner Insurance Specialist) is W333468
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. – 8:00 p.m.
Tuesday: 7:00 a.m. – 8:00 p.m.
Wednesday: 7:00 a.m. – 8:00 p.m.
Thursday: 7:00 a.m. – 8:00 p.m.
Friday: 7:00 a.m. – 8:00 p.m.
Saturday: 7:00 a.m. – 8:00 p.m.
Sunday: 7:00 a.m. – 8:00 p.m.
SERVICE AREA FACTS UNITED STATES
The United States: Facts and Top Visitor Sites
The United States of America is a vast, diverse country with a wide array of cultures, landscapes, and iconic landmarks. Here are some key facts and top attractions:
Facts about the USA
The United States is a vast, diverse country with a rich tapestry of culture, history, and natural beauty. Here is a comprehensive overview of key statistics and top visitor attractions across the nation.
Key U.S. Statistics and Economic Overview
The United States is a global leader in population, economy, and innovation, attracting people from all over the world.
- Population and Demographics: As of 2025, the U.S. population is projected to exceed 343 million, making it the world’s third-most populous country. The population is diverse, with a significant Hispanic and Latino population that accounts for much of the recent growth. The median age is around 39 years, and a growing segment of the population is over 65, reflecting an aging nation.
- Geography: Third largest country by land area, behind Russia and Canada. It spans 3.8 million square miles and has 4 million miles of roads.
- National Parks: 63 national parks nationwide.
- Government-owned Land: The government owns 37% of the land (federal, state, and local).
- Diversity: The U.S. is a diverse country, with a growing non-white population. Non-Hispanic white people currently make up the largest ethnic group, but their share of the population has decreased over time. The Hispanic population has grown the most, increasing by 23% between 2010 and 2020.
- Languages: While English is the primary language, Spanish is the most common non-English language spoken at home, followed by Chinese and Tagalog.
- Aging Population: Americans are living longer, and the 65-and-older population is increasing significantly.
- Economy & Key Industries: The U.S. economy is the largest in the world by nominal GDP. Its economic strength is built on several key industries:
- Financial Services: This sector is a global powerhouse, centered in cities like New York, with major hubs for banking, insurance, and investment.
- Technology and Information Technology (IT): The U.S. leads the world in technology, with major tech hubs in Silicon Valley, Austin, and Seattle driving innovation in software, hardware, and digital services.
- Healthcare and Social Assistance: As the country’s largest private employment sector, healthcare is a massive industry with high demand for skilled workers and ongoing innovation.
- Manufacturing: The U.S. manufacturing sector is a backbone of the economy, producing everything from automobiles and aerospace components to medical equipment and consumer goods.
- Work-from-Home Trends: More Americans work remotely than before the pandemic. In 2022, 15% of Americans worked from home, up from 6% in 2019.
Top Places for Visitors to Explore in the USA
The United States offers an incredible variety of destinations, from iconic cities to breathtaking national parks.
- New York City, New York: A global icon, New York City is famous for its vibrant culture, world-class museums, and iconic landmarks. Visitors can explore Times Square, see a Broadway show, visit the Statue of Liberty, and walk through Central Park. The city offers an endless array of dining and shopping experiences.
- The Grand Canyon, Arizona: A breathtaking natural wonder carved by the Colorado River, the Grand Canyon National Park is a must-see. Visitors can take in panoramic views from the South Rim, hike into the canyon, or take a helicopter tour for a unique perspective.
- Las Vegas, Nevada: Known as “The Entertainment Capital of the World,” Las Vegas is famous for its casinos, luxury hotels, and spectacular live shows. The Las Vegas Strip is a bustling boulevard with unique attractions and a vibrant nightlife.
- Orlando, Florida: The “Theme Park Capital of the World,” Orlando is home to some of the world’s most famous attractions, including Walt Disney World Resort and Universal Orlando Resort. It is a top destination for families and anyone seeking a thrilling, magical vacation.
- Washington, D.C.: The nation’s capital is a city of history and monuments. Visitors can explore the National Mall, which connects the Lincoln Memorial, Washington Monument, and the U.S. Capitol. It’s also home to the Smithsonian Institution’s world-class museums.
- Yellowstone National Park, Wyoming: As the first national park in the U.S., Yellowstone National Park is a marvel of geothermal activity and wildlife. It is home to the famous Old Faithful geyser, the Grand Prismatic Spring, and a wide variety of animals, including bison, bears, and wolves.
- San Francisco, California: This iconic West Coast city is famous for the Golden Gate Bridge, its historic cable cars, and diverse neighborhoods. Visitors can explore Fisherman’s Wharf, Alcatraz Island, and the beautiful Golden Gate Park.
- Hawaii: An archipelago in the Pacific Ocean known for its stunning natural beauty, volcanic landscapes, and rich Polynesian culture. Visitors can relax on beautiful beaches, hike through lush rainforests, and explore the Hawaii Volcanoes National Park on the Big Island.
- Great Smoky Mountains National Park, North Carolina/Tennessee: The Great Smoky Mountains National Park is the most visited national park in the U.S. and is known for its beautiful mountains, diverse plant and animal life, and rich Appalachian culture.
- New Orleans, Louisiana: This historic city on the Mississippi River is famous for its unique blend of cultures, live music, and vibrant festivals. The French Quarter is a lively neighborhood with historic architecture, delicious Creole cuisine, and jazz clubs.
MEDICare SUPPLEMENT INSURANCE POSTS
SERVICE AREA
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please contact Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can research the plans available in your Florida county using the Medicare Plan Finder at Medicare.gov, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.