
Medicare Supplement vs. Medicare Advantage: Which Fits You Best in 2027?

Medicare Supplement vs. Medicare Advantage: Comparing Two Main Medicare Coverage Options
If you’re choosing between a Medicare Supplement and a Medicare Advantage plan for 2027, I want to help you decide with less stress. This is one of the biggest health care decisions you will make after you turn 65. The right pick can save you thousands of dollars. The wrong one can leave you with bills you did not plan for, or doctors you can’t see.
When I first started learning about Medicare, I felt lost. Letters, numbers, and terms were everywhere. Part A. Part B. Plan G. HMO. PPO. It felt like alphabet soup. So in this article, I will keep things simple. I will use plain words, short lists, and real examples.
Here is what I will cover:
- What Medicare Supplement and Medicare Advantage plans are
- The key 2027 costs and changes you should know
- A side-by-side look at how the two compare
- The pros and cons of each choice
- Who each option fits best
- Answers to the questions people ask me most
- A simple checklist to help you decide
By the end, I hope you will feel sure about which path fits your life, your health, and your budget in 2027.
Medicare Basics: The Two Main Paths
Before I compare the two plans, I need to explain where each one fits. Think of Medicare like a road that splits into two paths. You pick one path to get your health care.
Path 1: Original Medicare (plus a Supplement)
The federal government runs Original Medicare. It has two parts:
- Part A helps pay for hospital stays, skilled nursing care, and hospice.
- Part B helps pay for doctor visits, lab tests, outpatient care, and medical equipment.
Original Medicare is good coverage, but it has gaps. After you pay the Part B deductible, you usually pay 20% of the bill for most doctor and outpatient care. And here is the scary part: there is no yearly cap on that 20%. If you get very sick, your share could keep growing.
That is where a Medicare Supplement comes in. People also call it Medigap. A private insurance company sells it. It “fills the gaps” in Original Medicare, like the 20% coinsurance and the hospital deductible.
Medigap plans are named with letters, like Plan G or Plan N. Each letter covers the same things no matter which company sells it. So a Plan G from one company has the same benefits as a Plan G from another. Only the price and service are different.
Most people on this path also buy a separate Part D plan for prescription drugs. Medigap does not cover drugs.
Path 2: Medicare Advantage (Part C)
Medicare Advantage is another way to get Medicare. Instead of the government paying your bills, a private insurance company does. You still have Medicare, but the plan sets its own rules.
Most Medicare Advantage plans bundle everything into one card:
- Hospital coverage (Part A)
- Medical coverage (Part B)
- Drug coverage (Part D), in most plans
- Extras like dental, vision, and hearing in many plans
The most common types are HMOs and PPOs. An HMO usually makes you use doctors in its network. A PPO lets you go out of network, but you pay more when you do.
The Big Rule to Remember
You can’t have both. If you join a Medicare Advantage plan, you can’t use a Medigap plan. It is one path or the other.
Key Medicare Numbers and Changes for 2027
Costs change every year, so I always check the new numbers before I compare plans. Some 2027 numbers are final. Others are still estimates, because the government usually announces the Part B premium in November. Here is what I know as of mid-October 2026:
| What it is | 2026 | 2027 | Final or estimate? |
|---|---|---|---|
| Part B monthly premium | $202.90 | About $209.50 | Estimate (Medicare Trustees, via MedicareFAQ) |
| Part B yearly deductible | $283 | About $292 | Estimate (AARP) |
| Medicare Advantage in-network out-of-pocket cap | $9,250 | $9,850 | Final (BenefitsUSA) |
| Medicare Advantage PPO combined cap (in and out of network) | $13,900 | $14,800 | Final (BenefitsUSA) |
| Part D drug deductible (most you can be charged) | $615 | $700 | Final (Kiplinger) |
| Part D yearly out-of-pocket drug cap | $2,100 | $2,400 | Final (BenefitsUSA) |
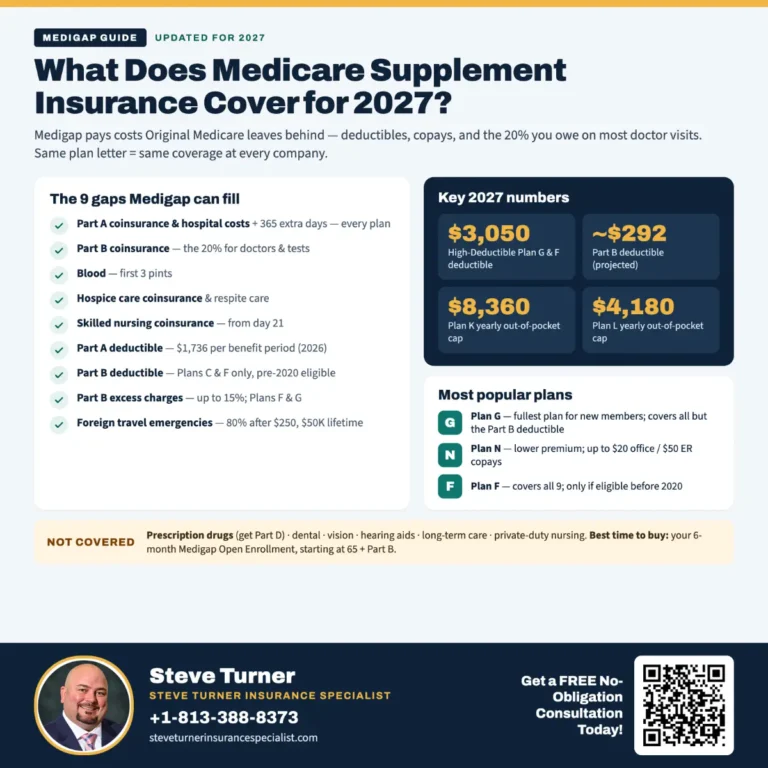
| High-Deductible Plan G deductible | $2,950 | $3,050 | Final (CMS) |
What These Numbers Mean for You
Here are the 2027 changes I think matter most:
- Everyone pays more for Part B. You pay the Part B premium on both paths. That includes people in Medicare Advantage. So this cost doesn’t help you choose one over the other. It is just part of your budget.
- The Medicare Advantage worst case went up. The highest cap a plan may set rose $600, to $9,850. Many plans set a lower cap. But a BenefitsUSA review of 2027 plan files found the typical plan with drug coverage raised its in-network cap from $5,900 to $6,500.
- Drug costs still have a ceiling. The Part D cap rises to $2,400. This cap protects you on either path, as long as you have Part D coverage.
- High-Deductible Plan G costs a bit more to reach. Its deductible is now $3,050. After you pay that, the plan covers the rest of your approved costs for the year.
My tip: once the official Part B numbers come out, look at your plan letters again. Your “Annual Notice of Change” letter also shows what’s changing in your current plan for 2027.
Medicare Supplement vs. Medicare Advantage: Side by Side
The simplest way I can explain the difference is this: Medigap means you pay more each month, but less when you get care. Medicare Advantage means you pay less each month, but more when you get care.
Here is how the two compare on the things people care about most:
| Feature | Medicare Supplement (Medigap) | Medicare Advantage |
|---|---|---|
| Monthly premium | Higher; often well over $100 a month, based on your age, state, and plan | Often low; many plans charge $0 beyond Part B |
| Costs when you get care | Very low; Plan G leaves you only the Part B deductible | Copays and coinsurance, up to the plan’s yearly cap |
| Worst-case yearly medical bill | Small and easy to predict | Up to $9,850 in network in 2027 (PPOs: up to $14,800 combined) |
| Choice of doctors | Any doctor or hospital in the U.S. that takes Medicare | Usually only doctors in the plan’s network |
| Referrals and approvals | No referrals; little prior approval | Often needs referrals (HMOs) and prior approval for some care |
| Drug coverage | Not included; buy a separate Part D plan | Usually built in |
| Dental, vision, hearing | Not included | Often included, with limits |
| Travel | Works across the country; some plans help in other countries | Often limited to your local area, except emergencies |
| Changing plans later | May require health questions in most states | Can switch each fall with no health questions |
Pros of a Medicare Supplement
- Freedom to choose. I like that you can see any doctor in the country who takes Medicare. No networks.
- Few surprise bills. With Plan G, once you pay the Part B deductible, your approved medical costs are covered for the year.
- Easy budgeting. Your costs are mostly your monthly premium. That is easy to plan for.
- No permission slips. You usually don’t need the insurance company to approve a treatment first.
- Great for snowbirds. It works the same in Florida as it does in Ohio.
Cons of a Medicare Supplement
- Higher monthly premiums. You pay for Part B, your Medigap plan, and a Part D plan. That adds up.
- Premiums can go up with age. Many plans raise prices as you get older.
- No extras. Dental, vision, and hearing are not covered.
- Harder to get later. Outside your first enrollment window, most states let companies ask health questions and say no.
Pros of Medicare Advantage
- Low monthly cost. Many plans have a $0 premium, in addition to your Part B premium.
- All in one. Hospital, medical, and usually drug coverage come in one plan with one card.
- Bonus benefits. Many plans include dental, vision, hearing, fitness programs, or rides to appointments.
- A yearly safety cap. Every plan must cap your in-network costs. Original Medicare alone has no cap.
Cons of Medicare Advantage
- Networks. If your doctor leaves the network, you may need a new one.
- Prior approval. The plan may have to approve certain care before you get it, like some scans or a stay at a rehab center.
- Costs add up when you are sick. Copays for hospital stays, scans, and specialists can quickly climb toward the yearly cap.
- Plans change every year. Your premium, copays, drug list, and doctors can all change on January 1.
Who Each Option Fits Best in 2027
There is no single “best” plan. The best plan fits your life. Here is how I would sort it out.
A Medicare Supplement may fit you best if you:
- Have health problems now, or worry about big bills later
- Want to keep a doctor or specialist who might not be in a local network
- Travel a lot or live in two states during the year
- Can afford a higher monthly premium for peace of mind
- Don’t want to deal with referrals or approvals
- Are turning 65 now and can get any Medigap plan without health questions
Medicare Advantage may fit you best if you:
- Are fairly healthy and don’t see doctors very often
- Need to keep your monthly costs as low as possible
- Like your local doctors, and they are in the plan’s network
- Want dental, vision, or hearing benefits in the same plan
- Like having one card and one company to call
- Have enough savings to cover the plan’s yearly cap in a bad year
A Simple Cost Example
Let me show you how the math works. These are rough examples, not real quotes.
Healthy year: You see your doctor twice and get your yearly checkup.
- With Medigap Plan G, you might pay about $150 a month for the plan, or $1,800 a year, plus the Part B deductible.
- With a $0-premium Medicare Advantage plan, you might pay only a few small copays.
- Winner: Medicare Advantage.
Hard year: You have surgery, a hospital stay, and weeks of therapy.
- With Plan G, you still pay about $1,800 in premiums plus the Part B deductible (projected at $292). That is close to your total.
- With Medicare Advantage, your copays could reach the plan’s in-network cap. That could be $6,500 or more, and up to $9,850.
- Winner: Medigap.
So I always ask myself one question: “Would I rather pay more now to be safe, or pay less now and take a chance?” Your answer tells you a lot.
Questions People Ask Me Most
Q: When can I change my plan for 2027?
A: The main window is the Annual Enrollment Period. It runs from October 15 to December 7, 2026, and changes start January 1, 2027. If you are already in a Medicare Advantage plan, you get one more chance from January 1 to March 31, 2027. During that time, you can switch to another Advantage plan or go back to Original Medicare.
Q: Can I switch from Medicare Advantage back to a Medigap plan whenever I want?
A: This is the question I want you to think about most. You can go back to Original Medicare during the enrollment windows. But getting a Medigap plan is different. In most states, if you are past your first Medigap window, the company can ask about your health. It can charge you more or say no.
There are some exceptions. For example, if you tried Medicare Advantage for the first time when you turned 65, you often have up to 12 months to switch back with a guaranteed right to buy Medigap. A few states also have extra protections. Check your state’s rules before you leave a Medigap plan.
Q: When is the best time to buy a Medigap plan?
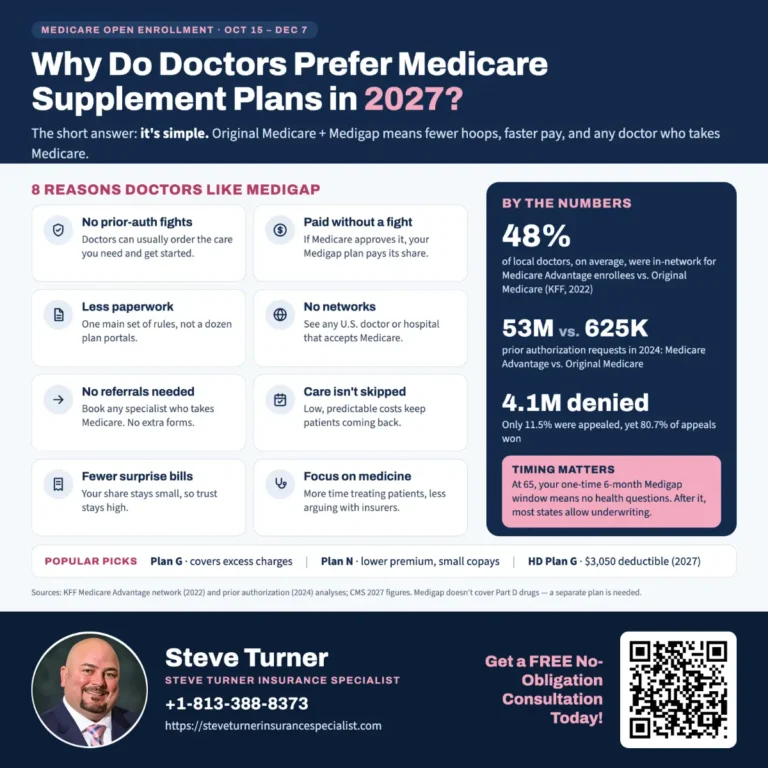
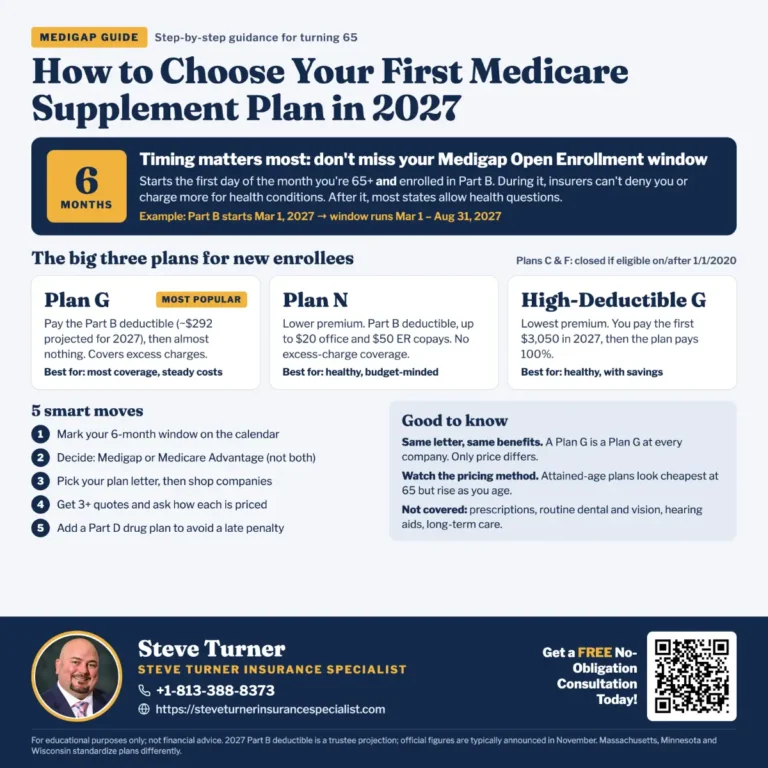
A: The best time is your Medigap Open Enrollment Period. It lasts six months and starts the month you are 65 or older and have Part B. During this time, a company can’t turn you down or charge you more because of your health. I tell everyone not to miss this window.
Q: Do I still pay the Part B premium if I join Medicare Advantage?
A: Yes. Almost everyone pays the Part B premium, no matter which path they choose. A “$0 premium” Advantage plan means the plan itself costs $0 extra. You still pay Part B.
Q: Which Medigap plan is the most popular?
A: For people new to Medicare, Plan G is the most popular. It covers almost everything except the Part B deductible. Plan N costs less each month, but you pay some copays at the doctor and the emergency room. Plan F covers the Part B deductible too, but you can only buy it if you were eligible for Medicare before January 1, 2020.
Q: Is High-Deductible Plan G a good deal?
A: It can be. The monthly premium is much lower than regular Plan G, but you pay out of pocket until you reach $3,050 in 2027. I think it works best for healthy people who have savings to cover that amount in a bad year.
Q: Do Medicare Advantage plans cover prescription drugs?
A: Most do. Just check the plan’s drug list, called a formulary, to make sure your medicines are on it. Also check which pharmacies offer the best prices.
Q: Where can I get free help?
A: Here are three places I trust:
- Medicare.gov Plan Finder lets you compare plans in your ZIP code.
- 1-800-MEDICARE (1-800-633-4227) answers questions 24 hours a day.
- Your State Health Insurance Assistance Program (SHIP) gives free, unbiased advice from trained counselors.
My Step-by-Step Checklist for Choosing in 2027
When I help someone make this choice, I walk through these steps in order:
- List your doctors. Write down every doctor, specialist, and hospital you use. Then check if they are in each Advantage plan’s network.
- List your medicines. Write down each drug, the dose, and how often you take it. Use the Medicare Plan Finder to see what each plan would cost you.
- Think about your health. Do you have a long-term illness? Any surgery coming up? The more care you expect, the more Medigap makes sense.
- Look at your budget. Can you pay a higher monthly premium? Or could you handle a bill of several thousand dollars in a bad year?
- Think about travel. If you spend months away from home, Medigap is usually easier.
- Check your timing. If you are new to Medicare, your Medigap window is your best chance to get any plan you want.
- Read the fine print. For Advantage plans, check the yearly cap, specialist copays, hospital copays, and which services need approval.
- Get free advice. Call your SHIP office or 1-800-MEDICARE before you sign up.
Final Thoughts: Which One Fits You Best?
Here is my honest take. If you can afford it and you are new to Medicare, I lean toward a Medicare Supplement like Plan G. It gives you freedom, few surprises, and protection for the years ahead, when health needs often grow. It is also hard to get later if you pass on it now.
But Medicare Advantage can be a smart choice too. It works well if you are healthy, your doctors are in the network, and you want low monthly costs with extra benefits. Just make sure you can pay the plan’s yearly cap if you have a tough year.
The most important thing is to choose on purpose. Don’t just keep your plan because it is easy. Plans change every year, and so do our lives. Take an hour this fall, before December 7, to compare your options. Your future self will thank you.
Why choose Steve Turner Insurance Specialist?
Because I’m an “Insurance Specialist.” An “insurance specialist” is a broad term that includes insurance agents and insurance brokers, but the key difference is who the agent represents versus who the broker represents.
An “insurance agent” works directly for an insurance company and sells its specific policies to clients.
An “insurance broker” acts as an independent intermediary, comparing policies from multiple companies to find the best fit for their client’s needs, essentially representing the client rather than the insurance company.
I am both a licensed Insurance Agent and a licensed Insurance Broker.
My number one goal in life is to help people and ensure, without a shadow of a doubt, that you and your family are secure and protected. I will always be by your side, helping you mitigate risk by providing the industry’s best and most affordable insurance solutions.
I will find insurance plans for the entire family to help cover whatever life throws at you. I can help you save on severe medical emergencies, find a health insurance plan with low- or no-cost doctor visits and affordable prescription medications, and protect your family in the event of an unexpected accident or illness.
Best of all, it doesn’t cost you anything extra to use an experienced Insurance Agent and Broker like me to help you find the Insurance Plans that fit your individual, family, or business needs.
The companies that sell the insurance plans “you choose“ pay me – you don’t pay me. Calling any big insurance company directly won’t get you a lower price, as they will forward your call to the next available insurance agent on their list. You won’t have had any opportunity to learn about the insurance agent you’re speaking with in advance, understand their qualifications or experience level, or make an informed choice about who you want to work with.
Tap the Contact Me text or icon and get in touch by phone or email, or schedule a “No Obligation” chat through my calendar. I look forward to speaking with you!
OUR CLIENT REVIEWS


CONTACT STEVE TURNER INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a longstanding member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable Healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7 a.m. to 8 p.m.
Tuesday: 7 a.m. to 8 p.m.
Wednesday: 7 a.m. to 8 p.m.
Thursday: 7 a.m. to 8 p.m.
Friday: 7 a.m. to 8 p.m.
Saturday: 7 a.m. to 8 p.m.
Sunday: 7 a.m. to 8 p.m.
SOCIAL FOLLOW + SHARE
MEDICARE SUPPLEMENT POSTS
INSURANCE OFFERINGS
Medicare Supplement vs. Medicare Advantage: Which Fits You Best in 2027?
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
MEDICARE STATEMENT
The Medicare Annual Enrollment Period is October 15th to December 7th. Steve Turner is not connected with or endorsed by the United States Government or the Federal Medicare Program. Some plans may not be available in your area, and any information I provide is limited to those offered. Please contact Medicare.gov or 1-800-MEDICARE for information on all your options.
There’s no one-size-fits-all answer. Carefully evaluate your health status, anticipated medical needs, prescription drug usage, budget, preferred doctors and hospitals, and tolerance for network rules. During the Medicare Annual Enrollment Period (October 15th to December 7th), research the specific plans available in your Florida county using the Medicare Plan Finder on Medicare.gov, compare costs and benefits, and consider free, personalized counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program.