
Tap the button below to get your FREE Medicare Advantage & Medicare Supplement Quote from Steve Turner.
Medicare Plan K Insurance

Medicare Plan K Insurance
Medicare Plan K: What It Covers, What It Costs, and If It’s Right for You
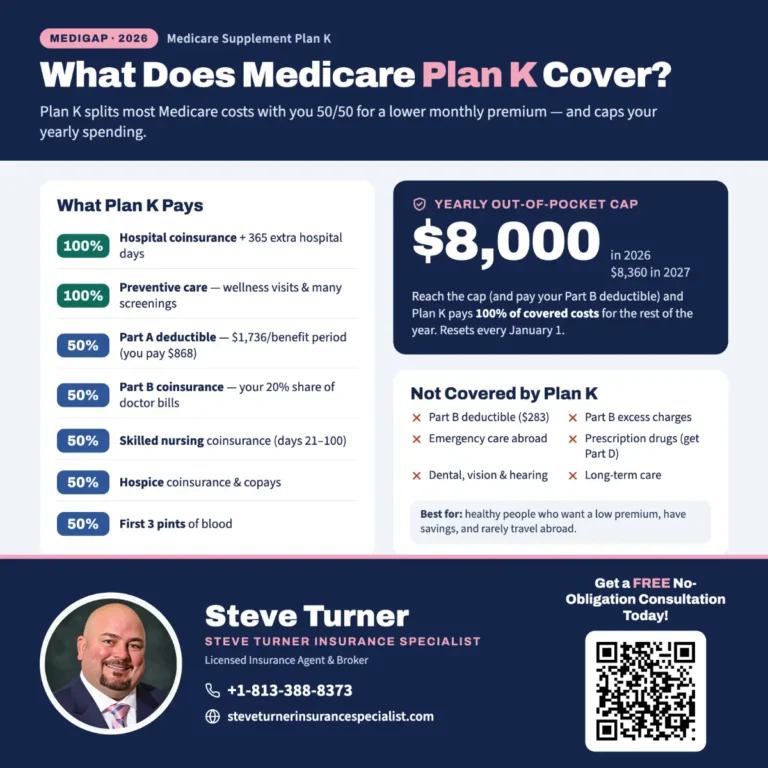
Medicare Plan K is a Medigap plan with a low monthly price and a yearly cap on what you pay. In 2026, that cap is $8,000. In 2027, it goes up to $8,360. Once you hit it, the plan pays 100% of covered costs for the rest of the year.
Hi, I’m Steve Turner, a licensed Medicare agent with Steve Turner Insurance Specialist. I help people sort out their Medicare choices every day. And I hear this question a lot: “What is Medicare Plan K, and should I get it?”
That’s a smart question. Plan K is one of the least talked-about Medigap plans. But for the right person, it can save a lot of money each month.
On this page, I’ll walk you through Plan K in plain words. No fancy terms. No sales pressure. Here’s what you’ll learn:
- What Plan K is and how it works
- What it covers (and what it doesn’t)
- What it costs and how the yearly cap protects you
- Who Plan K is a good fit for, and who should skip it
- How Plan K stacks up against Plans G, N, and L
- When to sign up and how I can help, at no cost to you
By the end, you’ll know if Plan K belongs on your short list. And if you want help, I’m just a phone call away at [Phone Number].
What Is Medicare Plan K?
Plan K is a Medicare Supplement plan. Some people call these plans “Medigap.” They help pay the bills that Original Medicare (Parts A and B) leaves behind.
Here’s the simple version. Original Medicare pays a big part of your health bills. But it doesn’t pay all of it. You still owe deductibles, copays, and a 20% share of most doctor bills. And with Original Medicare alone, there’s no limit on how much you could owe in a year.
That’s where a Medigap plan comes in. It picks up some or all of those leftover costs.
Most Medigap plans pay those costs in full. Plan K is different. It splits most costs with you, 50/50. In return, you get a lower monthly premium.
Think of it like sharing a pizza bill with a friend. You each pay half. But Plan K also has a rule that protects you: once your share hits the yearly cap, Plan K pays the whole bill for the rest of the year.
What Plan K Covers
Every Plan K works the same way, no matter which insurance company sells it. The government sets the benefits. Here’s what Plan K pays:
- Part A hospital coinsurance: 100%, plus up to 365 extra hospital days after Medicare runs out
- Part A hospital deductible: 50% (that’s $868 of the $1,736 deductible in 2026)
- Part B coinsurance and copays: 50% (but 100% for Medicare-covered preventive care)
- Skilled nursing facility coinsurance: 50%
- Hospice care coinsurance: 50%
- First 3 pints of blood: 50%
What Plan K Does Not Cover
I always want my clients to know the gaps up front. Plan K does not pay for:
- The Part B deductible. You pay this yourself. It’s $283 in 2026.
- Part B excess charges. Some doctors charge up to 15% more than Medicare allows. Plan K won’t cover that extra.
- Foreign travel emergencies. If you get sick outside the U.S., Plan K won’t help.
- Prescription drugs. No Medigap plan covers these. You’ll want a separate Part D drug plan.
- Dental, vision, and hearing. Original Medicare and Medigap don’t cover routine care like cleanings, glasses, or hearing aids.
Good news: you can see any doctor or hospital in the U.S. that takes Medicare. There are no networks. No referrals. That freedom is one of the best parts of any Medigap plan.
How Much Does Medicare Plan K Cost?
Plan K usually has one of the lowest monthly premiums of any Medigap plan. That’s its biggest selling point. But the premium is only one part of your cost. Let me break it all down.
1. Your Monthly Premium
This is what you pay the insurance company each month. The price depends on a few things:
- Your age
- Your ZIP code
- Whether you use tobacco
- Your gender (in most states)
- The insurance company you pick
- How the company sets prices as you age
Here’s a tip many people miss. Plan K is the same plan no matter who sells it. So two companies can sell the same coverage at very different prices. That’s why I shop several companies for you. Why pay more for the same thing?
2. Your Share of the Bills
On top of the premium, you pay:
- The Part B deductible ($283 in 2026)
- Half of most other costs Medicare doesn’t pay
3. The Yearly Out-of-Pocket Cap
This safety net makes Plan K special. Only two Medigap plans have one: Plan K and Plan L.
| Year | Plan K yearly cap | Plan L yearly cap |
|---|---|---|
| 2027 | $8,360 | $4,180 |
| 2026 | $8,000 | $4,000 |
| 2025 | $7,220 | $3,610 |
Once you meet the yearly cap and your Part B deductible, Plan K pays 100% of covered services for the rest of the calendar year. The cap resets every January 1. Your monthly premiums do not count toward the cap.
A Real-Life Example
Let’s say it’s 2026. You have Plan K. Here’s how a few bills might play out:
- You go to the hospital. The Part A deductible is $1,736. Plan K pays half. You pay $868.
- You see a specialist a few times. After your $283 Part B deductible, Medicare pays 80% of the bills. Say your 20% share comes to $400. Plan K pays half, so you pay $200.
- You get your yearly wellness visit and flu shot. You pay $0. Plan K covers preventive care in full.
In this year, you’d pay about $1,351 out of pocket, plus your premiums. That’s far below the $8,000 cap.
Now picture a really bad year, with a cancer diagnosis or a long hospital stay. Your costs could climb fast. But they stop at the cap. After that, Plan K covers the rest of your covered bills.
Is Plan K Right for You?
Plan K is a great fit for some people and a poor fit for others. After years of helping folks with Medicare, I’ve noticed a clear pattern.
Plan K Is Often a Good Fit If You:
- Are healthy and rarely see the doctor. You’ll pay a low premium and won’t use much care. That’s money saved every month.
- Want to keep monthly costs low. Maybe you’re on a fixed income. A smaller premium can make your budget easier.
- Have savings to cover a bad year. You’re okay paying more when you’re sick, as long as there’s a limit.
- Want to pick any doctor. You don’t want to deal with networks or referrals like many Medicare Advantage plans have.
- Like knowing your worst case, the yearly cap tells you the most you’ll pay for covered care. That brings peace of mind.
Plan K May Not Be a Good Fit If You:
- Have a long-term health problem. If you see doctors often, those 50% shares add up quickly.
- Get regular treatments. Things like dialysis, chemo, or physical therapy can push you toward the cap each year.
- Travel outside the U.S. Plan K has no foreign travel coverage.
- See doctors who charge excess fees. Plan K won’t cover those.
- Hate surprise bills. If you want one price and to be done, a plan with fuller coverage may suit you better.
Plan K Pros and Cons at a Glance
| Pros | Cons |
|---|---|
| Low monthly premium | You pay 50% of most costs |
| Yearly cap on covered costs | The cap is high ($8,000 in 2026) |
| 100% of preventive care | No Part B deductible coverage |
| Any doctor who takes Medicare | No foreign travel coverage |
| Same benefits from every company | No Part B excess charge coverage |
Here’s how I put it to my clients. Plan K is like a high-deductible plan with a safety net. If you stay healthy, you win. If you get very sick, you’re still protected. You pay more along the way than with a richer plan.
Plan K vs. Other Medicare Plans
Plan K makes the most sense when you compare it side by side with other choices. Here’s how it stacks up against the plans I get asked about most.
| Benefit | Plan K | Plan L | Plan N | Plan G |
|---|---|---|---|---|
| Monthly premium | Lowest | Low | Medium | Highest |
| Part A deductible | 50% | 75% | 100% | 100% |
| Part B coinsurance | 50% | 75% | 100% (small copays) | 100% |
| Part B deductible | No | No | No | No |
| Part B excess charges | No | No | No | 100% |
| Foreign travel emergency | No | No | 80% | 80% |
| Yearly out-of-pocket cap (2026) | $8,000 | $4,000 | None | None |
Plan K vs. Plan G
Plan G is the most popular Medigap plan for new enrollees. After you pay the Part B deductible, Plan G pays almost everything. But you pay a much higher premium.
So the question is simple. Would you rather pay more each month and almost nothing when you’re sick? Or pay less each month and more when you’re sick? Plan G is the first. Plan K is the second.
Plan K vs. Plan N
Plan N sits in the middle. It costs less than Plan G. It pays all your hospital costs. But you pay small copays: up to $20 for some office visits and up to $50 for ER visits that don’t lead to a hospital stay. For many people, Plan N is a happy middle ground.
Plan K vs. Plan L
Plan L is Plan K’s close cousin. It pays 75% of costs instead of 50%. Its yearly cap is half as high. In return, the premium is a bit higher than Plan K. If you want a lower cap but still want to save, Plan L is worth a look.
Plan K vs. Medicare Advantage
Medicare Advantage (Part C) is a whole different path. These plans replace Original Medicare. Many have $0 premiums and include extras like dental or drug coverage. But most use networks, and many need prior approval for care.
Plan K works with Original Medicare. You can see any provider in the country who takes Medicare. No networks. No referrals. That’s a big deal for people who travel within the U.S. or live in another state part of the year.
I’m licensed to offer both types of plans. So I’ll tell you honestly which path best fits your life.
When Can You Sign Up for Plan K?
Timing matters a lot with Medigap. Sign up at the right time, and you get the best deal and can’t be turned down. Wait too long, and it can get harder.
Your Best Window: Medigap Open Enrollment
Your Medigap Open Enrollment Period lasts 6 months. It starts the month you’re 65 or older and enrolled in Medicare Part B. During this time:
- Insurance companies must sell you any Medigap plan they offer
- They can’t charge you more because of health problems
- They can’t make you wait for coverage of past health issues (in most cases)
This is a once-in-a-lifetime window. I always tell people not to let it slip by.
What If You Missed It?
You can still apply for Plan K later. But in most states, the company can ask health questions. They may charge more or decline your application. Some states have special rules that give you more chances to switch. Certain life events, like losing employer coverage, can also give you a special right to buy a plan. I’ll check what applies to you.
A Quick Note About Fall Open Enrollment
The fall Medicare Open Enrollment runs from October 15 to December 7. That window is for Medicare Advantage and Part D drug plans. It does not give you a free pass to switch Medigap plans. Many people mix these up. But fall is still a great time to review your drug plan if you have Plan K.
How I Help You Choose and Enroll
Working with me costs you nothing. Insurance companies pay me, and your plan costs the same whether you use me or not. Here’s what I do for you:
- Listen first. I learn about your health, doctors, budget, and worries.
- Run the numbers. I show you what Plan K would cost in a good year and a bad year, next to other plans.
- Shop the market. I compare Plan K prices from several top-rated companies in your area.
- Check your drugs. I help you find a Part D plan that covers your prescriptions at a fair price.
- Handle the paperwork. I help you apply and make sure everything is set up right.
- Stay with you. Have a billing question next year? Rates going up? Call me. I’m here for the long haul.
My goal is simple. I want you to feel confident in your choice, not confused or pushed.
Let’s Find Out If Plan K Is Right for You
Plan K can save you real money each month while still protecting you from a huge bill in a bad year. But the only way to know if it’s your best choice is to look at your own numbers.
That’s where I come in. In one short call, I’ll:
- Answer your Medicare questions in plain English
- Compare Plan K prices from top companies near you
- Show you how Plan K stacks up against Plans G, N, and L for your situation
- Help you enroll, at no cost to you
There’s no pressure and no obligation. Just honest help from someone who does this every day.
Medicare PLAN K INSURANCE AGENT AND BROKER
As your Insurance Agent and Broker serving you, my goal is to “help you” and ensure, without a shadow of a doubt, that you and your family are secure and protected from risk. As a licensed Medicare Advantage and Medicare Supplement agent, I take the burden off your shoulders by conducting a thorough needs analysis and researching the benefits that best suit you.
I can help you save on severe medical emergencies and find a plan that offers low- to no-cost doctor visits, prescription medication, and extra benefits such as dental, vision, and hearing, gym membership, and over-the-counter items. I will show you plans where your doctors are in-network and provide a side-by-side comparison of your prescription costs across plans.
Medicare is constantly changing, and I work tirelessly to stay informed about the latest market developments. Every year brings new government regulations, new or modified coverages, and new techniques for controlling benefit costs. To best serve their clients, professionals must understand each benefit or program’s provisions, advantages, and limitations to support economic security.
I am a long-standing member of the National Association of Benefits and Insurance Professionals® (NABIP.ORG) and hold the Registered Employee Benefits Consultant® designation (https://nabip.org/professional-development/rebc-designation). I can provide information on your market’s availability and any expected changes.
After you choose your Medicare Insurance plan, I provide ongoing support year-round; you won’t have to call an (800) number anymore.
If you have questions, issues, or concerns about your plan’s benefits, you can contact me by phone, text, or through my simple-to-use email contact form using the buttons below.
Steve Turner, your Helpful Licensed Agent and Broker
Medicare Plan K Insurance FAQ
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, LICENSED INSURANCE AGENT & BROKER
Questions? Call, text, or book a time below; I answer calls and emails 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
EMAIL ME: 24×7
OFFICE LOCATION
Address: 14502 N Dale Mabry Hwy, Suite 200, Tampa, FL 33618
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
SERVICE AREA FACTS UNITED STATES
The United States: Facts and Top Visitor Sites
The United States of America is a vast, diverse country with a wide array of cultures, landscapes, and iconic landmarks. Here are some key facts and top attractions:
Facts about the USA
The United States is a vast, diverse country with a rich tapestry of culture, history, and natural beauty. Here is a comprehensive overview of key statistics and top visitor attractions across the nation.
Key U.S. Statistics and Economic Overview
The United States is a global leader in population, economy, and innovation, attracting people from all over the world.
- Population and Demographics: As of 2025, the U.S. population is projected to exceed 343 million, making it the world’s third-most populous country. The population is diverse, with a significant Hispanic and Latino population that accounts for much of the recent growth. The median age is around 39 years, and a growing segment of the population is over 65, reflecting an aging nation.
- Geography: Third largest country by land area, behind Russia and Canada. It spans 3.8 million square miles and has 4 million miles of roads.
- National Parks: 63 national parks nationwide.
- Government-owned Land: The government owns 37% of the land (federal, state, and local).
- Diversity: The U.S. is a diverse country, with a growing non-white population. Non-Hispanic white people currently make up the largest ethnic group, but their share of the population has decreased over time. The Hispanic population has grown the most, increasing by 23% between 2010 and 2020.
- Languages: While English is the primary language, Spanish is the most common non-English language spoken at home, followed by Chinese and Tagalog.
- Aging Population: Americans are living longer, and the 65-and-older population is increasing significantly.
- Economy & Key Industries: The U.S. economy is the largest in the world by nominal GDP. Its economic strength is built on several key industries:
- Financial Services: This sector is a global powerhouse, centered in cities like New York, with major hubs for banking, insurance, and investment.
- Technology and Information Technology (IT): The U.S. leads the world in technology, with major tech hubs in Silicon Valley, Austin, and Seattle driving innovation in software, hardware, and digital services.
- Healthcare and Social Assistance: As the country’s largest private employment sector, healthcare is a massive industry with high demand for skilled workers and ongoing innovation.
- Manufacturing: The U.S. manufacturing sector is a backbone of the economy, producing everything from automobiles and aerospace components to medical equipment and consumer goods.
- Work-from-Home Trends: More Americans work remotely than before the pandemic. In 2022, 15% of Americans worked from home, up from 6% in 2019.
Top Places for Visitors to Explore in the USA
The United States offers an incredible variety of destinations, from iconic cities to breathtaking national parks.
- New York City, New York: A global icon, New York City is famous for its vibrant culture, world-class museums, and iconic landmarks. Visitors can explore Times Square, see a Broadway show, visit the Statue of Liberty, and walk through Central Park. The city offers an endless array of dining and shopping experiences.
- The Grand Canyon, Arizona: A breathtaking natural wonder carved by the Colorado River, the Grand Canyon National Park is a must-see. Visitors can take in panoramic views from the South Rim, hike into the canyon, or take a helicopter tour for a unique perspective.
- Las Vegas, Nevada: Known as “The Entertainment Capital of the World,” Las Vegas is famous for its casinos, luxury hotels, and spectacular live shows. The Las Vegas Strip is a bustling boulevard with unique attractions and a vibrant nightlife.
- Orlando, Florida: The “Theme Park Capital of the World,” Orlando is home to some of the world’s most famous attractions, including Walt Disney World Resort and Universal Orlando Resort. It is a top destination for families and anyone seeking a thrilling, magical vacation.
- Washington, D.C.: The nation’s capital is a city of history and monuments. Visitors can explore the National Mall, which connects the Lincoln Memorial, Washington Monument, and the U.S. Capitol. It’s also home to the Smithsonian Institution’s world-class museums.
- Yellowstone National Park, Wyoming: As the first national park in the U.S., Yellowstone National Park is a marvel of geothermal activity and wildlife. It is home to the famous Old Faithful geyser, the Grand Prismatic Spring, and a wide variety of animals, including bison, bears, and wolves.
- San Francisco, California: This iconic West Coast city is famous for the Golden Gate Bridge, its historic cable cars, and diverse neighborhoods. Visitors can explore Fisherman’s Wharf, Alcatraz Island, and the beautiful Golden Gate Park.
- Hawaii: An archipelago in the Pacific Ocean known for its stunning natural beauty, volcanic landscapes, and rich Polynesian culture. Visitors can relax on beautiful beaches, hike through lush rainforests, and explore the Hawaii Volcanoes National Park on the Big Island.
- Great Smoky Mountains National Park, North Carolina/Tennessee: The Great Smoky Mountains National Park is the most visited national park in the U.S. and is known for its beautiful mountains, diverse plant and animal life, and rich Appalachian culture.
- New Orleans, Louisiana: This historic city on the Mississippi River is famous for its unique blend of cultures, live music, and vibrant festivals. The French Quarter is a lively neighborhood with historic architecture, delicious Creole cuisine, and jazz clubs.
MEDICare PLAN K INSURANCE POSTS
SERVICE AREA
Medicare plan availability differs by state and county. Steve Turner is licensed in AL, CO, FL, GA, NC, SC, TN, and TX.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
MEDICARE DISCLAIMER
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
Steve Turner
Steve Turner, CLU®, REBC® is licensed in AL, CO, FL, GA, NC, SC, TN, and TX · NPN 18030539 · Florida License W333468
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals NABIP®. Steve holds the Registered Employee Benefits Consultant® (REBC®) designation. Steve also holds the “Chartered Life Underwriter” designation (CLU®), a professional credential for individuals specializing in life insurance and estate planning, conferred by the American College of Financial Services. Since 2016 (over 10 years), Steve has helped individuals, families, Medicare beneficiaries, and small businesses find the right coverage to meet their needs. Steve has earned 180+ Google reviews from happy clients.
Steve Turner is a licensed agent appointed by Florida Blue in Florida.