
Can I Get Medicare Without Social Security

Can I Get Medicare Without Social Security
Can I Get Medicare Without Social Security? An Expert’s Definitive Guide
Section 1: Introduction: Separating Two Pillars of American Retirement
Whether you can enroll in Medicare without receiving Social Security retirement benefits is one of the most critical and frequently misunderstood aspects of retirement planning in the United States. The answer is unequivocally yes. It is not only possible but also a common and often financially prudent strategy to enroll in Medicare at age 65 while deferring Social Security income benefits to a later age. This separation, however, causes significant confusion because of the intertwined administrative relationship between two fundamentally distinct federal programs.
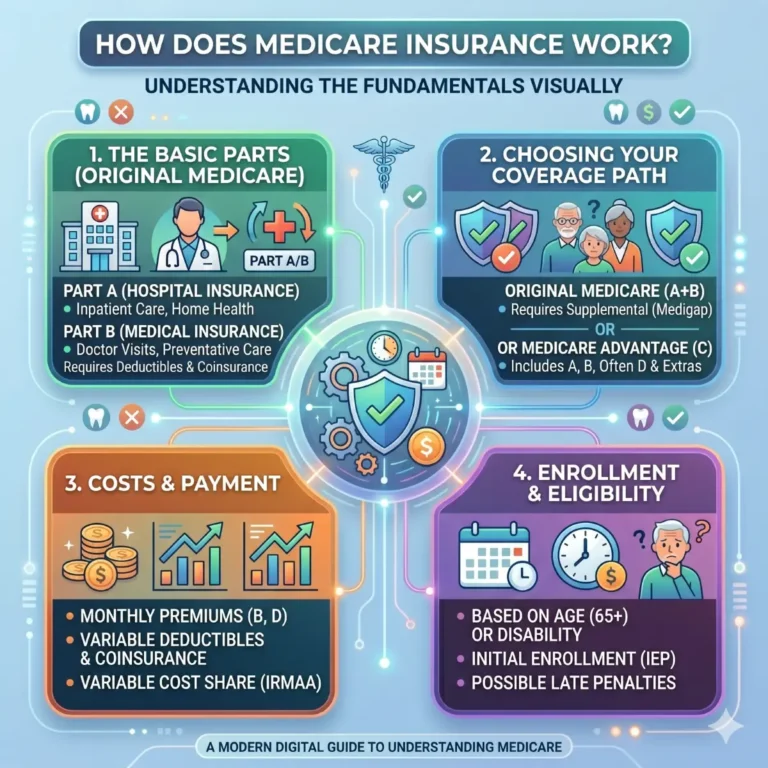
Social Security is an income replacement program designed to provide a financial foundation in retirement, with eligibility for reduced benefits beginning as early as age 62 and full benefits at a designated “full retirement age,” which is now 67 for those born in 1960 or later. Medicare, conversely, is a federal health insurance program primarily for individuals aged 65 or older, as well as for younger people with certain disabilities or medical conditions. The critical point of intersection—and confusion—is that the Social Security Administration (SSA) handles the enrollment process for Original Medicare, which consists of Part A (Hospital Insurance) and Part B (Medical Insurance).
This administrative linkage has inadvertently fostered a pervasive and potentially costly public misconception. Because the SSA manages both programs, many individuals logically but incorrectly assume that the timelines and eligibility for both are perfectly aligned. This creates a “passivity trap,” where individuals not yet engaging with the SSA for retirement income believe they do not need to engage with the SSA for healthcare coverage. The reality is starkly different. For those not actively drawing Social Security benefits as they approach their 65th birthday, the government’s operational convenience for one group of retirees creates a dangerous knowledge gap for another. The system, in effect, shifts the burden of timely enrollment and penalty avoidance onto individuals who are often making the sound financial decision to delay Social Security to maximize their future monthly payments. Consequently, Medicare enrollment for this population is not automatic or passive. It is a proactive, high-stakes process that demands meticulous planning, an understanding of critical deadlines, and decisive action to secure essential healthcare coverage and avoid severe, lifelong financial penalties.
Section 2: The Mechanics of Enrollment: The Two Paths to Medicare Coverage
The Medicare enrollment system is fundamentally bifurcated, creating two distinct pathways to coverage. The path an individual follows depends not on their healthcare needs or eligibility for the program itself, but on a single administrative status. Whether they are receiving Social Security or Railroad Retirement Board (RRB) benefits at the point of eligibility. This design creates a system of “haves” and “have-nots” in terms of enrollment simplicity. One group is guided into the system automatically, while the other must navigate it manually, assuming full responsibility for compliance, timeliness, and avoiding significant financial repercussions. Understanding which path applies is the foundational step in a successful transition to Medicare.
Subsection 2.1: The Automatic Enrollment Path: When Medicare Comes to You
For a specific segment of the population, enrollment in Medicare Part A and Part B is a seamless, automatic process that requires no action. This “hands-off” path is reserved for individuals already integrated into the federal benefits system before becoming eligible for Medicare. The primary trigger for automatic enrollment is receiving retirement benefits from either Social Security or the RRB for at least four months before an individual’s 65th birthday.
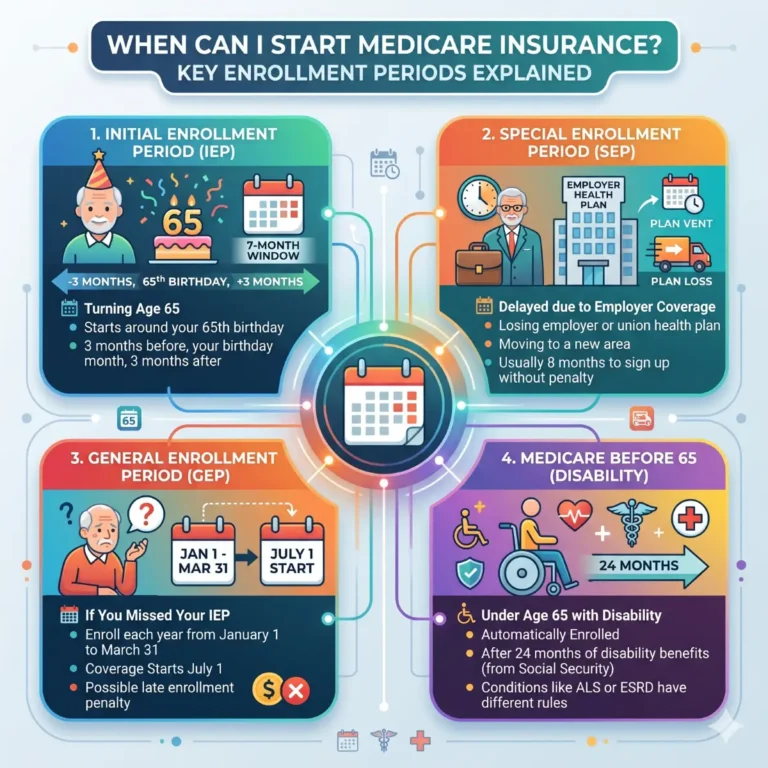
Automatic enrollment also extends to certain individuals under age 65. Specifically, those receiving Social Security Disability Insurance (SSDI) or RRB disability benefits will be automatically enrolled in Medicare Parts A and B after a 24-month waiting period. An exception is made for individuals diagnosed with Amyotrophic Lateral Sclerosis (ALS), also known as Lou Gehrig’s disease; their Medicare coverage begins automatically in the same month that their disability benefits start, with no waiting period.
For those on the automatic path, the process is straightforward. About three months before their Medicare coverage begins, they will receive a “Welcome to Medicare” packet in the mail from the Social Security Administration. This packet includes their red, white, and blue Medicare card, which shows that enrollment in both Part A and Part B is complete and coverage will start on the first day of their 65th birthday month (or the month their eligibility begins, for those with disabilities).
Subsection 2.2: The Manual Enrollment Imperative: When You Must Go to Medicare
Automatic enrollment is the exception, not the rule. A large and growing number of Americans must engage in a “hands-on,” manual enrollment process. This structural inequity places a significant administrative burden on those who have chosen to work longer or strategically delay their retirement benefits—decisions often made for sound financial planning reasons. The system’s architecture does not account for this dynamic and, in effect, penalizes prudent financial planning by introducing complexity and risk. Failing to recognize that you belong to this group is the leading cause of missed deadlines and subsequent penalties.
The following populations will not be automatically enrolled in Medicare and must take proactive steps to sign up:
- Individuals Approaching Age 65 Not Receiving Benefits: This is the largest group and the primary focus of this report. Anyone turning 65 who has not yet started collecting Social Security or RRB retirement benefits must manually enroll in Medicare.
- Individuals Working Past Age 65: Many people continue working beyond their 65th birthday and keep health coverage through their employer. These individuals are not automatically enrolled and must decide when and how to sign up for various parts of Medicare, which involves coordinating with their existing coverage.
- Individuals with End-Stage Renal Disease (ESRD): ESRD qualifies for Medicare at any age, but enrollment is not automatic in most cases. Individuals with ESRD must file an application to start their benefits.
- Residents of Puerto Rico: U.S. citizens residing in Puerto Rico who receive Social Security benefits are automatically enrolled in Medicare Part A. However, they are not automatically enrolled in Part B and must sign up for it manually if they want that coverage.
Subsection 2.3: A Step-by-Step Guide to Manual Enrollment
For those who must manually enroll, the Social Security Administration provides three distinct methods to apply for Medicare Parts A and B. You can file an application for “Medicare only,” which will not trigger the start of Social Security retirement benefits.
- Online Application: This is the most efficient and recommended method. You can access the online application through the Social Security Administration’s official website at ssa.gov/medicare. The process can be completed in as little as 10 minutes and requires no documents to be mailed. The application lets users apply for Medicare benefits without simultaneously filing for retirement income.
- By Phone: Individuals can apply for Medicare by calling the SSA’s national toll-free number at 1-800-772-1213. Representatives can assist with the application process over the phone. This is a viable option for those who are not comfortable with or do not have access to the internet.
- In-Person: Applicants can schedule an appointment to apply in person at their local Social Security office. While this method is available, it is often the least convenient and may involve travel and wait times. It is generally recommended to try the online or phone options first.
Regardless of the method you choose, the key is to act within the prescribed enrollment periods to ensure a smooth transition to Medicare coverage and avoid negative consequences.
Section 3: Navigating Critical Timelines: Your Medicare Enrollment Periods
The Medicare system is governed by strict, unforgiving timelines known as enrollment periods. These periods are not mere suggestions; they are rigid windows of opportunity during which an individual can sign up for coverage. These periods function as a powerful behavioral framework. The seamless coverage start date offered for enrolling early in the Initial Enrollment Period (IEP) serves as a positive reinforcement, incentivizing proactive behavior. Conversely, the built-in coverage gaps and permanent financial penalties associated with the General Enrollment Period (GEP) strongly deter procrastination and inaction. The Special Enrollment Period (SEP) provides a regulated “off-ramp” for a specific group—the actively employed—but its complex and rigid rules create new potential points of failure. Misunderstanding these deadlines can lead to months or even years without health insurance and subject an individual to lifelong financial penalties.
Subsection 3.1: The Initial Enrollment Period (IEP): Your Primary Window of Opportunity
The Initial Enrollment Period is the most critical timeline for anyone new to Medicare. It is a seven-month window tied to an individual’s 65th birthday. The IEP begins three months before the month of one’s 65th birthday, includes the birthday month itself, and extends for three months after the birthday month. For example, if an individual’s 65th birthday is on June 15, their IEP runs from March 1 to September 30.
A crucial nuance exists for individuals whose birthday falls on the first day of the month. In these cases, their entire seven-month IEP is shifted one month earlier. For someone born on June 1, their eligibility is treated as if they were born in May, so their IEP would run from February 1 to August 31.
The timing of enrollment within the IEP directly affects when coverage begins. To ensure coverage starts on the first day of the 65th birthday month, an individual must enroll during the three months before their birthday month. If enrollment occurs during the birthday month or in the three months following it, coverage will now start on the first day of the month after enrollment is completed. This is a recent and beneficial change, as previously, enrolling in the latter part of the IEP could result in a coverage delay of up to three months.
Subsection 3.2: The Special Enrollment Period (SEP): The Exception for the Working Population
The Special Enrollment Period is a vital provision for individuals who continue to work past age 65 and have health coverage through their current employer or a spouse’s current employer. This SEP allows them to delay enrollment in Medicare Part B (and Part A, if they have to pay a premium for it) without incurring a late enrollment penalty.
However, the rules governing this SEP are strict and often misunderstood, creating a “trap door” for even well-intentioned individuals who misinterpret the regulations.
- Creditable Coverage from Active Employment: The health coverage must be based on current, active employment. Coverage from COBRA, retiree health plans, or severance packages does not count as active employment coverage and will not make an individual eligible for an SEP to delay Part B.
- Employer Size Rule: Generally, the employer providing the health coverage must have 20 or more employees for the plan to be considered the primary payer over Medicare. If the employer has fewer than 20 employees, Medicare typically becomes the primary payer at age 65. In this scenario, failing to enroll in Part B during the IEP can result in significant coverage gaps, as the small employer plan may legally refuse to pay for services that Medicare would have covered.
- SEP Timeline: The SEP is an eight-month window that begins the month after the active employment ends or the group health plan coverage ends, whichever occurs first. To avoid a coverage gap, it is highly recommended to enroll in Medicare during the last month of employment, which will ensure Medicare coverage begins on the first day of the following month.
Subsection 3.3: The General Enrollment Period (GEP): The Last Resort
The General Enrollment Period is the enrollment window for individuals who failed to sign up during their IEP and do not qualify for an SEP. This period runs from January 1 through March 31 each year. While the GEP provides a path to coverage, it is deeply flawed, with two significant drawbacks that punish inaction.
- Delayed Coverage: When enrolling during the GEP, Medicare coverage does not begin until the first day of the month after the enrollment is processed. For instance, an individual who enrolls in March will not have coverage until April 1. This can create a substantial and dangerous gap in health insurance.
- Late Enrollment Penalties: Using the GEP to enroll almost guarantees that the individual will be subject to a late enrollment penalty for Part B. If the individual must also pay a premium for Part A and delayed enrollment, they will face a penalty for that as well. These penalties are not a one-time fee; they are a permanent addition to the monthly premiums.
View the GEP as a safety net of last resort, not a viable alternative to timely enrollment during the IEP or a qualifying SEP.
Section 4: A Strategic Analysis: Pros and Cons of Medicare While Deferring Social Security
The decision to enroll in Medicare at 65 while deferring Social Security benefits is not merely procedural; it is a strategic financial choice with significant advantages and potential drawbacks. For the proactive planner, weighing these factors is essential to optimizing both retirement income and healthcare security. The analysis reveals a critical disconnect between government healthcare policy and tax policy, particularly concerning Health Savings Accounts (HSAs), forcing individuals into a high-stakes trade-off between two powerful retirement planning tools.
Subsection 4.1: The Compelling Case for Enrolling in Medicare at 65
For most individuals turning 65 who are not covered by a qualifying employer health plan, the arguments for enrolling in Medicare are overwhelming.
- Pro 1: Avoiding Permanent Financial Penalties: This is the most compelling reason to enroll on time. As detailed later, delaying Medicare Part B enrollment without creditable coverage from active employment triggers a lifelong late enrollment penalty. This penalty permanently increases the monthly Part B premium, eroding retirement income for the rest of one’s life. Timely enrollment is therefore a crucial defensive financial maneuver.
- Pro 2: Securing Comprehensive Health Coverage: For those who are retiring, self-employed, or losing other forms of insurance at age 65, Medicare provides an essential and often more affordable health insurance safety net. Even those who continue to work can benefit from enrolling in premium-free Part A. Part A can act as a secondary payer to an employer plan, potentially covering some or all of the inpatient hospital deductibles and coinsurance left by the primary plan.
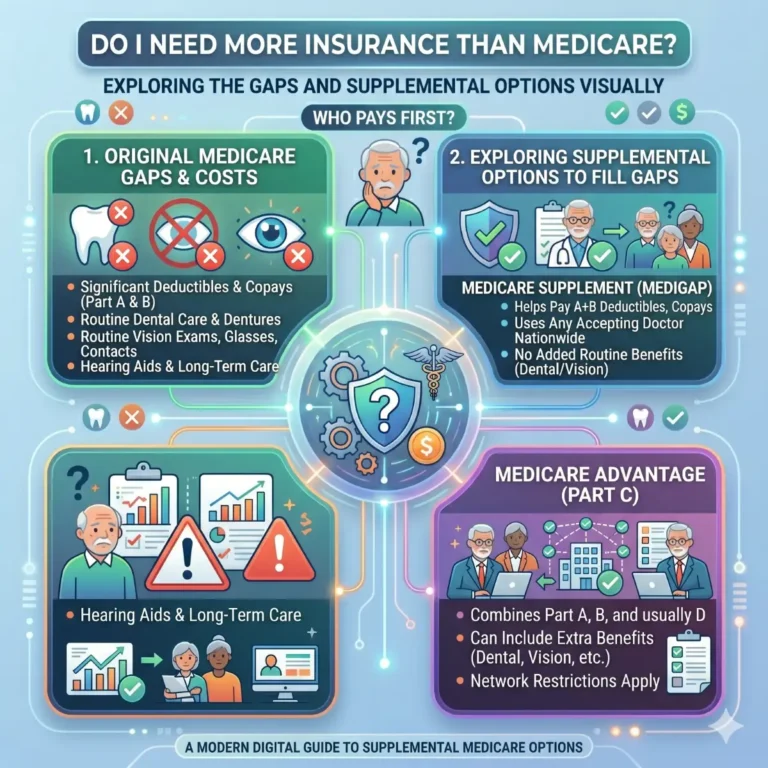
- Pro 3: Unlocking Broader Insurance Options: Original Medicare (Parts A and B) is the foundation of the Medicare system. To buy private insurance products that manage out-of-pocket costs and expand benefits, you must enroll in both parts. These include Medicare Supplement Insurance (Medigap) plans, which cover costs like deductibles and copayments, and Medicare Advantage (Part C) plans, which are all-in-one alternatives that often include prescription drug coverage and other ancillary benefits like dental and vision.
Subsection 4.2: Potential Drawbacks and Critical Financial Conflicts
While the case for timely enrollment is strong, some scenarios create challenges and force complex financial decisions.
- Con 1: The Health Savings Account (HSA) Collision: This is the most significant and financially hazardous drawback for individuals with a high-deductible health plan (HDHP). The conflict arises from a lack of integration between Medicare rules and IRS tax law.
- The Rule: IRS regulations are explicit: an individual is not eligible to make contributions to an HSA for any month in which they are enrolled in any part of Medicare.
- The Trap: The danger lies in a procedural rule within Medicare law. When an individual who has delayed both Medicare and Social Security applies for benefits more than six months after their 65th birthday, Medicare automatically makes their Part A coverage retroactive for up to six months. For example, if someone retires and applies for Medicare at age 65 and 7 months, their Part A coverage will be backdated to their 65th birthday month. This action retroactively nullifies their eligibility to contribute to their HSA for those seven months, making all contributions made during that period “excess contributions.” These are subject to income tax and potential tax penalties. This creates a hidden financial hazard for diligent planners unaware of the retroactivity rule.
- The Strategy: To legally continue making HSA contributions after age 65, an individual must delay enrollment in all parts of Medicare. This strategy is viable only if they have creditable employer-sponsored coverage from an employer with 20 or more employees, which allows them to delay Medicare without penalty. Furthermore, they must also delay applying for Social Security benefits, because applying for Social Security after age 65 automatically triggers enrollment in Part A, which would halt HSA contributions. This forces a difficult choice: forgo the powerful tax advantages of an HSA by enrolling in premium-free Part A, or maintain HSA contributions while navigating the complexities of delaying Medicare.
- Con 2: The Burden of Direct Premium Payments: When Medicare premiums cannot be deducted from a Social Security check, the beneficiary must pay them directly. Medicare typically sends a quarterly bill for Part B premiums. This adds a new administrative task to the retiree’s financial life and carries the risk of a missed payment, which, if not corrected, could lead to termination of coverage.
- Con 3: Complex Coordination with Employer Coverage: For those who continue working past 65 with employer coverage, deciding whether to enroll in only Part A, both Parts A and B, or delay both requires careful analysis. It involves understanding which plan acts as the primary payer, comparing the costs (premiums, deductibles, copays) of the employer plan versus Medicare, and ensuring there are no coverage gaps. This decision is highly individualized and often requires expert guidance.
Section 5: The Financial Landscape: Premiums, Payments, and Penalties
Understanding Medicare’s full financial picture is essential for anyone enrolling without the convenience of automatic premium deductions from Social Security. This includes the costs of each part of Medicare, how to make direct payments, and, most critically, the devastating and permanent financial impact of late enrollment penalties.
Subsection 5.1: Understanding Your Medicare Costs
Medicare costs are multifaceted and can vary significantly based on an individual’s work history and income.
- Part A (Hospital Insurance): For most Americans, Medicare Part A is premium-free. This is granted to individuals who, or whose spouse, have worked for at least 10 years (equivalent to 40 quarters) and paid Medicare taxes during that time. For the small percentage of individuals who do not qualify for premium-free Part A, the monthly premium can be substantial, reaching up to several hundred dollars per month.
- Part B (Medical Insurance): All beneficiaries must pay a monthly premium for Part B coverage. The federal government sets a standard base premium each year. For 2025, the standard Part B premium is $185 per month. This figure, however, is just the starting point for many.
- Income-Related Monthly Adjustment Amount (IRMAA): Medicare premiums for both Part B (medical insurance) and Part D (prescription drug coverage) are subject to an income-based surcharge known as IRMAA. This means that higher-income beneficiaries pay more than the standard premium. The SSA determines IRMAA based on the modified adjusted gross income reported on an individual’s IRS tax return from two years prior. For example, 2025 premiums are based on 2023 income. Individuals with incomes above $106,000 (or couples filing jointly with incomes above $212,000) in 2023 will pay a higher premium in 2025.
Subsection 5.2: How to Pay Your Premiums Without Automatic Deduction
When an individual is enrolled in Medicare but not yet receiving Social Security or RRB benefits, they must pay their premiums directly to the Centers for Medicare & Medicaid Services (CMS). CMS typically sends a quarterly bill, known as the “Medicare Premium Bill” (Form CMS-500). This bill covers three months of Part B premiums (and Part A premiums, if applicable). Beneficiaries have several options for making these payments:
- Online via a Secure Medicare Account: This is the fastest and most direct method. You can make payments through an individual’s secure account on Medicare.gov using a credit card, debit card, or a transfer from a checking or savings account.
- Medicare Easy Pay: This free automatic payment service deducts the monthly premium directly from a designated checking or savings account. It is a reliable “set it and forget it” option that eliminates the need to remember to pay a quarterly bill.
- Online Bill Pay Through a Personal Bank: Individuals can use their own bank’s online bill payment service to send payments to Medicare, just as they would for any other utility or bill.
- Mail: The traditional method of mailing a check, money order, or credit/debit card information, along with the payment coupon at the bottom of the bill, is also available. However, this is the slowest method and carries the risk of mail delays.
Subsection 5.3: The High Cost of Inaction: A Detailed Analysis of Late Enrollment Penalties
The failure to enroll in Medicare promptly results in penalties that are not a one-time fine but a permanent surcharge on monthly premiums. These penalties are among the most punitive in the federal benefits system and are designed to discourage enrollment delays strongly. The rules for each part of Medicare differ in calculation and duration, so it’s essential to understand each one.
Table 1: Medicare Late Enrollment Penalties at a Glance
| Medicare Part | Penalty Calculation | Penalty Duration |
| Part A | 10% increase on the monthly Part A premium. | Paid for twice the number of years the individual was eligible but did not enroll. |
| Part B | 10% of the standard Part B premium for each full 12-month period of delay. | For as long as the individual has Part B coverage (permanent). |
| Part D | 1% of the “national base beneficiary premium” for each full month of delay without creditable drug coverage. | For as long as the individual has Part D coverage (permanent). |
- Part A Penalty: This penalty applies only to the small number of individuals who must pay a premium for Part A and delay enrollment. The penalty is a 10% increase in their monthly premium. They must pay this surcharge for a period equal to twice the number of years they could have had Part A but did not sign up for. For example, a two-year delay in enrollment would require paying the higher premium for four years.
- Part B Penalty: This is the most common and financially damaging penalty. It is assessed on anyone who delays Part B enrollment without having qualifying coverage from active employment. The penalty is a 10% increase on the standard Part B premium for each full 12-month period the individual was eligible but did not enroll. This penalty is permanent and is paid every single month for as long as the person remains enrolled in Part B. For example, an individual who delays enrollment for three full years would face a permanent 30% penalty. Using the 2025 standard premium of $185, the penalty calculation would be: $ $ (\$185.00 \times 0.30 = \$ 55.50$$ This $55.50 penalty would be added to their monthly premium for the rest of their life. The penalty amount is recalculated each year as the standard premium changes, so it will continue to grow over time.
- Part D (Prescription Drug) Penalty: This penalty is levied on individuals who go for 63 consecutive days or more without either a Medicare Part D plan or other creditable prescription drug coverage (like from an employer or VA) after their IEP ends. The penalty is 1% of the national base beneficiary premium (which is $36.78 for 2025) for each full month the individual was without coverage. This amount is then rounded to the nearest $0.10 and added to their monthly Part D premium. Like the Part B penalty, the Part D penalty is also permanent. For example, going 24 months without coverage would result in a penalty of 24% of the base premium, or approximately $8.80 per month in 2025, added to their plan’s premium forever.
Section 6: Conclusion: Taking Control of Your Medicare Journey
The evidence overwhelmingly confirms that obtaining Medicare without Social Security benefits is not only possible but a standard pathway for millions of Americans, particularly those engaged in strategic retirement planning. However, this path demands a fundamental mindset shift—from the passive expectation of automatic enrollment to the active, engaged management of one’s healthcare transition. The administrative convenience that links Social Security and Medicare enrollment has created a critical knowledge gap, placing the onus of timely, correct action squarely on the individual.
A series of critical, non-negotiable steps define the journey to Medicare for those deferring Social Security. First is the self-identification of being on the manual enrollment path, a realization that the system will not act on one’s behalf. Second is precisely calendaring the seven-month Initial Enrollment Period, recognizing it as the primary and most advantageous window to secure coverage without complication. Third is a careful strategic analysis of potential conflicts, most notably the high-stakes trade-off between Medicare enrollment and the ability to contribute to a Health Savings Account. This decision point, born from a disconnect between Healthcare and tax policy, requires a deliberate choice based on individual financial circumstances and long-term goals.
Ultimately, the most important conclusion is that inaction carries a severe and permanent cost. The late enrollment penalties for Medicare Parts B and D are not minor fees but lifelong surcharges that can compound over decades, significantly diminishing retirement income. Proactive enrollment, therefore, should not be viewed as a bureaucratic chore. It is a foundational act of financial self-preservation and a cornerstone of a secure, well-planned retirement. By understanding the rules, respecting the deadlines, and taking decisive action, individuals can navigate this process successfully and protect their health and financial well-being for years to come.
Section 7: Professional Guidance: Purchasing Medicare and Consulting an Expert
Successfully enrolling in Original Medicare (Parts A and B) through the Social Security Administration is the first and most crucial step. However, it is not the last. Original Medicare provides a solid foundation but leaves beneficiaries exposed to high out-of-pocket costs like deductibles, coinsurance, and the full cost of most prescription drugs. The final stage of building a comprehensive retirement healthcare plan is selecting additional coverage from private insurance companies to fill these gaps. Navigating this marketplace can be complex, and guidance from a licensed, independent insurance agent can be invaluable.
Subsection 7.1: How to Purchase Medicare Coverage
Once enrollment in Parts A and B is confirmed, individuals have several avenues to enhance their coverage:
- Medicare Supplement Insurance (Medigap): These are private insurance plans, standardized by the federal government, that work alongside Original Medicare. They help pay for some or all of the out-of-pocket costs that Medicare doesn’t cover, such as the Part A hospital deductible and the 20% coinsurance for Part B services. Medigap plans offer predictable costs and the freedom to see any doctor or visit any hospital in the U.S. that accepts Medicare.
- Medicare Advantage (Part C): These are all-in-one bundled plans offered by private insurers that Medicare approves. They must provide all the same benefits as Original Medicare (Part A and Part B), and most plans also include prescription drug coverage (Part D). Many Medicare Advantage plans offer additional benefits not covered by Original Medicare, such as routine dental, vision, and hearing care. These plans typically use a provider network, such as an HMO or PPO.
- Standalone Prescription Drug Plans (Part D): For individuals who choose to stay with Original Medicare (with or without a Medigap plan), a standalone Part D plan is needed to cover prescription medications. Private insurance companies offer these plans, and they vary widely in monthly premiums, deductibles, and the specific drugs they cover (their formulary).
Subsection 7.2: The Role of a Licensed Agent: A Profile of Steve Turner, Insurance Specialist
Choosing between Original Medicare with a Medigap plan and a Part D plan, or a comprehensive Medicare Advantage plan, has long-term financial and health implications. A licensed, experienced insurance agent can provide personalized, expert guidance to help individuals choose the option that best fits their needs and budget.
For Florida residents, Steve Turner of Steve Turner Insurance Specialist is a highly regarded professional in this field.
- Location: The office is located at 14502 N Dale Mabry Hwy Suite 200, Tampa, FL 33618.
- Expertise: Steve Turner has deep, thorough knowledge of the Medicare landscape and the wide array of health insurance options available. His specialty is simplifying the often-overwhelming process of selecting coverage, communicating complex plan details in an easy-to-understand way that empowers clients to make confident decisions.
- Services: The services offered extend beyond simple plan selection. Steve Turner Insurance Specialist provides personalized consultations to guide clients through the entire Medicare journey, from understanding enrollment rules to comparing Medicare Advantage, Medigap, and Part D plans. The focus is on finding a tailored solution that aligns with each client’s specific health needs and financial situation.
- Client Approach: Reviews consistently highlight exceptional customer service, responsiveness, and a genuine commitment to client well-being. Steve Turner is described not merely as an agent but as a trustworthy advisor and a reliable partner in navigating the complexities of health insurance. This client-oriented approach helps ensure individuals are well-informed and confident in their choices.
- Cost of Services: Consumers should know there is typically no fee for consulting with or using the services of a licensed insurance agent like Steve Turner. These professionals are compensated by the insurance carriers when a plan is selected, so clients receive expert guidance at no direct cost.
Engaging with a professional like Steve Turner is not a sales transaction but a strategic partnership. It is the final, critical step in transforming a complex federal benefit into a personalized, comprehensive healthcare strategy that provides peace of mind throughout retirement.
Finding Your Trusted Advisor in the Florida Medicare Market
We have taken a very detailed look at Medicare for 2026. We’ve seen how its clever design offers a modern solution for today’s retirees. We’ve also seen that while the plan’s benefits are stable and reliable, its monthly cost can vary significantly from one insurance company to another. Choosing the right company at the right price is the key to maximizing the value of Medicare in 2026.
This is where the guidance of an independent, licensed insurance agent becomes invaluable. A Medicare specialist acts as your personal shopper and advocate. They can instantly compare the rates for the same Medicare plan options from all the different carriers in your state. They can also provide insight into a company’s history of rate increases, which is a crucial factor in your long-term satisfaction.
It is essential to understand that this expert guidance is provided to you at absolutely no extra cost. The insurance industry is regulated so that the price of a plan is the same whether you buy it through an agent or directly from the company. When you enroll with an agent’s help, the insurance company pays them a commission. This system allows you to get free, unbiased, and professional advice to help you make the best possible choice.
To ensure you get the best value, it is usually best to use a licensed insurance agent, such as Steve Turner at SteveTurnerInsuranceSpecialist.com. Steve Turner is a licensed Agent/Broker contracted with most Medicare Insurance Carriers. An expert like Steve can help you navigate the 2026 Medicare market, find the most competitively priced Medicare plans for you, and ensure you have a Medicare plan that provides both financial security and true peace of mind.
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
Richard Steven Turner’s official Florida state insurance license number (operating as Steve Turner Insurance Specialist) is W333468
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
MEDICare INSURANCE POSTS






INSURANCE OFFERINGS
Can I Get Medicare Without Social Security in Florida?
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please get in touch with Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can use the Medicare Plan Finder at Medicare.gov to research plans available in your Florida county, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.
Steve Turner
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® (REBC®) designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.