
Group Health Insurance Key Parts
Group Health Insurance Key Parts
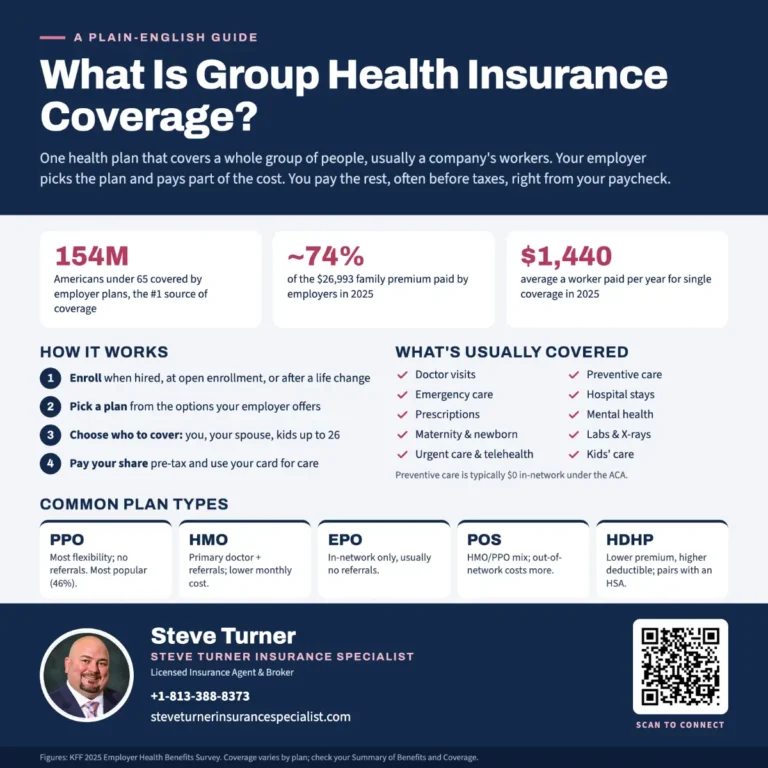
As I meet with business owners here in Citrus Park, I often find they view their group health insurance plan through one of two lenses: as a major expense on their balance sheet or as a powerful tool for attracting and retaining top talent. Both perspectives are correct, but they only tell part of the story. I encourage my clients to see their health plan for what it is: a complex, vital contract that underpins their employees’ financial and physical well-being. [Group Health Insurance Key Parts]
For three decades, I have guided companies and their employees through the intricate details of these policies. I have seen how a well-structured plan can provide immense peace of mind and how a poorly understood one can lead to confusion and devastating out-of-pocket costs. A group health insurance policy is a blueprint for partnership, detailing exactly how the insurance company, the employer, the employee, and the medical providers will work together. [Group Health Insurance Key Parts]
Today, my goal is to hand you the key to understanding that blueprint. We will walk through the 20 most essential parts of a modern group health plan. I will also highlight the five critical components that employees and even some employers frequently overlook, leading to the most common and costly surprises. [Group Health Insurance Key Parts]
Understanding the Architecture: Key Financial Terms
Before we examine the specific benefits, we must first understand the financial architecture of any group health plan. These five terms define how you share costs with your insurance carrier. [Group Health Insurance Key Parts]
- Premium: The employer and the employee (usually through payroll deduction) pay a fixed monthly amount to keep the plan active.
- Deductible: The amount you must pay out of pocket each year before your insurance plan starts paying for most services. [Group Health Insurance Key Parts]
- Copayment (Copay): You pay a flat fee, such as $40, for certain services like a doctor’s visit or a prescription drug, even if you have not yet met your annual deductible. [Group Health Insurance Key Parts]
- Coinsurance: After you meet your deductible, you share the cost of your medical care with the insurance company. Coinsurance is the percentage of the bill you pay. For an 80/20 plan, the insurer pays 80%, and you pay 20%. [Group Health Insurance Key Parts]
- Out-of-Pocket Maximum: This is the most important number for your financial safety. It’s the absolute maximum amount you will have to pay for covered, in-network medical care in a year. Once you reach this limit, the insurance company pays 100% of all covered costs for the rest of the plan year. [Group Health Insurance Key Parts]
The Top 20 Essential Parts a Group Health Insurance Policy Must Contain
A modern, compliant group health plan must provide a comprehensive suite of benefits. I have organized these 20 essential parts into functional categories to make them easier to understand. [Group Health Insurance Key Parts]
Foundational & Everyday Care
- 1. A Strong Provider Network: A health plan’s value is directly tied to the doctors and hospitals you can access. A quality plan offers a broad network of primary care physicians, specialists, hospitals, and clinics in your geographic area. Check the provider directory to ensure your preferred doctors and local hospitals are “in-network.” [Group Health Insurance Key Parts]
- 2. Comprehensive Preventive Care at No Cost: The Affordable Care Act (ACA) mandates that all compliant plans cover a wide range of preventive services at 100%, with no cost to you, as long as you use an in-network provider. This essential benefit includes annual physicals, well-woman exams, immunizations, and critical screenings for cancer, high blood pressure, and cholesterol. [Group Health Insurance Key Parts]
- 3. Low Copays for Primary Care Visits: Your plan should encourage you to build a relationship with a primary care physician (PCP). A good plan features affordable, fixed copayments for PCP visits, making it easy to seek care for routine illnesses without financial hesitation. [Group Health Insurance Key Parts]
- 4. Access to Specialists: You need the ability to see specialists like cardiologists, dermatologists, or orthopedists when necessary. Your plan must provide access to a deep roster of specialists within its network. Seeing a specialist typically costs more than a PCP visit. [Group Health Insurance Key Parts]
- 5. Prescription Drug Coverage with a Tiered Formulary: The plan must cover prescription drugs. Insurers manage this through a formulary, or a list of covered drugs, organized into tiers. A good formulary includes a wide range of generic (Tier 1), preferred brand-name (Tier 2), and non-preferred brand-name (Tier 3) drugs at predictable costs. [Group Health Insurance Key Parts]
Emergency & Major Medical Care
- 6. Emergency Room and Ambulance Coverage: Your plan must cover emergency services. This includes ER treatment and both ground and air ambulance transportation. The law protects you by requiring your plan to cover out-of-network emergency services at the in-network cost-sharing level.
- 7. Hospitalization Coverage: This is the core of “major medical” protection. The plan must cover inpatient hospital stays, including semi-private rooms, nursing care, medications, and surgeries performed during your admission. [Group Health Insurance Key Parts]
- 8. Outpatient Surgery Coverage: Many modern surgical procedures happen in an outpatient setting, meaning you go home the same day. Your policy must cover surgeries performed at an ambulatory surgical center, not just in a hospital. [Group Health Insurance Key Parts]
- 9. Mental Health Parity: The law requires your plan to cover mental and behavioral health services with the same level of benefits as it does for physical health. This essential part includes coverage for psychotherapy, counseling, and inpatient treatment for mental health and substance use disorders. [Group Health Insurance Key Parts]
- 10. Maternity and Newborn Care: Your plan must provide comprehensive coverage for pregnancy and childbirth. This includes all prenatal appointments, labor and delivery services, and inpatient care for both mother and newborn. [Group Health Insurance Key Parts]
Therapeutic & Long-Term Care
- 11. Rehabilitative Services: After an injury or major illness, you need support to recover. Your plan must cover rehabilitative therapies, such as physical therapy to regain strength after a knee replacement, occupational therapy to relearn daily tasks after a stroke, and speech therapy. [Group Health Insurance Key Parts]
- 12. Habilitative Services: The plan must also cover services that help a person learn skills they never had, which is particularly important for children with developmental conditions. [Group Health Insurance Key Parts]
- 13. Durable Medical Equipment (DME): Your policy should cover necessary medical equipment for use at home. This includes items like wheelchairs, walkers, oxygen tanks, and hospital beds. [Group Health Insurance Key Parts]
- 14. Laboratory and Imaging Services: The plan must cover the diagnostic tests your doctor orders to make a diagnosis. This includes routine blood work, urinalysis, X-rays, MRIs, and CT scans. [Group Health Insurance Key Parts]
- 15. Chronic Disease Management: For individuals with conditions like diabetes, asthma, or heart disease, the plan should offer programs and benefits that help you manage your condition and stay healthy. [Group Health Insurance Key Parts]
Essential Modern Features
- 16. A Clear and Usable Member Portal: In today’s digital world, a quality insurance plan provides an easy-to-use website or mobile app. This portal should let you find in-network doctors, check claim status, view your deductible progress, and access your insurance ID card. [Group Health Insurance Key Parts]
- 17. Telehealth or Virtual Visit Options: A modern plan must offer a telehealth benefit. This lets you have a virtual visit with a doctor by phone or computer for minor illnesses or mental health counseling, often with a lower copay than an in-person visit. [Group Health Insurance Key Parts]
- 18. A 24/7 Nurse Line: Many plans provide access to a 24-hour phone line staffed by registered nurses. This valuable service lets you get immediate advice for non-emergency health questions, helping you decide whether to go to urgent care, the ER, or wait to see your doctor. [Group Health Insurance Key Parts]
- 19. A Fair and Transparent Appeals Process: Sometimes, the insurance company may deny a claim. Your policy must have a clear, well-defined process that lets you and your doctor appeal the decision and provide more information so the case can be reconsidered. [Group Health Insurance Key Parts]
- 20. A Summary of Benefits and Coverage (SBC): The law requires your plan to provide a standardized, easy-to-read document called the SBC. This document outlines the plan’s key features, costs, and limitations in a consistent format, allowing you to compare different health plans easily. [Group Health Insurance Key Parts]
The Top 5 Overlooked Parts of a Group Health Insurance Policy
Over my many years as a broker, I have seen clients make the same mistakes time and time again. They focus on the monthly premium and the deductible but miss the critical details that can cost them thousands. I always review these five areas with every client.
- 1. The Out-of-Network Rules and Costs: Many people assume their plan will work the same way no matter which doctor they see. This is a massive and costly mistake. If you go to an “out-of-network” doctor, your plan may provide zero coverage, or it may have a completely separate—and much higher—deductible and out-of-pocket maximum for that care. I always advise my clients to consider out-of-network care a financial emergency only. Always confirm a provider is in-network before you make an appointment. [Group Health Insurance Key Parts]
- 2. The Prescription Drug Formulary Details: People often check to see that their plan has “drug coverage,” but they fail to investigate the specifics. You must check the plan’s formulary to see which tier your specific medications fall into. A maintenance medication for a chronic condition might be a low-cost generic on one plan but an expensive “non-preferred brand” on another, costing you hundreds of dollars more per month. You should also check for any “step therapy” or “prior authorization” requirements for your medications. [Group Health Insurance Key Parts]
- 3. The Definition of a “Medical Emergency”: While the law protects you from out-of-network penalties for emergency care, you need to understand how the insurance company defines an emergency. They use a “prudent layperson” standard, meaning they will cover a condition that a person with average medical knowledge would reasonably believe is an emergency. If you go to the ER for a minor condition that could have been treated at an urgent care center, the insurer could deny the claim, leaving you with the entire bill. [Group Health Insurance Key Parts]
- 4. Pediatric Dental and Vision Coverage: This is a huge point of confusion. The ACA requires compliant plans to cover dental and vision care for children up to age 19. Many parents assume this benefit is automatically embedded in their medical plan. Often, the carrier meets this requirement by automatically enrolling children in a separate pediatric dental and vision plan, which may have its own premium and provider network. Parents often forget to check and miss out on this valuable benefit for their children. [Group Health Insurance Key Parts]
- 5. The Plan’s Specific Exclusions: Every insurance policy has a section that lists what it will not cover. People rarely read this section. It is where you will find information on common exclusions like cosmetic surgery, most infertility treatments, and long-term care. Taking ten minutes to review the “Exclusions” section of your benefits summary can save you from a massive, unexpected bill for a service you mistakenly assumed your plan would cover.
Here at my office, I see the power of a good health plan every day. It empowers employees to seek care with confidence and gives employers a competitive edge. By understanding these essential parts, you can turn your health insurance from a confusing expense into a clear, powerful tool for financial security. Use this guide as a checklist to engage with your benefits and make the most of your coverage.
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
Richard Steven Turner’s official Florida state insurance license number (operating as Steve Turner Insurance Specialist) is W333468
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
Group HEALTH INSURANCE POSTS

INSURANCE OFFERINGS
Group Health Insurance Key Parts
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please get in touch with Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can use the Medicare Plan Finder at Medicare.gov to research plans available in your Florida county, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.
Steve Turner
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® (REBC®) designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.