
What Is Group Health Insurance Coverage?

What Is Group Health Insurance Coverage? Basic Definition and How Group Plans Work
The first time I got a job with benefits, the HR person handed me a thick packet. It was full of words like “premium,” “deductible,” and “PPO.” I nodded as if I understood. I did not.
If you feel the same way, you are not alone. In this guide, I will explain group health insurance coverage in plain words. I’ll explain what it is, how it works, what it covers, and what it costs. I will also answer the questions people ask me most.
Here is the short answer: group health insurance coverage is one health plan that covers a whole group of people, usually the workers at a company. The employer picks the plan and pays part of the cost. You pay the rest, often through your paycheck.
What Is Group Health Insurance?
Group health insurance is a health plan that one organization buys for a group of people. Most of the time, that organization is an employer, and the group is its workers. Some unions and professional groups offer it too.
I like to think of it like buying snacks in bulk. When one person buys a single bag of chips, each chip costs more. When a school buys chips for every class, the price per bag goes down. Group health insurance works similarly. The insurance company spreads the risk across many people, so the per-person cost is often lower.
This kind of coverage is a really big deal in the United States. According to KFF, employer plans cover about 154 million people under age 65. That makes it the most common way Americans get health insurance.
You may also hear it called:
- Employer-sponsored health insurance
- Employer health plan
- Group medical coverage
- Job-based health insurance
They all mean pretty much the same thing.
How Does Group Health Insurance Work?
Three players are part of every group health plan. Here is who they are and what each one does:
- The employer. Your company shops for a plan, signs the contract, and pays a big part of the monthly cost.
- The insurance company. It pays doctors, hospitals, and drug stores when you get care. (Some large companies skip this step and pay claims with their own money. This is called a “self-funded” plan.)
- You, the worker. You sign up, pay your share, and use the plan when you need care.
Here is what usually happens, step by step:
- You get hired, or your company’s yearly “open enrollment” time starts.
- You look at the plans your job offers and pick one.
- You choose who to cover: just you, you and your spouse, you and your kids, or your whole family.
- Your share of the cost comes out of each paycheck. Most of the time, it is taken out before taxes, which saves you money.
- You get an insurance card. You show it when you visit the doctor or pick up medicine.
One thing I wish someone had told me sooner: you usually can only sign up or switch plans at certain times. Those times are when you are first hired, during open enrollment each year, or after a big life change. Big life changes include getting married, having a baby, or losing other coverage.
Who Can Get Group Health Insurance?
Not every worker gets offered a plan. Whether you qualify depends on your job and on the company’s rules.
Most plans are open to:
- Full-time workers. Under the Affordable Care Act (ACA), this usually means people who work 30+ hours a week.
- Spouses. Many plans let you add your spouse.
- Children up to age 26. Your kids can stay on your plan until they turn 26, even if they are married or out of school.
- Some part-time workers. This depends on the company. Some offer it, and many do not.
Companies can also make you wait before you sign up. Under the ACA, that waiting period can’t be longer than 90 days.
Do employers have to offer health insurance?
It depends on the company’s size. Companies with 50 or more full-time workers (or the same in part-time hours added up) are called “applicable large employers.” The ACA says they must offer full-time workers coverage that is “affordable” and meets a basic quality bar. If they don’t, they can owe the IRS a penalty.
For plans that start in 2026, coverage counts as affordable if the cheapest worker-only plan costs no more than 9.96% of your household income. That number comes from the IRS, and it is the highest it has ever been.
Smaller companies with fewer than 50 workers don’t have to offer a plan. Many still do, because good benefits help them hire and keep great people.
Small group vs. large group
You may hear these two terms:
- Small group plans are for small businesses. In most states, that means 1 to 50 workers. A few states use 1 to 100.
- Large group plans are for bigger companies. These plans have more freedom in how they are built and priced.
Many insurers also want a certain share of eligible workers to sign up before they will sell a small group plan. This rule helps keep the group large enough to spread out the risk.
What Does Group Health Insurance Cover?
Every plan is a little different, so I always tell people to read their plan’s “Summary of Benefits and Coverage.” It is a short paper that lists what is covered and what you pay. Still, most group plans cover the same basic things.
Here are 10 things most group health plans cover:
- Doctor visits. Checkups with your main doctor and visits to specialists.
- Preventive care. Yearly checkups, many shots, and common health screenings. Under the ACA, most plans cover these at no cost to you when you see an in-network doctor.
- Emergency care. Emergency care.
- Hospital stays. Surgery, overnight stays, and care while you are in the hospital.
- Prescription drugs. Medicines your doctor orders. KFF reports that nearly all covered workers have drug coverage.
- Mental health care. Therapy, counseling, and treatment for substance use.
- Pregnancy and newborn care. Prenatal visits, delivery, and newborn care.
- Lab tests and X-rays. Blood work, scans, and other tests.
- Urgent care and telehealth. Quick care for urgent needs, plus video visits from home.
- Kids’ care. Checkups, shots, and often vision and dental care for children.
What is usually not covered?
Most plans leave out things like cosmetic surgery, and some don’t cover certain weight-loss drugs. Adult dental and vision care are often sold as separate plans. If something matters to you, check before you sign up.
Types of Group Health Insurance Plans
When I first looked at my plan choices, the letters made my head spin. Here is what each one means in plain words.
- PPO (Preferred Provider Organization). You can see almost any doctor, inside or outside the network, and you don’t need a referral to see a specialist. Going in-network costs less. PPOs often have higher monthly costs. This is the most popular type: 46% of covered workers have one, per KFF.
- HMO (Health Maintenance Organization). You choose a primary doctor who coordinates your care. You usually need a referral to see a specialist. The plan won’t pay for out-of-network care unless it is an emergency. HMOs often cost less each month.
- EPO (Exclusive Provider Organization). Like an HMO, it only pays for in-network care. But you usually don’t need a referral to see a specialist.
- POS (Point of Service). A mix of HMO and PPO. You have a main doctor and need referrals, but you can go out of network if you pay more.
- HDHP (High-Deductible Health Plan). You pay less each month, but you pay more before the plan starts helping. These plans often come with a Health Savings Account (HSA). An HSA lets you save money tax-free for medical bills. About one in three covered workers is in this kind of plan.
What about an ICHRA?
Some employers don’t buy one group plan at all. Instead, they give workers tax-free money to buy their own plan. This is called an Individual Coverage Health Reimbursement Arrangement (ICHRA). It is still fairly rare, but more small businesses are thinking about it.
My tip: If you are healthy and rarely see a doctor, an HDHP with an HSA can save you money. If you have ongoing health needs or take daily medicine, a PPO or HMO with a lower deductible may cost you less over the year.
How Much Does Group Health Insurance Cost?
The full price of group health insurance is high, but your employer usually pays most of it. Here are the latest national averages from KFF’s 2025 Employer Health Benefits Survey:
| Cost (2025 average, per year) | Just you (single) | Family |
|---|---|---|
| Total premium | $9,325 | $26,993 |
| What workers paid | $1,440 | $6,850 |
| Worker’s share of the premium | 16% | 26% |
So on a family plan, the employer paid about $20,000 a year, and the worker paid the rest. KFF also expects costs to climb faster in 2026, so your numbers may be a bit higher.
The 5 costs I always check
The monthly premium is only part of the story. Here are the five costs I look at before I pick a plan:
- Premium. The amount taken from your paycheck to keep your coverage, whether you see a doctor or not.
- Deductible. What you pay for care each year before the plan starts paying its share. The average single deductible was $1,886 in 2025. At small companies, it was higher, at $2,631.
- Copay. A set fee for a visit. The average was $27 to see your main doctor and $45 to see a specialist.
- Coinsurance. A percent of the bill you pay after you meet your deductible. Around 20% is common.
- Out-of-pocket maximum. The most you will pay in a year for in-network care. After you hit it, the plan pays 100%. This is your safety net.
My tip: Don’t just pick the cheapest premium. Add up the premium plus what you think you’ll spend on care. The plan with the lowest total is often the real winner.
Pros and Cons of Group Health Insurance
I think group health insurance is a great deal for most people. But it is not perfect. Here is my honest list.
The pros
- Your employer pays most of the bill. That is money you would otherwise pay on your own.
- It saves on taxes. Your share usually comes out before taxes, so you take home more than you would if you paid with after-tax money.
- Everyone can join. You can’t be turned down or charged more because of a health problem you already have.
- Lower prices per person. A big group helps keep costs down.
- Family coverage. You can add your spouse and kids up to age 26.
- Less work for you. Your HR team does the shopping and handles a lot of the paperwork.
The cons
- Fewer choices. You can only pick from the plans your employer offers.
- It’s tied to your job. If you quit or get let go, your coverage usually ends.
- Family coverage can be pricey. At small companies, workers paid an average of $8,889 a year for family coverage in 2025, according to KFF.
- Plans can change each year. Your employer may switch insurers, raise costs, or change the doctor network.
- Deductibles keep rising. More than a third of covered workers now have a single deductible of $2,000 or more.
Group vs. Individual Health Insurance
People often ask me which is better: a group plan through work or an individual plan they buy on their own. Here is how they compare.
| Group health insurance | Individual health insurance | |
|---|---|---|
| Who buys it | Your employer | You |
| Who pays | Employer pays most; you pay a share | You pay it all, minus any tax credits |
| How you pay | Taken from your paycheck, often before taxes | You pay the insurer each month |
| Plan choices | Only what your job offers | Many plans on HealthCare.gov or your state’s marketplace |
| When you can sign up | When hired, open enrollment, or a life change | Yearly open enrollment or a life change |
| What happens if you leave your job | Coverage usually ends | Coverage stays with you |
For most people, the group plan wins because the employer pays so much of the cost. An individual plan can make sense if you are self-employed, between jobs, or your job doesn’t offer coverage. If your work plan costs more than 9.96% of your household income in 2026, you might also qualify for help paying for a marketplace plan.
What Happens to Your Coverage When You Leave a Job?
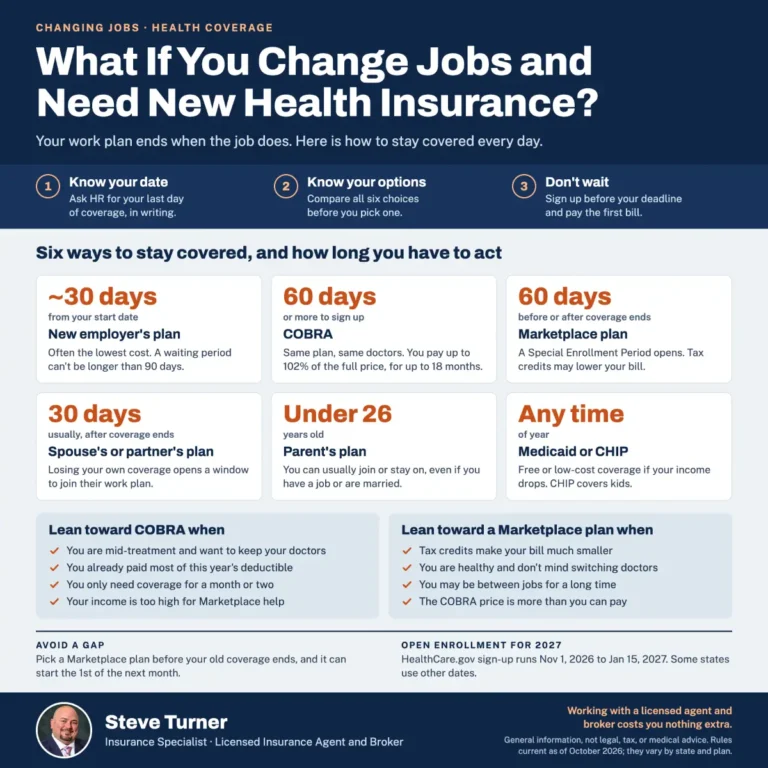
This part scares a lot of people, so I want to make it clear. When you leave a job, your group coverage usually ends. Some plans end it on your last day. Others keep you covered until the end of that month. Ask HR to confirm your exact end date.
The good news is you have options. Here are the three I’d look at first:
- COBRA. This federal law lets you keep your same plan for a while, usually up to 18 months. It applies to companies with 20 or more workers, and many states have similar rules for smaller companies. The catch? You pay the full price yourself, plus up to 2% more. Since your employer no longer helps, COBRA can be very expensive. You generally have 60 days to decide.
- A marketplace plan. Losing job coverage lets you buy a plan on HealthCare.gov or your state’s marketplace, even outside open enrollment. You usually have 60 days after you lose coverage to sign up. Depending on your income, you may get help paying.
- A spouse’s or parent’s plan. Losing your coverage lets you join a spouse’s work plan outside their open enrollment. If you are under 26, you can join a parent’s plan. Act fast, because the window to sign up is often just 30 days.
If your income is low, you might also qualify for Medicaid, which you can apply for year-round.
My tip: Don’t let your coverage lapse. Even one week without insurance can be costly if you get sick or hurt.
Frequently Asked Questions About Group Health Insurance
Is group health insurance the same as employer-sponsored insurance?
Mostly, yes. Employer-sponsored insurance is the most common kind of group health insurance. Some unions, trade groups, and associations also offer group plans.
Can I turn down my employer’s health insurance?
Yes. You can say no, for example, if you are already on a spouse’s plan. Just know that if you turn it down, you usually can’t join until the next open enrollment unless you have a big life change.
Can a group plan deny me because of a health problem?
No. Under the ACA, a group plan can’t turn you down or charge you more because of a health condition you already have.
Can I add my partner or kids?
You can almost always add your kids up to age 26. Most plans let you add a spouse. Some also cover domestic partners, so check your plan’s rules.
How many people do you need for a group plan?
It depends on the insurer and your state. In some places, a business with just one worker who isn’t the owner or the owner’s spouse can buy a small group plan. Others need two or more.
Is my share of the premium taken out before taxes?
Usually, yes. Most employers set it up so your share comes out before income taxes. That lowers your taxable pay and puts more money in your pocket.
What is open enrollment?
It is a set time each year, often in the fall, when you can join, drop, or change your plan. Many companies hold it around this time of year for plans that start January 1.
Does group health insurance cover dental and vision?
Sometimes. Many employers offer dental and vision as separate plans that you sign up for on their own. Kids’ dental and vision care is more often included.
The Bottom Line
Group health insurance coverage is a health plan that your employer buys for you and your coworkers. Your employer picks the plan and pays most of the cost. You pay a smaller share from your paycheck, often before taxes. In return, you get help paying for doctor visits, hospital stays, medicine, and much more.
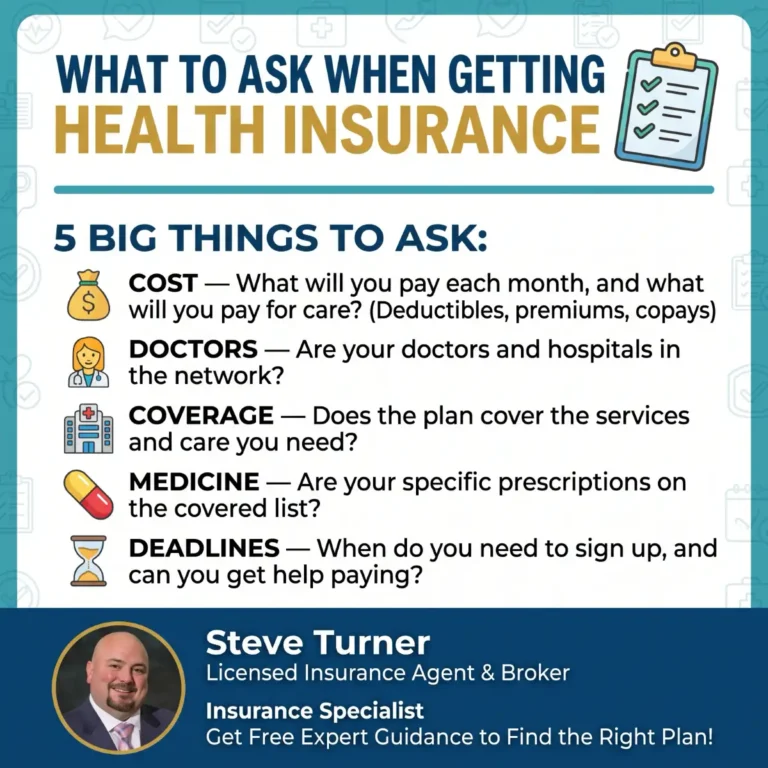
Before you pick a plan, here is my quick checklist:
- Compare the premium, deductible, copays, and out-of-pocket maximum.
- Make sure your doctors are in the plan’s network.
- Check that your medicines are covered.
- Decide who you want to cover: just you, or your family too.
- Mark your open enrollment dates on your calendar.
- Know your options, like COBRA or the marketplace, in case you ever leave your job.
When I finally took the time to learn these basics, that thick benefits packet stopped scaring me. I hope this guide does the same for you. If you still have questions, your HR team is a great place to start.
Why choose Steve Turner Insurance Specialist?
Because I’m an “Insurance Specialist.” An “insurance specialist” is a broad term that includes insurance agents and insurance brokers, but the key difference is who the agent represents versus who the broker represents.
An “insurance agent” works directly for an insurance company and sells its specific policies to clients.
An “insurance broker” acts as an independent intermediary, comparing policies from multiple companies to find the best fit for their client’s needs, essentially representing the client rather than the insurance company.
I am both a licensed Insurance Agent and a licensed Insurance Broker.
My number one goal in life is to help people and ensure, without a shadow of a doubt, that you and your family are secure and protected. I will always be by your side, helping you mitigate risk by providing the industry’s best and most affordable insurance solutions.
I will find insurance plans for the entire family to help cover whatever life throws at you. I can help you save on severe medical emergencies, find a health insurance plan with low- or no-cost doctor visits and affordable prescription medications, and protect your family in the event of an unexpected accident or illness.
Best of all, it doesn’t cost you anything extra to use an experienced Insurance Agent and Broker like me to help you find the Insurance Plans that fit your individual, family, or business needs.
The companies that sell the insurance plans “you choose“ pay me – you don’t pay me. Calling any big insurance company directly won’t get you a lower price, as they will forward your call to the next available insurance agent on their list. You won’t have had any opportunity to learn about the insurance agent you’re speaking with in advance, understand their qualifications or experience level, or make an informed choice about who you want to work with.
Tap the Contact Me text or icon and get in touch by phone or email, or schedule a “No Obligation” chat through my calendar. I look forward to speaking with you!
OUR CLIENT REVIEWS


CONTACT STEVE TURNER INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
Richard Steven Turner’s official Florida state insurance license number (operating as Steve Turner Insurance Specialist) is W333468
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. – 8:00 p.m.
Tuesday: 7:00 a.m. – 8:00 p.m.
Wednesday: 7:00 a.m. – 8:00 p.m.
Thursday: 7:00 a.m. – 8:00 p.m.
Friday: 7:00 a.m. – 8:00 p.m.
Saturday: 7:00 a.m. – 8:00 p.m.
Sunday: 7:00 a.m. – 8:00 p.m.
Group HEALTH INSURANCE POSTS

INSURANCE OFFERINGS
What Is Group Health Insurance Coverage?
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please contact Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can research the plans available in your Florida county using the Medicare Plan Finder at Medicare.gov, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.