
How to Check if Your Medication is Covered – Prescription Drugs Insurance

How to Check if Your Medication is Covered – Prescription Drugs Insurance – Customer Wants to Verify Coverage Before Filling Prescription
I still remember the day I stood at the pharmacy counter and heard the words no one wants to hear: “Your insurance won’t cover this.” The pharmacist told me the price. My jaw dropped. It was a medicine my doctor had just prescribed, and I had no idea it wasn’t covered.
I walked away that day without my medicine. I felt confused, a little embarrassed, and honestly a bit angry. Why didn’t anyone tell me? How was I supposed to know?
Here’s the good news. After that day, I learned how prescription drug insurance really works. I learned how to check if a medicine is covered before I get to the pharmacy. And I learned what to do when the answer is “no.”
In this guide, I’ll walk you through everything I wish I had known. I’ll keep it simple. You don’t need to be an insurance expert. You need a few minutes, your insurance card, and the name of your medicine.
By the end, you’ll know:
- What a drug list (called a formulary) is and why it matters
- How to check if your medication is covered, step by step
- What special rules might apply to your medicine
- What to do if your drug isn’t covered
- Smart ways to pay less for your prescriptions
Let’s get started.
What Is a Formulary? (The Drug List That Decides Everything)
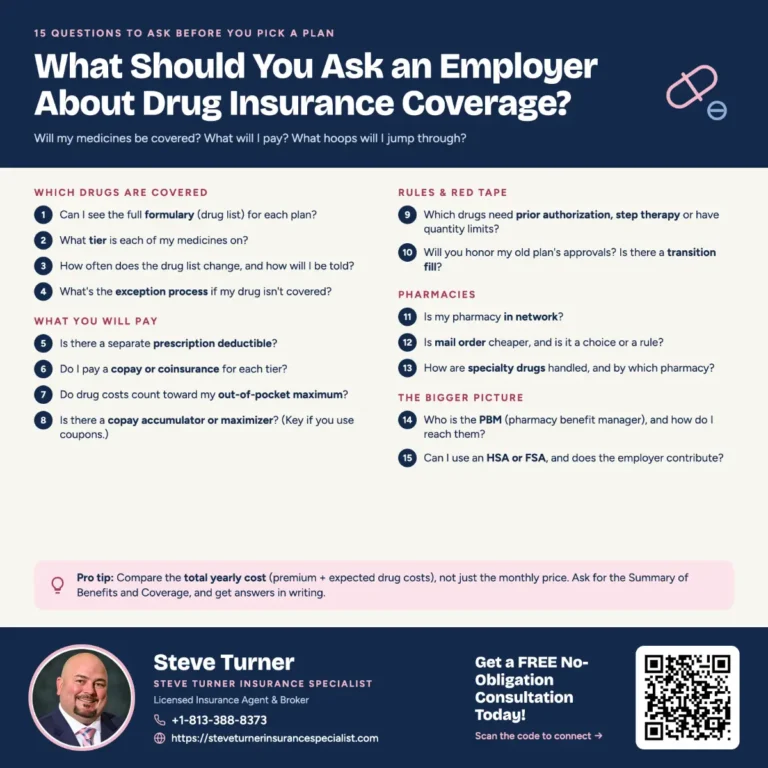
The first thing I learned is that every insurance plan has a list of the medicines it covers. This list is called a formulary. Some people call it a “drug list” or a “preferred drug list.” They all mean the same thing.
If your medicine is on the list, your plan will help pay for it. If it’s not on the list, you may have to pay the full price yourself.
Here’s something that surprised me: two plans from the same insurance company can have different drug lists. So even if your friend has the same insurer, their coverage may not match yours. Always check your plan.
Why Do Formularies Change?
Drug lists are not set in stone. Plans can update them, often once a year and sometimes during the year. A new drug might get added. An old one might get dropped. A drug might move to a more expensive group. That’s why I check my coverage every year, even for medicines I’ve taken for a long time.
What Are Drug Tiers?
Most drug lists sort medicines into groups called tiers. The tier tells you how much you’ll pay. A lower tier usually means a lower cost. Here is how tiers often work (your plan may be a little different):
| Tier | What It Usually Includes | What You Usually Pay |
|---|---|---|
| Tier 1 | Preferred generic drugs | Lowest cost |
| Tier 2 | Other generic drugs | Low cost |
| Tier 3 | Preferred brand-name drugs | Medium cost |
| Tier 4 | Non-preferred brand-name drugs | Higher cost |
| Tier 5 | Specialty drugs (often for serious or rare conditions) | Highest cost |
So when I look up a drug, I don’t just ask, “Is it covered?” I also ask, “What tier is it on?” A drug can be covered and still cost a lot if it’s on a high tier.
Copay vs. Coinsurance
You’ll see two words a lot when you look at tiers:
- Copay: A set dollar amount you pay, like $10 per fill.
- Coinsurance: A percentage of the drug’s price you pay, like 25%.
Copays are easier to plan for. Coinsurance can surprise you because if the drug is expensive, 25% of a big number is still a big number.
You may also have a deductible. That’s the amount you pay each year before your plan starts sharing the cost. Some plans skip the deductible for cheaper tiers, so it’s worth checking.
How to Check if Your Medication Is Covered: 7 Easy Steps
This is the part I use the most. These are the exact steps I follow every time I get a new prescription or change plans.
- Gather what you need. Before you start, grab three things:
- Your insurance card (front and back)
- The exact name of your medicine, including the strength (like “20 mg”)
- Your plan name, which is usually printed on the card
- Find your plan’s drug list online. Go to your insurance company’s website. Look for words like “Drug List,” “Formulary,” “Pharmacy,” or “Prescription Coverage.” Many plans post the full list as a searchable PDF. Make sure the list is for the current year and for your exact plan.
- Use the online drug price tool. Most insurers have a tool where you type in a drug name and see if it’s covered. When I log in to my member account, this tool often shows my actual cost, not just a guess. It may also show cheaper options.
- Search for both the brand name and the generic name. This is a step I used to skip. A drug might be listed under its generic name only. For example, if you search for a brand name and get nothing, try the generic version. Your pharmacist or doctor can tell you the generic name.
- Call the number on your insurance card. If the website is confusing, call. The back of the card usually has a member services or pharmacy phone number. I always ask these questions:
- Is this drug covered on my plan?
- What tier is it on?
- How much will I pay at a regular pharmacy? By mail order?
- Are there any special rules, like prior authorization?
- Ask your pharmacist. Pharmacists are one of my favorite resources. They can run your prescription through your insurance and tell you right away if it’s covered and what you’ll pay. They can also tell you if there’s a cheaper generic.
- Check with your doctor’s office. Many doctors’ offices can see your plan’s coverage in their computer system when they write a prescription. Ask them to check before they send it. If the drug isn’t covered, they may be able to choose a similar one that is.
My tip: Write down what you find. I keep a simple note on my phone with the drug name, the tier, the cost, the date I checked, and the name of anyone I talked to on the phone. It has saved me more than once when there was a mix-up.
“Covered” Doesn’t Always Mean Easy: Special Rules to Watch For
Here’s a lesson I learned the hard way. A drug can be on your plan’s list and still not be simple to get. Plans often add rules to certain medicines. On most drug lists, you’ll see these rules marked with short codes like PA, ST, or QL. Here’s what they mean.
Prior Authorization (PA)
Prior authorization means your plan wants to approve the drug before it pays. Your doctor has to send the plan information explaining why you need it. This can take a few days, so I always try to start early. If I know a drug needs prior authorization, I ask my doctor’s office to send the request the same day they write the prescription.
Step Therapy (ST)
Step therapy means the plan wants you to try a cheaper drug first. If that drug doesn’t work for you, or causes problems, then the plan will cover the more expensive one. If you’ve already tried the cheaper drug in the past, tell your doctor. That history can help you skip the step.
Quantity Limits (QL)
Quantity limits cap how much of a drug you can get at one time. For example, a plan might only cover 30 pills a month. If your doctor wants you to take more, they can request an exception from the plan.
Pharmacy Network Rules
This one tripped me up once. Many plans only cover drugs at certain pharmacies, called in-network pharmacies. Some plans also have preferred pharmacies where you pay even less. Some specialty drugs must come from a specific specialty pharmacy. Before you fill a prescription, make sure your pharmacy works with your plan.
What to Do If Your Medication Isn’t Covered
When I first heard “not covered,” I thought that was the end of the story. It isn’t. You have more options than you might think. Here’s what I do, in order.
- Ask about a covered alternative. Call your doctor and ask if there’s a similar drug on your plan’s list. Often there is, and it works just as well. This is usually the fastest fix.
- Ask about a generic. If your drug is a brand name, there may be a generic version that costs far less and is covered.
- Request a formulary exception. This is a formal request asking your plan to cover a drug that isn’t on its list. Your doctor usually needs to write a statement explaining why you need this specific drug. For example, other drugs may have caused side effects or didn’t work.
- Ask for a tiering exception. If the drug is covered but on a high, costly tier, you can ask the plan to charge you the lower-tier price instead.
- Ask about a temporary supply. If you just joined a new plan and your drug isn’t covered, some plans will give you a short “transition” supply while you and your doctor sort things out. Medicare drug plans must offer this to many new members.
- File an appeal if you’re denied. If your plan says no, you have the right to appeal. That means asking them to look at the decision again. Your denial letter should explain how to appeal and the deadline. Don’t miss that deadline.
- Ask for an outside review. If your appeal is denied, you can often ask for an independent review by someone outside the insurance company. In many cases, that decision is final, and the plan must follow it.
Tips That Helped My Appeal
The one time I had to appeal, these things made a big difference:
- Get your doctor involved early. A strong letter from your doctor is the most important part.
- Ask about an expedited (fast) review. If waiting could harm your health, you can ask for a faster decision.
- Keep copies of everything. Save letters, emails, and notes from phone calls.
- Be polite but persistent. Follow up if you don’t hear back by the date they promised.
Checking Coverage by Type of Insurance
The basic steps work for almost any plan. But each type of insurance has a few extras worth knowing.
Medicare (Part D and Medicare Advantage)
If you have Medicare, your drug coverage usually comes from a Part D plan or a Medicare Advantage plan that includes drug coverage. Here’s how I’d check:
- Use the Medicare Plan Finder. On Medicare.gov, the Plan Finder tool lets you enter your medicines and pharmacy. It shows which plans cover your drugs and estimates your yearly costs.
- Read your Annual Notice of Change. Every fall, your plan mails this letter. It lists changes for next year, including drugs that are being dropped or moved to a new tier.
- Know the enrollment dates. Medicare Open Enrollment runs from October 15 to December 7 every year. That’s your main chance to switch plans if your drugs won’t be covered well next year.
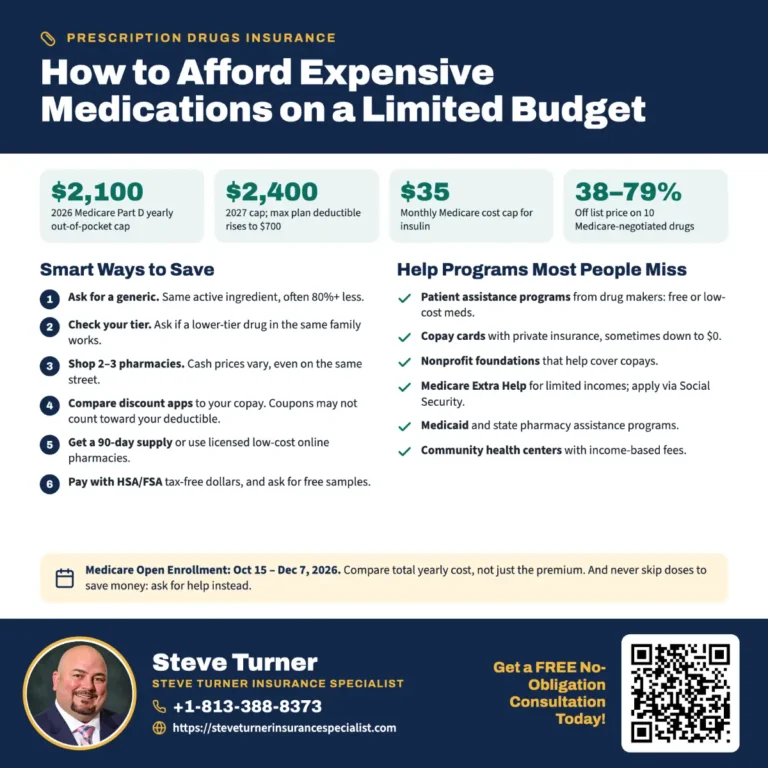
- Know your protections. Medicare drug plans now have a yearly cap on out-of-pocket drug costs, and covered insulin costs no more than $35 for a month’s supply. Check Medicare.gov for this year’s exact cap.
If you need help, your State Health Insurance Assistance Program (SHIP) offers free, unbiased Medicare counseling. You can also call 1-800-MEDICARE.
Medicaid
Each state runs Medicaid drug coverage. Most states have a Preferred Drug List (PDL). You can usually find it on your state’s Medicaid website or your Medicaid health plan’s website. Many medicines cost very little or nothing at all with Medicaid. Some still require prior authorization, so ask your doctor to check.
Job-Based Insurance
If you get insurance through work, a separate company called a pharmacy benefit manager (PBM) may manage your drug coverage. Your insurance card may list the PBM’s name and phone number. That’s often the best place to check your drug list. Your company’s HR or benefits team can also help, especially during your yearly enrollment period.
Marketplace (ACA) Plans
If you buy insurance on HealthCare.gov or your state’s marketplace, you can often check drug coverage while you shop. Look for a “drug list” link on each plan. Before I’d pick any plan, I’d make sure every medicine I take is on its list.
9 Ways I Save Money on Prescriptions
Even when a drug is covered, the cost can add up. These are the tricks that have saved me the most money over the years:
- Choose generics when you can. Generic drugs have the same active ingredients as brand-name drugs and usually cost much less.
- Try a mail-order pharmacy. Many plans offer a 90-day supply by mail for less than three 30-day fills at a store.
- Ask for a 90-day supply. Even at a local pharmacy, a 90-day fill can lower your cost and mean fewer trips.
- Use preferred pharmacies. If your plan has preferred pharmacies, using one can lower your copay.
- Compare cash prices with discount cards. Sometimes a free discount card or app price is cheaper than your insurance copay. Just know that the money you pay this way may not count toward your deductible.
- Look for manufacturer savings programs. Many drug makers offer copay cards or coupons for brand-name drugs. Check the drug’s official website. (These often can’t be used with Medicare or Medicaid.)
- Apply for patient assistance programs. If money is tight, many drug companies and nonprofits help people get medicine at low or no cost.
- Ask about Extra Help. If you have Medicare and limited income, the Extra Help program can significantly lower your drug costs.
- Review your plan every year. Your needs change, and so do plans. A quick yearly check can save you hundreds of dollars.
Frequently Asked Questions About Prescription Drug Coverage
These are questions I’ve asked myself, or that friends and family have asked me.
How do I know if my medication is covered by insurance?
Check your plan’s drug list (formulary) on your insurer’s website, use their online drug cost tool, or call the number on the back of your insurance card. Your pharmacist can also check your insurance and tell you right away.
Why was my medication covered last year but not this year?
Plans can change their drug lists, usually at the start of a new year. A drug might be removed or moved to a higher tier. That’s why I check my coverage every fall before my plan renews.
What does “non-formulary” mean?
It means the drug is not on your plan’s list of covered medicines. You may have to pay full price unless your doctor gets an exception approved.
How long does prior authorization take?
It depends on your plan. Many standard requests are decided within a few days. Urgent requests are often decided faster. Ask your plan how long it usually takes and follow up if you don’t hear back.
Can my pharmacist tell me if a drug is covered?
Yes. Pharmacists can check your coverage and cost in real time. They can also suggest a cheaper generic or let you know if you need prior authorization.
Is a generic drug as good as the brand name?
Generic drugs must have the same active ingredient, strength, and dosage form as the brand-name version. For most people, they work the same way. If you have concerns, talk with your doctor or pharmacist.
What if I can’t afford my medicine even with insurance?
Talk to your doctor about cheaper options. Then look into manufacturer savings programs, patient assistance programs, discount cards, and (if you have Medicare) the Extra Help program. Please don’t just stop taking a medicine without talking to your doctor first.
Do I need to check coverage every time I refill?
Not every refill. But I do check when I start a new drug, change plans, change pharmacies, or start a new plan year.
Final Thoughts: Don’t Wait Until You’re at the Pharmacy Counter
Looking back, my bad day at the pharmacy taught me something important. Checking if your medication is covered isn’t hard. It just has to happen before you need the medicine, not after.
Here’s my quick checklist to remember:
- Find your plan’s drug list (formulary)
- Look up your medicine by brand and generic name
- Check the tier and your cost
- Look for special rules like prior authorization, step therapy, or quantity limits.
- Make sure your pharmacy is in your network
- Call your plan, pharmacist, or doctor if anything is unclear
- Review your coverage every year during open enrollment
If your drug isn’t covered, remember that “no” is often just the start of the conversation. Ask about alternatives, request an exception, and appeal if needed.
You deserve to get the medicine you need without surprises. A few minutes of checking today can save you stress and money tomorrow.
This article is for general information only and isn’t medical or legal advice. Always talk with your doctor, pharmacist, or insurance plan about your specific situation.
Why choose Steve Turner Insurance Specialist?
Because I’m an “Insurance Specialist.” An “insurance specialist” is a broad term that includes insurance agents and insurance brokers, but the key difference is who the agent represents versus who the broker represents.
An “insurance agent” works directly for an insurance company and sells its specific policies to clients.
An “insurance broker” acts as an independent intermediary, comparing policies from multiple companies to find the best fit for their client’s needs, essentially representing the client rather than the insurance company.
I am both a licensed Insurance Agent and a licensed Insurance Broker.
My number one goal in life is to help people and ensure, without a shadow of a doubt, that you and your family are secure and protected. I will always be by your side, helping you mitigate risk by providing the industry’s best and most affordable insurance solutions.
I will find insurance plans for the entire family to help cover whatever life throws at you. I can help you save on severe medical emergencies, find a health insurance plan with low- or no-cost doctor visits and affordable prescription medications, and protect your family in the event of an unexpected accident or illness.
Best of all, it doesn’t cost you anything extra to use an experienced Insurance Agent and Broker like me to help you find the Insurance Plans that fit your individual, family, or business needs.
The companies that sell the insurance plans “you choose“ pay me – you don’t pay me. Calling any big insurance company directly won’t get you a lower price, as they will forward your call to the next available insurance agent on their list. You won’t have had any opportunity to learn about the insurance agent you’re speaking with in advance, understand their qualifications or experience level, or make an informed choice about who you want to work with.
Tap the Contact Me text or icon and get in touch by phone or email, or schedule a “No Obligation” chat through my calendar. I look forward to speaking with you!
OUR CLIENT REVIEWS


CONTACT STEVE TURNER INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
Richard Steven Turner’s official Florida state insurance license number (operating as Steve Turner Insurance Specialist) is W333468
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. – 8:00 p.m.
Tuesday: 7:00 a.m. – 8:00 p.m.
Wednesday: 7:00 a.m. – 8:00 p.m.
Thursday: 7:00 a.m. – 8:00 p.m.
Friday: 7:00 a.m. – 8:00 p.m.
Saturday: 7:00 a.m. – 8:00 p.m.
Sunday: 7:00 a.m. – 8:00 p.m.
PRESCRIPTION DRUG INSURANCE POSTS
INSURANCE OFFERINGS
How to Check if Your Medication is Covered – Prescription Drugs Insurance
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please contact Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can research the plans available in your Florida county using the Medicare Plan Finder at Medicare.gov, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.