
How to Choose the Right Medicare Advantage Plan

How to Choose the Right Medicare Advantage Plan. Decision-making Framework for Selecting a Plan
Picking a Medicare Advantage plan can feel like standing in a cereal aisle with 50 boxes. They all look good. They all make big promises. And you only get to pick one for the whole year.
I know that feeling well. The first time I helped a family member choose a plan, I spread a pile of mailers across the kitchen table. Every one said it was the “best” plan. By the end of the night, my head hurt, and we still hadn’t decided.
Since then, I’ve learned a simple way to cut through the noise. In this guide, I’ll walk you through choosing the right Medicare Advantage plan, step by step. I’ll keep it plain and simple. No insurance jargon without an explanation. No sales pitch.
Here’s why the timing matters right now. The Medicare Annual Enrollment Period runs from October 15 to December 7, 2026. Any plan you pick in that window starts on January 1, 2027. If you miss it, you may be stuck with your current plan for another year, even if it no longer fits your needs.
By the end of this article, you’ll know:
- What a Medicare Advantage plan is (and isn’t)
- The exact steps I use to compare plans
- Which plan type fits different kinds of people
- The costs that really matter (hint: it’s not just the premium)
- The red flags that should make you walk away
Let’s dig in.
What Is a Medicare Advantage Plan?
Before I talk about choosing a plan, I want to make sure we’re on the same page about what one is.
Medicare has a few main parts. Here’s the quick version:
- Part A covers hospital stays.
- Part B covers doctor visits and outpatient care.
- Part C is Medicare Advantage.
- Part D covers prescription drugs.
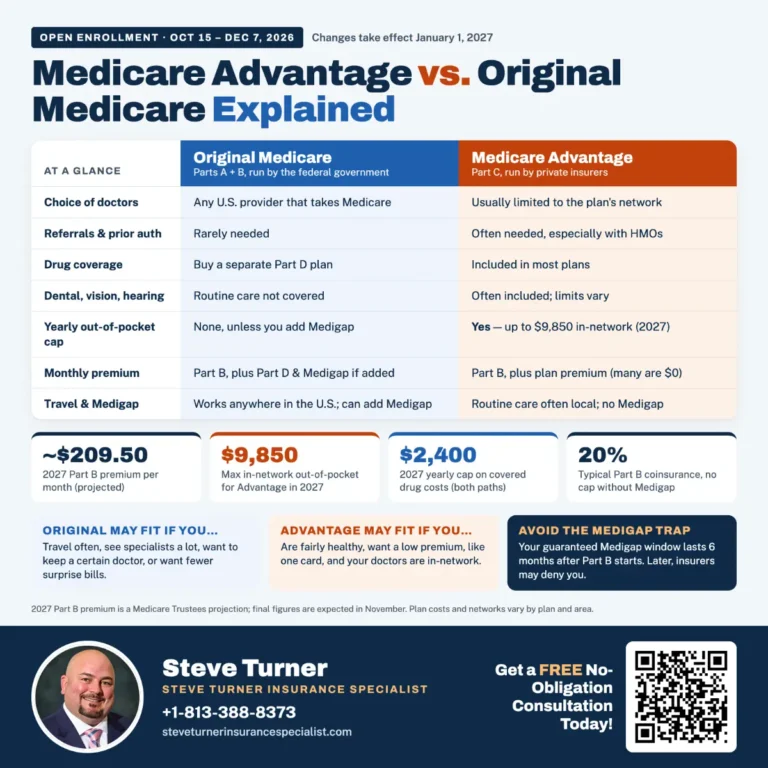
Parts A and B together are called Original Medicare. The government runs it. You can see almost any doctor in the country who takes Medicare.
A Medicare Advantage plan (Part C) is a different way to get your Medicare. Instead of the government paying your bills directly, a private insurance company does. Medicare pays that company to cover you. The company must cover everything Original Medicare covers. But it gets to set its own rules, prices, and doctor networks.
I like to think of it like this. Original Medicare is like buying each part of a meal separately. Medicare Advantage is like ordering a combo meal. You get several things bundled together, often for a lower price. But you can’t always swap out what comes in the box.
What Medicare Advantage plans usually include
Most plans bundle these together:
- Hospital coverage (Part A)
- Medical coverage (Part B)
- Prescription drug coverage (Part D), in most plans
- Extra perks like dental, vision, and hearing coverage
The big trade-off
Here’s the truth. Medicare Advantage plans often cost less each month than Original Medicare plus a supplement. Many have a $0 monthly premium. But you usually have to use doctors in the plan’s network. You may also need the plan’s approval (called prior authorization) before some care.
That’s not good or bad. It just means the right plan depends on you. And that’s what the rest of this guide is about.
How to Choose the Right Medicare Advantage Plan: My 8-Step Method
This is the exact process I use every fall. It takes a little time, but it saves a lot of stress (and money) later.
Step 1: Make a list of your doctors
I always start here, because this is where most people get burned.
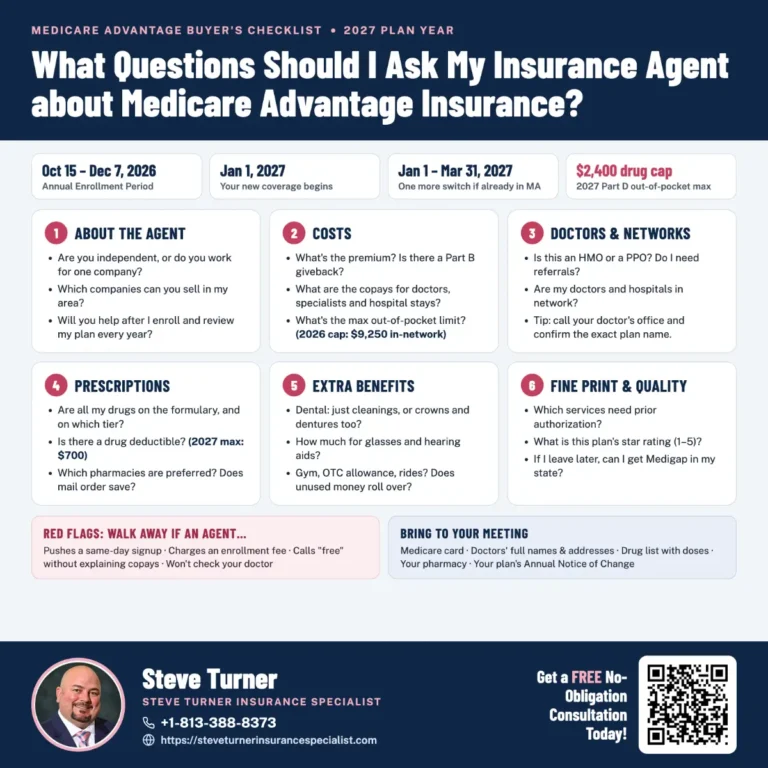
Write down every doctor you see. Include your main doctor, any specialists, and the hospital you’d want to go to in an emergency. Then check if each one is in the plan’s network.
You can do this two ways:
- Look them up in the plan’s online provider directory.
- Call your doctor’s office and ask, “Do you take [plan name] for 2027?”
I always call. Directories are sometimes out of date. A two-minute phone call can save you from a surprise bill.
Step 2: Make a list of your medicines
Next, write down every prescription you take. Include the name, the dose, and how often you take it.
Each plan has a formulary. That’s just a fancy word for the list of drugs the plan covers. Plans sort drugs into price levels called tiers. Tier 1 drugs are usually cheap. A Tier 5 drug can cost a lot.
Check three things for each medicine:
- Is it on the plan’s drug list?
- What tier is it in?
- Are there any rules, like needing approval first or trying a cheaper drug first?
Step 3: Think about how you use health care
Be honest with yourself here. Ask:
- Do I see the doctor often, or only once a year?
- Do I have a long-term health condition, like diabetes or heart disease?
- Do I have surgery or a big procedure coming up?
- Do I travel a lot, or spend winters in another state?
If you’re healthy and rarely see a doctor, a low-premium plan may work fine. If you see specialists often, you’ll want a plan with low copays and a lower yearly spending cap.
Step 4: Compare the total yearly cost
This is the step I wish more people took. Don’t just look at the monthly premium. Add up what you’d really pay in a year. I cover this more in the costs section below.
Step 5: Check the out-of-pocket maximum
Every Medicare Advantage plan has a limit on how much you’ll pay for covered medical care in a year. It’s called the maximum out-of-pocket, or MOOP. Once you hit it, the plan pays 100% of covered in-network care for the rest of the year.
For 2027, the highest a plan can set for in-network care is $9,850. Many plans set it lower. I see this number as my “worst-case scenario.” If I had a really bad year, this is the most I’d pay for covered medical care.
Step 6: Look at the extra benefits (but don’t get distracted)
Dental, vision, hearing, and gym memberships are nice. But they shouldn’t be the main reason you pick a plan. I’ve seen people choose a plan for a free gym card, then find out their heart doctor wasn’t in the network. Always put doctors and drugs first.
Step 7: Check the star rating
Medicare rates plans from 1 to 5 stars. The rating looks at things like quality of care and customer service. I aim for plans with 4 stars or more.
Step 8: Use the official tools
The best free tool I know is the Medicare Plan Finder at Medicare.gov. You can enter your zip code, your drugs, and your pharmacy. It shows you plans side by side with estimated yearly costs.
You can also call 1-800-MEDICARE or get free help from your state’s SHIP (State Health Insurance Assistance Program). SHIP counselors don’t sell insurance, so they have no reason to push you toward one plan.
The Main Types of Medicare Advantage Plans
Not all Medicare Advantage plans work the same way. Here are the types I see most often, and who I think each one fits best.
| Plan type | Need to stay in network? | Need a referral for specialists? | Best for |
|---|---|---|---|
| HMO | Yes, except emergencies | Usually yes | People who like a main doctor and want low costs |
| PPO | No, but out-of-network costs more | Usually no | People who want more choice or travel often |
| SNP | Depends on the plan | Depends on the plan | People with certain health needs or both Medicare and Medicaid |
| PFFS | Sometimes | No | People in areas with few other choices |
HMO (Health Maintenance Organization)
With an HMO, you pick a main doctor, called a primary care provider. That doctor guides your care. If you need a specialist, you usually need a referral first. HMOs often have the lowest costs. But if you go outside the network for non-emergency care, you may pay the whole bill.
PPO (Preferred Provider Organization)
A PPO gives you more freedom. You can see doctors outside the network, but you’ll pay more. You usually don’t need a referral to see a specialist. I often point snowbirds and frequent travelers toward PPOs.
One thing to know: PPOs have two spending caps. For 2027, the in-network cap can be up to $9,850. The combined cap for in-network and out-of-network care can be up to $14,800.
SNP (Special Needs Plan)
SNPs are built for specific groups of people. There are three kinds:
- D-SNP: for people who have both Medicare and Medicaid
- C-SNP: for people with certain long-term conditions, like diabetes or heart failure
- I-SNP: for people who live in a nursing home or need that level of care at home
If you fit one of these groups, an SNP can offer care designed just for you.
PFFS (Private Fee-for-Service)
These plans are less common. The plan decides how much it pays doctors and how much you pay. Not every doctor accepts these plans, so I always check before each visit.
The Costs That Really Matter
A $0 premium sounds great. And sometimes it is! But I’ve learned that the cheapest plan each month isn’t always the cheapest plan for the year. Here are the costs I always compare.
1. Monthly premium
This is what you pay the plan each month to be a member. Many plans charge $0. Keep in mind that you still have to pay your Part B premium to Medicare, even with a $0 plan.
2. Deductible
This is how much you pay before the plan starts to help. Some plans have a medical deductible. Many have a separate drug deductible. For 2027, a plan’s drug deductible can’t exceed $700.
3. Copays and coinsurance
A copay is a set amount, like $20 for a doctor visit. Coinsurance is a percentage, like 20% of the bill. I look closely at copays for the things I use most, such as:
- Primary care visits
- Specialist visits
- Hospital stays (often charged per day)
- Emergency room and urgent care
- Lab tests and imaging, like MRIs
4. Prescription drug costs
The good news is that drug costs now have a yearly cap. In 2027, once you’ve paid $2,400 out of pocket for covered drugs, you pay nothing more for covered drugs for the rest of the year. That’s up from $2,100 in 2026. Insulin costs are also capped at $35 a month for covered insulin.
5. The out-of-pocket maximum
As I said earlier, this is your safety net for medical care. It does not include your premiums or your drug costs. Drugs have their own separate cap.
My simple cost formula
Here’s the quick math I do for each plan:
Yearly premiums + expected copays + expected drug costs = my estimated yearly cost
Then I look at the out-of-pocket maximum to see my worst-case number. A plan with a $30 premium and low copays can beat a $0 plan if I see doctors often.
Extra Benefits, Star Ratings, and Red Flags
Extra benefits worth a look
Original Medicare doesn’t cover most routine dental, vision, or hearing care. That’s a big reason people like Medicare Advantage. Common extras include:
- Dental cleanings, X-rays, and sometimes fillings or dentures
- Eye exams and money toward glasses
- Hearing exams and hearing aids
- Gym or fitness memberships
- Over-the-counter allowances for things like vitamins and bandages
- Rides to doctor visits
- Meals delivered after a hospital stay
My tip: read the fine print. A plan might say it covers dental, but only $500 a year. If you need a crown, that won’t go far.
Why star ratings matter
Star ratings are Medicare’s report card for plans. A 5-star plan is rated excellent. A plan with fewer than 3 stars for three years in a row gets a warning label on Medicare.gov. Medicare is also changing how it scores some star ratings for 2027, so I check the newest rating every year instead of trusting last year’s.
Red flags I watch for
These are the warning signs that make me slow down:
- Pushy salespeople. Anyone who rushes you or says “this deal ends today” is a red flag. Medicare plans don’t work that way.
- Calls you didn’t ask for. Plans and agents aren’t allowed to cold-call you. If someone does, hang up.
- Your doctor isn’t in-network. No perk is worth losing a doctor you trust.
- A low star rating. Below 3 stars signals poor service or care.
- Lots of prior authorization rules. Some plans require approval for many services. That can delay your care.
- Big promises in ads. TV ads that promise “extra money back” may not apply in your area. Always check the plan’s details for your zip code.
Frequently Asked Questions About Choosing a Medicare Advantage Plan
These are the questions people ask me most often.
When can I join or switch Medicare Advantage plans?
The main window is the Annual Enrollment Period, October 15 to December 7, 2026. Changes start January 1, 2027. If you’re already in a Medicare Advantage plan, you get one more chance from January 1 to March 31, 2027. During that time, you can switch to a different Medicare Advantage plan or go back to Original Medicare. You can also join when you first become eligible for Medicare, or if you have a special life event, like moving.
Is a $0 premium plan a good deal?
It can be. But a $0 premium doesn’t mean $0 costs. You’ll still pay copays, coinsurance, and your Part B premium. Always compare the total yearly cost, not just the premium.
Can I keep my doctor?
Only if your doctor is in the plan’s network (or if you pick a PPO and are okay paying more to see them). Call your doctor’s office and ask before you sign up.
What should I do with my Annual Notice of Change?
Read it! If you already have a plan, it mails you an Annual Notice of Change each fall. It shows what’s changing next year, like costs, covered drugs, and doctors. I treat it as my cue to start shopping.
What happens if my plan is leaving my area?
Your plan has to tell you in writing. You’ll get a special chance to pick a new plan. You can choose another Medicare Advantage plan or go back to Original Medicare.
Can I switch back to Original Medicare later?
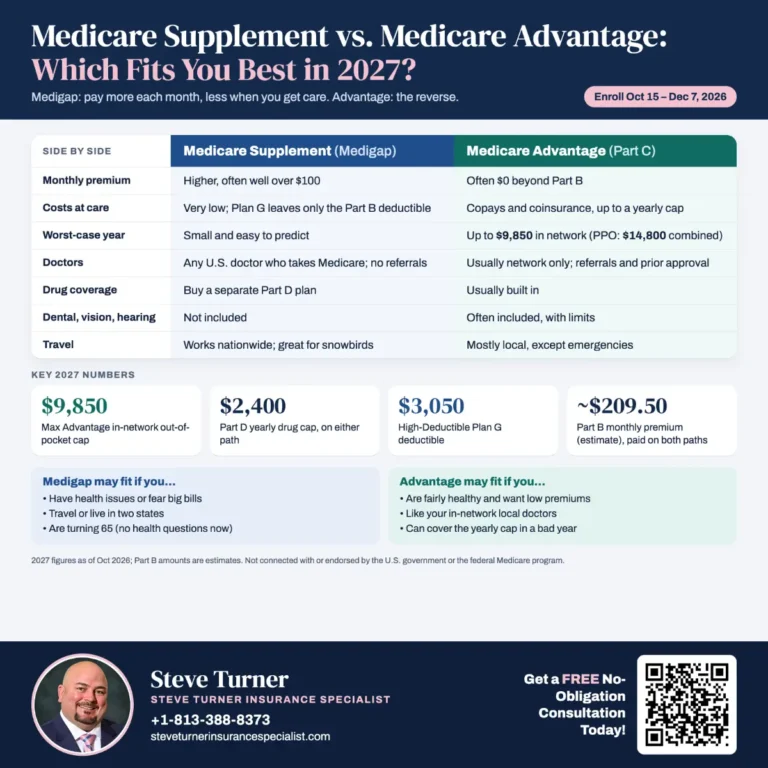
Yes, during enrollment periods. But here’s a catch I always mention. If you want a Medigap (Medicare Supplement) policy later, insurers in many states can turn you down or charge more because of your health. Think about this before you leave Original Medicare.
Do Medicare Advantage plans cover telehealth?
Most plans cover some virtual visits. Congress has also extended many Medicare telehealth rules through the end of 2027. Check your plan’s details to see what’s included.
Is it worth talking to an agent?
A good, licensed agent can help. But some agents only sell certain companies’ plans. I also like to check with a free SHIP counselor or the Medicare Plan Finder to see the full picture.
Final Thoughts: Picking the Plan That Fits You
Choosing the right Medicare Advantage plan doesn’t have to give you a headache. When I boil it all down, it comes to a few simple questions:
- Are my doctors and hospital in the network?
- Are my medicines covered, and at what cost?
- What will I really pay in a year, and what’s my worst case?
- Does the plan have 4 stars or more?
- Do the extra benefits match what I’ll actually use?
If a plan checks all of these boxes, you’ve probably found a good fit.
My last piece of advice is simple: don’t wait until December 6. Start comparing plans now, while you have time to ask questions and call your doctors. The Annual Enrollment Period ends December 7, 2026, and the right choice today can save you money and stress all through 2027.
If you get stuck, reach out for free help from Medicare or your local SHIP office. You don’t have to figure this out alone.
This article is for general information only and isn’t medical, legal, or financial advice. Plan costs and benefits vary by location, so always check the details for plans in your area.
Why choose Steve Turner Insurance Specialist?
Because I’m an “Insurance Specialist.” An “insurance specialist” is a broad term that includes insurance agents and insurance brokers, but the key difference is who the agent represents versus who the broker represents.
An “insurance agent” works directly for an insurance company and sells its specific policies to clients.
An “insurance broker” acts as an independent intermediary, comparing policies from multiple companies to find the best fit for their client’s needs, essentially representing the client rather than the insurance company.
I am both a licensed Insurance Agent and a licensed Insurance Broker.
My number one goal in life is to help people and ensure, without a shadow of a doubt, that you and your family are secure and protected. I will always be by your side, helping you mitigate risk by providing the industry’s best and most affordable insurance solutions.
I will find insurance plans for the entire family to help cover whatever life throws at you. I can help you save on severe medical emergencies, find a health insurance plan with low- or no-cost doctor visits and affordable prescription medications, and protect your family in the event of an unexpected accident or illness.
Best of all, it doesn’t cost you anything extra to use an experienced Insurance Agent and Broker like me to help you find the Insurance Plans that fit your individual, family, or business needs.
The companies that sell the insurance plans “you choose“ pay me – you don’t pay me. Calling any big insurance company directly won’t get you a lower price, as they will forward your call to the next available insurance agent on their list. You won’t have had any opportunity to learn about the insurance agent you’re speaking with in advance, understand their qualifications or experience level, or make an informed choice about who you want to work with.
Tap the Contact Me text or icon and get in touch by phone or email, or schedule a “No Obligation” chat through my calendar. I look forward to speaking with you!
OUR CLIENT REVIEWS


CONTACT STEVE TURNER INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
Richard Steven Turner’s official Florida state insurance license number (operating as Steve Turner Insurance Specialist) is W333468
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. – 8:00 p.m.
Tuesday: 7:00 a.m. – 8:00 p.m.
Wednesday: 7:00 a.m. – 8:00 p.m.
Thursday: 7:00 a.m. – 8:00 p.m.
Friday: 7:00 a.m. – 8:00 p.m.
Saturday: 7:00 a.m. – 8:00 p.m.
Sunday: 7:00 a.m. – 8:00 p.m.
MEDICare advAntage INSURANCE POSTS
INSURANCE OFFERINGS
How to Choose the Right Medicare Advantage Plan
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please contact Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can research the plans available in your Florida county using the Medicare Plan Finder at Medicare.gov, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.