
2026 Medicare Plan G Changes
2026 Medicare Plan G Changes
2026 Medicare Plan G Changes
Welcome to your definitive guide to Medicare Plan G for 2026. If you are preparing to enroll in Medicare, you are likely navigating a sea of new terms, letters, and options that can feel incredibly complex. You hear about Part A, Part B, Part C, Part D, and then a whole other alphabet of “Plans” like F, G, and N. It’s enough to make anyone’s head spin. [2026 Medicare Plan G Changes]
This article is your calm, clear, steady guide. We’ll focus on the most popular and comprehensive choice for new Medicare beneficiaries: Medicare Plan G. We will break down what this plan is, who can get it, and the critical deadlines you must not miss. We will take an exhaustive look at what it covers, what it doesn’t, and, most importantly, demystify the so-called “changes” for 2026. Our mission is to replace confusion with confidence, so you can understand why Plan G is considered the gold standard of coverage and decide if it is the right choice for you. [2026 Medicare Plan G Changes]
Let’s start at the very beginning by clarifying what Plan G is. First, it’s important to know that Plan G is not part of the government’s Original Medicare. Instead, Medicare Plan G is a type of Medicare Supplement Insurance, also known as Medigap. Think of Original Medicare (Part A and Part B) as your primary health insurance. It covers a lot, but it leaves behind “gaps” in coverage, like deductibles and a significant 20% coinsurance that you are responsible for paying. A Medigap plan is a separate, private insurance policy you buy to work alongside Original Medicare and fill those gaps. It’s like financial “gap insurance” for your health, designed to cover costs Medicare doesn’t. Plan G is one of the ten standardized Medigap plans available, and it has become the most popular choice for new enrollees because of its comprehensive coverage. [2026 Medicare Plan G Changes]
Who is eligible to purchase a Medicare Plan G policy? To qualify, you must first be enrolled in both Medicare Part A and Medicare Part B. Additionally, a key rule determines who can buy which Medigap plan. A law passed in 2015, known as MACRA, changed the Medigap landscape. As of January 1, 2020, Medigap plans are no longer allowed to cover the Medicare Part B deductible. This means Plan F, once the most popular plan because it covered everything, is no longer available to people new to Medicare. If you became eligible for Medicare before January 1, 2020, you can still buy a Plan F. However, if you turn 65 in 2026, Plan G is the most comprehensive Medigap plan you can buy. [2026 Medicare Plan G Changes]
The enrollment deadline is the most critical piece of the puzzle. You have a one-time, six-month Medigap Open Enrollment Period. This is your golden ticket. This period automatically begins on the first day of the month that you are both 65 or older and enrolled in Medicare Part B. During these six months, you have guaranteed issue rights. This means insurance companies must sell you any Medigap plan they offer, including Plan G. They cannot deny you coverage or charge you a higher premium because of any pre-existing health conditions, whether it’s diabetes, a heart condition, or a past cancer diagnosis. If you miss this six-month window and apply for Plan G later, you will likely have to go through medical underwriting, and the insurance company can deny your application based on your health history. For this reason, securing your Medigap plan during this initial window is one of the most important decisions you will make. [2026 Medicare Plan G Changes]
How Plan G Works: Your Financial Shield Against Medicare’s Gaps
To appreciate the power of Plan G, we must first look closely at the problem it is designed to solve: the high out-of-pocket costs of Original Medicare. While Medicare Part A and Part B provide excellent foundational coverage, they were never designed to cover 100% of your costs.
The Problem: The Gaps in Original Medicare (Projected for 2026)
- The Part A Hospital Deductible: When you are admitted to a hospital, you are responsible for a large deductible for each “benefit period.” In 2026, this deductible is projected to be approximately $1,716. [2026 Medicare Plan G Changes]
- Part A Hospital Coinsurance: For very long hospital stays, you have to pay a daily coinsurance. For days 61-90 in 2026, this is projected to be around $429 per day. [2026 Medicare Plan G Changes]
- Skilled Nursing Facility Coinsurance: After the first 20 days of a covered stay, you are responsible for a daily coinsurance. For days 21-100 in 2026, this is projected to be around $214.50 per day. [2026 Medicare Plan G Changes]
- The Part B 20% Coinsurance: This is the biggest and most dangerous gap. After you meet your small annual Part B deductible, you are responsible for 20% of the cost of all your doctor visits, outpatient procedures, and medical equipment. Crucially, this 20% responsibility has no annual limit. A $100,000 cancer treatment could leave you with a $20,000 bill. [2026 Medicare Plan G Changes]
The Solution: A Detailed Look at Plan G’s Comprehensive Coverage
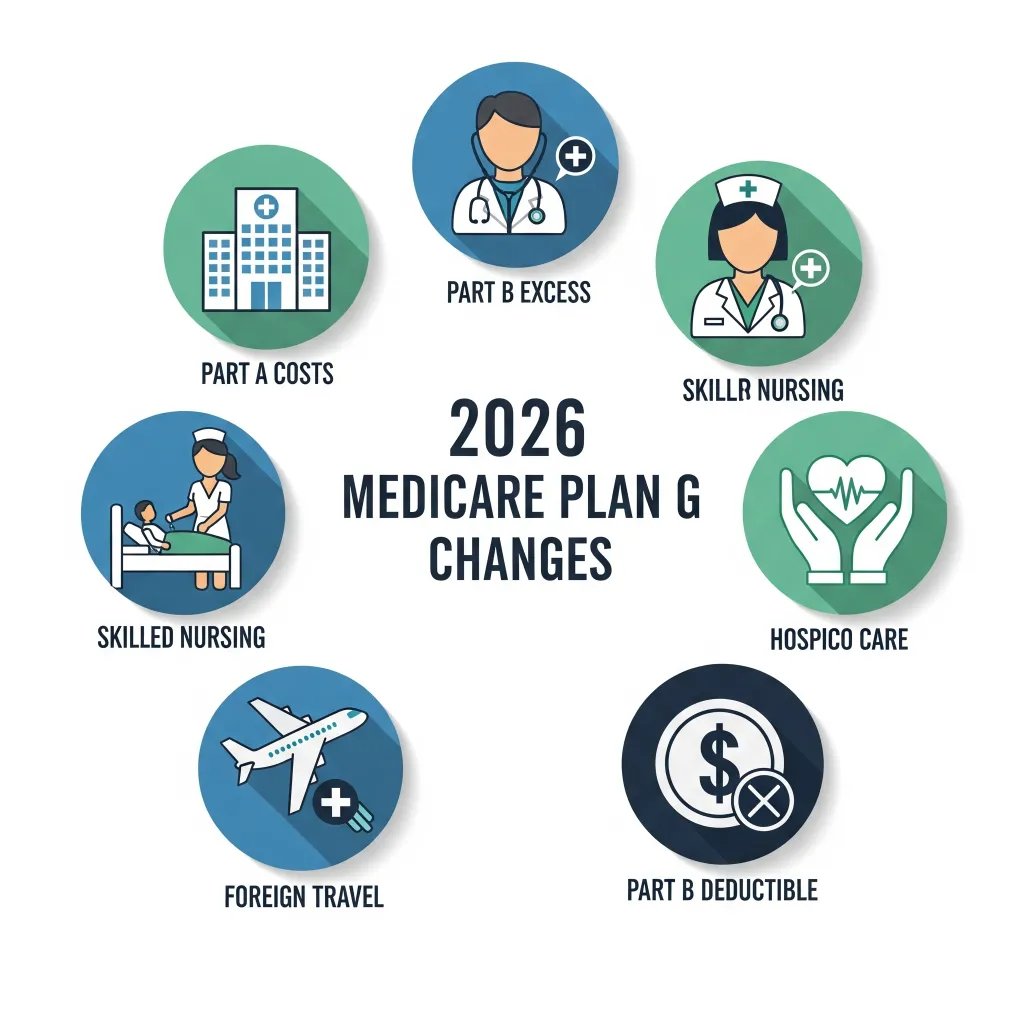
Medicare Plan G acts as a nearly complete financial shield, stepping in to pay for almost all of these gaps. With Plan G, your cost-sharing for Medicare-covered services becomes simple and predictable. Here is a line-by-line breakdown of what Plan G covers: [2026 Medicare Plan G Changes]
- Part A Deductible: Covered 100%. Your Plan G covers the projected $1,716 hospital bill.
- Part A Coinsurance and Hospital Costs: Covered 100%. It also provides you with an additional 365 lifetime reserve days for hospital stays.
- Part A Hospice Care Coinsurance or Copayment: Covered 100%. [2026 Medicare Plan G Changes]
- Skilled Nursing Facility Coinsurance: Covered 100%. Your Plan G pays the projected $214.50 per day for days 21-100.
- Part B Coinsurance or Copayment: Covered 100%. This is the most important benefit. The uncapped 20% financial risk is eliminated. Whether your doctor’s bill is $100 or $100,000, Plan G pays your 20% share. [2026 Medicare Plan G Changes]
- Part B Excess Charges: Covered 100%. This key benefit protects you from a rare but possible billing situation. Some doctors do not accept Medicare’s approved payment amount as payment in full. They may legally charge you up to 15% more than the Medicare-approved amount. This extra 15% is called an “excess charge.” Plan G pays this, so you don’t have to worry about finding doctors who “accept assignment.”
- First Three Pints of Blood: Covered 100%. [2026 Medicare Plan G Changes]
- Foreign Travel Emergency: Covers 80% of the cost of emergency care you receive outside of the United States, up to a lifetime limit of $50,000.
The One Thing You Pay: The Annual Part B Deductible
With Plan G, your financial responsibility for all Medicare-approved hospital and medical services for the year boils down to one small, predictable cost: the annual Part B deductible. [2026 Medicare Plan G Changes]
- For 2026, the Part B deductible is projected to be approximately $288.00
Let’s see this in action with an example:
Imagine Sarah enrolls in Plan G in 2026.
- Her first doctor visit: In February, she visits her primary care doctor. The bill is $150. Since this is her first medical service of the year, she pays the full $150. She has now paid $150 toward her $288 Part B deductible. [2026 Medicare Plan G Changes]
- Her second doctor visit: In March, she sees a specialist. The bill is $250. She pays the remaining $138 of her Part B deductible. [2026 Medicare Plan G Changes]
- Her deductible is now met: She has now paid a total of $288 out-of-pocket for the year. For the rest of that specialist bill, Medicare pays 80%, and her Plan G pays the remaining 20%.
- For the rest of the year: From that point forward, for every single doctor visit, hospital stay, surgery, or any other Medicare-covered service she receives for the rest of 2026, she will pay $0. Medicare will pay its share, and her Plan G will pay the rest.
This incredible simplicity and predictability is why Plan G is so highly valued. You know at the start of the year that your maximum out-of-pocket exposure for all Medicare-covered services will be just that one small deductible. [2026 Medicare Plan G Changes]
The “Changes” for 2026: Understanding Value and Cost
This is the most important section for understanding the 2026 landscape. Many people ask, “What are the changes to Plan G for next year?” The answer can be confusing, so let’s be very clear. [2026 Medicare Plan G Changes]
The Big Clarification: Plan G Benefits DO NOT Change
This is the fundamental truth of Medigap. The federal government standardizes Plan G benefits. This means a Plan G sold in 2026 will have the same medical benefits as a Plan G sold in 2025 or any other year. The list of what it covers—the Part A deductible, the 20% coinsurance, etc.—is set in stone. [2026 Medicare Plan G Changes]
So, when we talk about “changes,” we are not talking about a change in the plan’s design. Instead, we are talking about changes in the value it provides and the cost you pay for it. [2026 Medicare Plan G Changes]
Change #1: The Value of Your Coverage Automatically Increases
Because Plan G pays for the gaps in Original Medicare, its value is directly tied to the size of those gaps. As Medicare costs rise, the value of your Plan G coverage rises with them. [2026 Medicare Plan G Changes]
- The Part A Deductible: As this deductible is projected to rise from $1,676 in 2025 to around $1,716 in 2026, the Plan G benefit that pays this for you automatically increases by the same amount. You’re protected from higher costs without your plan’s benefits having to change. [2026 Medicare Plan G Changes]
- The 20% Coinsurance: As the cost of medical care, surgeries, and treatments continues to rise with inflation, the dollar amount of that 20% coinsurance also gets bigger. The value of your Plan G, which covers that 20% no matter how large it gets, becomes more powerful every single year. [2026 Medicare Plan G Changes]
Change #2: The Cost You Pay (Your Responsibility) Will Increase Slightly
Plan G does not cover the annual Part B deductible. [2026 Medicare Plan G Changes]
- Because this deductible is projected to rise from $257 in 2025 to about $288 in 2026, the total amount a Plan G member pays out of pocket for the year will also increase slightly. [2026 Medicare Plan G Changes]
Change #3: Your Monthly Premium Will Likely Increase
This change most directly affects your budget. The monthly premium you pay the private insurance company for your Plan G policy will almost certainly increase in 2026. Understanding why this happens matters. [2026 Medicare Plan G Changes]
- Medical Inflation: Healthcare costs consistently rise faster than general inflation. As doctors, hospitals, and drug companies charge more, the insurance plans that pay those bills must also charge more to cover the increased costs. [2026 Medicare Plan G Changes]
- Your Age: The vast majority of Medigap plans sold today use “attained-age” pricing. This means your premium is based on your current age, and it will go up each year as you get older. A 66-year-old will pay slightly more than a 65-year-old, and so on. [2026 Medicare Plan G Changes]
- Insurance Company Rate Adjustments: Each year, every insurance company analyzes its costs and the claims paid out for its pool of policyholders. Based on this data, they will implement a rate increase for the upcoming year. This is why the premium for the same Plan G can vary significantly from one company to another. [2026 Medicare Plan G Changes]
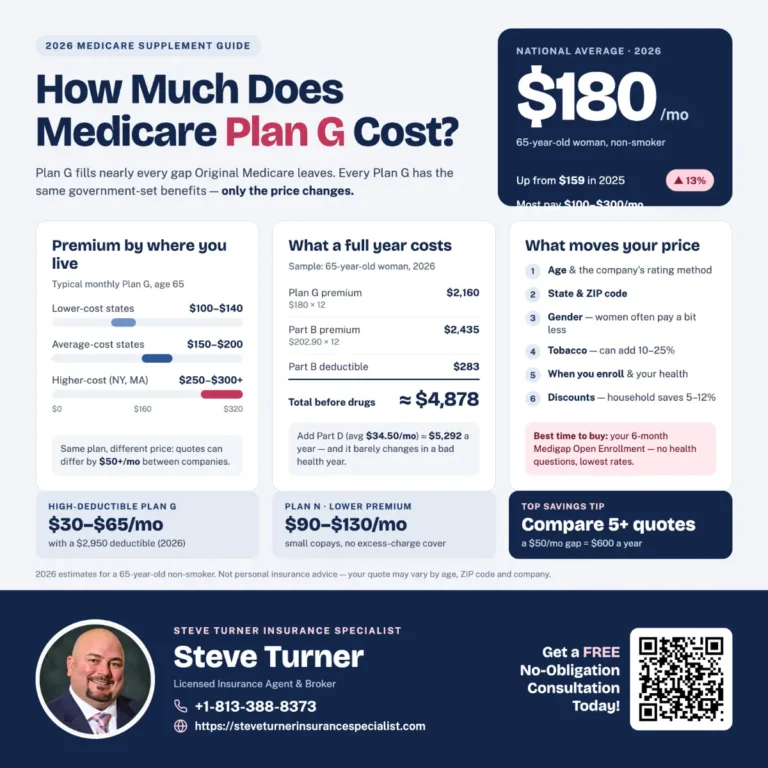
A 65-year-old enrolling in a new Plan G in Florida in 2026 can expect monthly premiums in the range of $180 to $250 per month, depending on the insurance company, gender, and specific location. This will likely be 3-6% higher than the average premiums were for new enrollees in 2025. [2026 Medicare Plan G Changes]
Completing Your Coverage: What Plan G Doesn’t Cover
While Plan G provides nearly seamless coverage for hospital and medical services, it is not all-encompassing. To build a complete healthcare portfolio, you need solutions for what it doesn’t cover. [2026 Medicare Plan G Changes]
Prescription Drugs (The Biggest Gap)
Medicare Supplement plans, including Plan G, do not cover prescription drugs. This is critical information. To help pay for your medications and, more importantly, avoid the lifelong Late Enrollment Penalty, you must enroll in a separate stand-alone Medicare Part D Prescription Drug Plan (PDP). You will pay a separate monthly premium for this plan. [2026 Medicare Plan G Changes]
Routine Dental, Vision, and Hearing Care
Original Medicare and Medigap Plan G do not cover routine care for your teeth, eyes, or ears. This includes: [2026 Medicare Plan G Changes]
- Dental cleanings, fillings, crowns, and dentures.
- Eye exams for glasses and the glasses or contact lenses themselves.
- Hearing aids and the exams to fit them.
To cover these items, you have two main options:
- Purchase a Stand-Alone DVH Plan: Many insurance companies offer private Dental, Vision, and Hearing plans that you can buy in addition to your Medigap plan. These plans have their own monthly premiums and provide a specific set of benefits for these services. [2026 Medicare Plan G Changes]
- Consider a Different Path (Medicare Advantage): If these benefits are a top priority and you are willing to accept network restrictions, a Medicare Advantage (Part C) plan might be a better fit, as these plans often bundle dental, vision, and hearing coverage into their package. [2026 Medicare Plan G Changes]
Long-Term Care
This is the single largest gap in all of Medicare. Plan G helps cover short-term, skilled care in a nursing facility for rehabilitation. It does not cover long-term custodial care, which is help with daily activities like bathing, dressing, and eating. You must pay for this type of care out of pocket or through a separate long-term care insurance policy. [2026 Medicare Plan G Changes]
Is Plan G Right for You? A 2026 Decision Guide
Plan G is a phenomenal choice for many, but it’s not the only choice. Here is how to think about whether it fits your specific needs. [2026 Medicare Plan G Changes]
Plan G is Likely a Perfect Fit if:
- You Want Maximum Peace of Mind: If you want to budget for your healthcare and never worry about a surprise bill from a hospital or doctor, Plan G is tailor-made for you. Its predictability is its greatest strength. [2026 Medicare Plan G Changes]
- You Travel Frequently or are a “Snowbird”: Because Plan G works with Original Medicare, you can see any doctor or visit any hospital in the United States that accepts Medicare. There are no networks. This is an essential feature for people who spend significant time in different states.
- You Have Complex Health Needs: If you have a serious health condition and need to see specific specialists at renowned medical centers, Plan G lets you do so without worrying about referrals or network restrictions. [2026 Medicare Plan G Changes]
Comparing Plan G to Plan N
For those looking for the comprehensive coverage of Medigap but wanting a lower monthly premium, Plan N is the closest alternative to Plan G. [2026 Medicare Plan G Changes]
- Similarities: Like Plan G, Plan N covers the 20% coinsurance in full. [2026 Medicare Plan G Changes]
- Differences: In exchange for a lower monthly premium (often $30-$50 less), with Plan N, you agree to pay a small copayment of up to $20 for some doctor visits and a $50 copayment for an ER visit that doesn’t result in an inpatient admission. Plan N also does not cover Part B excess charges.
- The 2026 Decision: For many healthy people, a Plan N can be a great way to save money on premiums. However, for those who visit the doctor frequently or want the absolute simplest, most seamless coverage, Plan G remains the superior choice. [2026 Medicare Plan G Changes]
Finding Your Guide in a Complex Market
We have taken a thorough look at Medicare Plan G. We’ve seen that while its core benefits remain stable, its cost and value keep changing. The most important decision you will make in 2026 is not just whether to get a Plan G, but which of the dozens of insurance companies to buy it from. Because the benefits are identical, the only difference between a Plan G from Company A and a Plan G from Company B is the price you pay and the company’s reputation for service and rate stability.
Shopping all these companies and comparing their rates and histories on your own can be daunting. This is why working with an experienced, independent, licensed insurance agent is so valuable. Think of an agent as your personal shopper. They can take your information and instantly compare the prices for the same Plan G from all the major carriers in your area, saving you time and potentially a lot of money.
This expert service is also provided at absolutely no extra cost. When you enroll in a plan through an agent, the insurance company pays them a commission.10. The premium you pay is legally required to be the same whether you use an agent or buy directly from the company. This system gives you access to free, unbiased, professional advice.
Medicare Plan G offers unmatched security and predictability, but navigating the market to find the best value is key. It is usually best to use a licensed insurance agent, such as Steve Turner of SteveTurnerInsuranceSpecialist.com. Steve Turner is a licensed Agent/Broker contracted with most Medicare Insurance Carriers. An expert like Steve can help you understand the nuances of the 2026 Medigap market, find the most competitively priced Plan G for you, and ensure you have a solid foundation of health coverage that gives you peace of mind for years to come.
OUR CLIENT REVIEWS


CONTACT STEVE TURNER INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
Richard Steven Turner’s official Florida state insurance license number (operating as Steve Turner Insurance Specialist) is W333468
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. – 8:00 p.m.
Tuesday: 7:00 a.m. – 8:00 p.m.
Wednesday: 7:00 a.m. – 8:00 p.m.
Thursday: 7:00 a.m. – 8:00 p.m.
Friday: 7:00 a.m. – 8:00 p.m.
Saturday: 7:00 a.m. – 8:00 p.m.
Sunday: 7:00 a.m. – 8:00 p.m.
MEDICare Plan G INSURANCE POSTS
INSURANCE OFFERINGS
2026 Medicare Plan G Changes | What Floridians Must Know!
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please contact Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can research the plans available in your Florida county using the Medicare Plan Finder at Medicare.gov, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.