

What Does Medicare Advantage Cover? What’s Included, and What Isn’t, in 2027
Reviewed by Steve Turner, CLU, REBC · Florida License W333468 · NPN 18030539 · November 2026
Date Published: 2026-07-01
Updated: 2026-11-21
Yes, some Medicare Advantage plans give money back. They do it through a Part B giveback, also called a Part B premium reduction. The plan pays part or all of your Medicare Part B premium, so less is taken out of your Social Security check each month, or your Medicare premium bill goes down. It’s not a separate check, and it’s not a government program. Certain Medicare Advantage plans in Tampa and across Florida offer it. Here’s how it works for 2027, who qualifies, and what to check before you choose a plan.
Key takeaways
- Same core coverage: hospital, doctor, outpatient, preventive, emergency, home health, skilled nursing and medical equipment, the same services Original Medicare covers.
- Usually more: most plans include drug coverage, and many add dental, vision, hearing, fitness and over-the-counter allowances. Extras vary by plan and county.
- Different rules: networks, referrals and prior authorization decide whether a covered service is paid in your situation.
- A yearly cap: in 2027, plans can’t make you pay more than $9,850 in-network ($14,800 in and out of network combined) for covered medical care. Drug costs are capped at $2,400.
- Common exclusions: long-term custodial care, most non-emergency care outside the network or service area, cosmetic care and anything beyond a plan’s extra-benefit limits.
Reviewed by Steve Turner, CLU, REBC · Florida License W333468 · NPN 18030539 · November 2026
Medicare Advantage (Part C) must cover everything Original Medicare Part A and Part B cover, except hospice care, which Original Medicare still pays for. Most plans also include Part D prescription drug coverage, and many add dental, vision, hearing, and other extras. What changes is how you get that care: through the plan’s network, with the plan’s copays, and sometimes only after the plan approves it. Here’s what Medicare Advantage plans in Tampa and across Florida cover in 2027, the common exclusions, and how to check a specific plan.
What Medicare Advantage covers
| Coverage | What’s included | What to check in a plan |
|---|---|---|
| Hospital care (Part A) | Inpatient stays, inpatient mental health care, surgery, hospital meals and nursing | Daily hospital copay and how many days it applies |
| Skilled nursing facility | Short-term skilled care after an illness or injury | Copays by day; many plans waive Medicare’s 3-day hospital stay rule |
| Home health care | Part-time skilled nursing and therapy at home when you’re homebound | Prior authorization rules |
| Doctor and outpatient care (Part B) | Primary care, specialists, outpatient surgery, lab work, X-rays, MRIs and CT scans | Specialist copay, referral rules, imaging copays |
| Preventive care | Annual wellness visit, screenings (mammograms, colonoscopies), flu, COVID-19 and pneumonia shots | Usually $0 in-network |
| Emergency and urgent care | Covered anywhere in the U.S., in or out of network | ER copay; worldwide emergency coverage is a plan extra |
| Mental health | Therapy, psychiatry, telehealth visits | Which providers are in-network |
| Durable medical equipment | Walkers, wheelchairs, oxygen, CPAP machines, diabetic supplies | Approved suppliers and coinsurance |
| Ambulance | Emergency ambulance transport | Ambulance copay |
| Prescription drugs (Part D) | Included in most plans (called MAPD plans) | Your drugs on the formulary, the drug tier, the pharmacy network |
| Extra benefits | Dental, vision, hearing, fitness, OTC allowances and more | Dollar limits, provider networks, what counts |
Part A and Part B services
A Medicare Advantage plan must cover every medically necessary service Original Medicare covers, and since 2024, plans must follow Original Medicare’s coverage rules when deciding whether something is medically necessary. They can’t use stricter criteria to deny a service Original Medicare would cover.
A plan can set its own cost-sharing. Instead of Original Medicare’s Part A deductible ($1,776 per benefit period in 2027) and 20% Part B coinsurance, you’ll usually pay set copays, such as a daily hospital copay for the first several days of a stay and a fixed amount per specialist visit.
Prescription drug coverage
Most Medicare Advantage plans include Part D. In 2027:
- Out-of-pocket drug costs are capped at $2,400 for covered drugs (up from $2,100 in 2026).
- Insulin costs no more than $35 a month for covered insulins.
- Recommended adult vaccines, like shingles and RSV, are $0.
- You can spread drug costs over the year in monthly payments through the Medicare Prescription Payment Plan.
Some plans don’t include drugs. These “MA-only” plans are often designed for veterans who use VA prescriptions. If you choose one without other creditable drug coverage, you can face a late enrollment penalty later. See Medicare Part D for more.
Extra benefits Medicare Advantage may cover
These are the benefits most people mean when they ask what Medicare Advantage covers that Original Medicare doesn’t. Each plan chooses its own, so they vary by plan and county:
- Dental: cleanings, exams, and X-rays; some plans also cover fillings, extractions, dentures, or crowns up to a yearly dollar limit
- Vision: a routine eye exam and an allowance for glasses or contacts
- Hearing: a hearing exam and an allowance toward hearing aids
- Fitness: a gym or fitness program membership
- Over-the-counter (OTC) allowance: a quarterly or monthly amount for health items
- Transportation to medical appointments
- Meals after a hospital stay
- Part B giveback: some plans lower your Part B premium (see Medicare Advantage give money back)
- Benefits for chronic conditions: some plans offer grocery, utility, or other help only to members with certain conditions who qualify
Read the limits. A plan that “covers dental” might pay only $1,000 a year, or cover only preventive visits. An extra benefit is only as good as its dollar limit and its network.
Common exclusions in Medicare Advantage: what it doesn’t cover
| Not covered | What to know |
|---|---|
| Long-term custodial care | Help with bathing, dressing or eating in a nursing home, assisted living or at home isn’t covered by Medicare or Medicare Advantage. Skilled nursing care is covered only for a limited time. Plan for this with long-term care insurance or savings. |
| Hospice | Covered, but by Original Medicare, not the plan. You keep your Medicare Advantage plan for care unrelated to your terminal illness and for its extra benefits. |
| Out-of-network care in an HMO | Except for emergencies, urgent care and dialysis while you’re traveling, you pay the full cost. PPOs cover out-of-network care at higher cost. |
| Care outside the service area | Routine care outside your plan’s area usually isn’t covered. Emergencies and urgent care are covered anywhere in the U.S. |
| Routine care outside the U.S. | Not covered. Some plans include worldwide emergency coverage as an extra. |
| Services without required approval | If a plan requires prior authorization or a referral and you skip it, the plan can refuse to pay. |
| Drugs not on the formulary | Not covered unless you get an exception. Drugs used only for weight loss are excluded from Part D by law. |
| Cosmetic procedures | Not covered unless medically necessary, such as reconstruction after an injury or mastectomy. |
| Most routine foot care, massage and acupuncture | Not covered, except limited foot care for conditions like diabetes and acupuncture for chronic low back pain. Some plans add these as extras. |
| Costs above extra-benefit limits | Anything beyond your plan’s dental, vision or hearing allowance is yours to pay. |
| Medigap | You can’t use a Medicare Supplement policy with Medicare Advantage. |
“Not covered” can mean two things. Some services aren’t covered by any Medicare plan, like long-term custodial care. Others are covered, but not in your situation, like seeing an out-of-network specialist in an HMO without approval. The second kind is where most surprise bills come from.
Networks, prior authorization and referrals
These rules decide whether a covered service is paid:
- HMO plans usually require you to use in-network providers and get referrals to see specialists.
- PPO plans let you see out-of-network providers without referrals, but at a higher cost.
- Prior authorization means the plan must approve certain services before you get them, often hospital stays, skilled nursing, home health, imaging, outpatient surgery, and some drugs. Your doctor’s office usually handles the request.
- If a plan denies coverage, you can appeal. Many denials are overturned on appeal.
Costs: what you still pay
Covered doesn’t mean free. You may pay a monthly plan premium (many Tampa-area plans have a $0 premium), the Part B premium ($209.40 a month in 2027 for most people), and copays or coinsurance when you get care.
The yearly out-of-pocket limit protects you in a bad year. Once you hit it, the plan pays 100% of covered Part A and Part B services for the rest of the year. For 2027, plans can set the limit at up to $9,850 for in-network care and $14,800 combined for in- and out-of-network care. Many plans set it lower. Drug costs and extra benefits don’t count toward it. See Medicare vs. Medicare Advantage for how these costs compare with Original Medicare.
How to check what a specific plan covers
Every plan publishes three documents:
- Summary of Benefits: a short overview of copays, the out-of-pocket limit, and extras.
- Evidence of Coverage: the full contract, including exclusions and prior authorization rules.
- Annual Notice of Change: what’s changing next year. If you’re already in a plan, read it before Annual Enrollment ends on December 7.
Use Medicare Plan Finder at Medicare.gov to check your drugs, and call your doctors’ offices to confirm they take the plan.
Medicare Advantage coverage in Tampa
Coverage on paper only helps if your doctors are in-network. In the Tampa Bay area, networks differ across Tampa General, BayCare, AdventHealth, HCA Florida, and Moffitt Cancer Center, and a plan that includes one system may not include another. I check your doctors, hospitals, and prescriptions before you choose.
Snowbirds: an HMO covers only emergency and urgent care when you’re up north. If you spend months outside Florida, look at PPOs with national networks, or compare Medicare Advantage with a Medicare Supplement plan.
How I help
- Compare plans in your ZIP code side by side: coverage, copays, out-of-pocket limits, and extras.
- Check your doctors, hospitals, and prescriptions against each plan.
- Read the fine print on prior authorization and limits on extra benefits.
- After you enroll, I help with claims, denials, and appeals.
My help costs you nothing. Premiums are the same whether you enroll through me or directly with the plan.
Medicare Advantage coverage FAQs
Does Medicare Advantage cover everything Original Medicare covers?
Yes, except hospice, which Original Medicare pays for even if you’re in a Medicare Advantage plan. Plans must cover all medically necessary Part A and Part B services and follow Original Medicare’s coverage rules.
What does Medicare Advantage cover that Original Medicare doesn’t?
Most plans include prescription drug coverage, and many add dental, vision, hearing, fitness, OTC allowances, and transportation. Plans also have a yearly out-of-pocket limit, which Original Medicare doesn’t.
What does Medicare Advantage not cover?
Medicare Advantage doesn’t cover long-term custodial care, routine care outside the U.S., most non-emergency out-of-network care in HMOs, cosmetic procedures, non-formulary drugs, or costs above the plan’s extra-benefit limits.
Does Medicare Advantage cover dental, vision, and hearing?
Many plans do, but coverage varies. Most cover routine exams and give an allowance for glasses or hearing aids. Dental coverage ranges from cleanings only to dentures and crowns, usually with a yearly dollar limit.
Does Medicare Advantage cover nursing home care?
It covers short-term skilled nursing care after an illness or injury, usually with daily copays. It doesn’t cover long-term custodial care in a nursing home.
Does Medicare Advantage cover me when I travel?
Medicare Advantage covers emergency and urgent care anywhere in the U.S. Routine care outside your service area usually isn’t covered unless you have a PPO with travel or national coverage. Some plans cover emergencies worldwide.
Can a Medicare Advantage plan deny a service Original Medicare would cover?
It shouldn’t. Plans must follow Original Medicare’s coverage rules, but they can require prior authorization. If a service is denied, you can appeal, and I can help.
Talk with Steve
Want to know exactly what a plan covers before you enroll? Call me at (813) 388-8373 or book a free review.
Related: Medicare Advantage plans in Tampa · Medicare vs. Medicare Advantage · Medigap vs. Medicare Advantage · Can I change Medicare Advantage plans? · 2027 Medicare Advantage changes
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, LICENSED INSURANCE AGENT & BROKER
Questions? Call, text, or book a time below; I answer calls and emails 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
EMAIL STEVE
OFFICE LOCATION
Address: 14502 N Dale Mabry Hwy, Suite 200, Tampa, FL 33618
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
More on Medicare Advantage
-

Are Medicare Advantage Plans Going Away? What’s Really Changing in 2027
By Steve Turner
• 2025-10-28
Medicare Advantage isn’t going away, but some plans are. Here’s what’s changing for 2027, how many Florida plans are ending, and what to do if yours won’t renew. -

Is Medicare Advantage Insurance Part A Insurance?
By Steve Turner
• 2026-06-23
Is Medicare Advantage the same as Part A? Understand how Part C includes your Part A benefits and what this means for your hospital coverage in 2026. -
Does Medicare Advantage Insurance Cover Long-Term Care?
By Steve Turner
• 2026-06-17
Does Medicare Advantage cover long-term care? Usually not. See what Part C pays for (rehab, home health, hospice) and what covers nursing home costs instead. -
15 Questions to Ask When Picking a Medicare Advantage Plan
By Steve Turner
• 2026-10-08
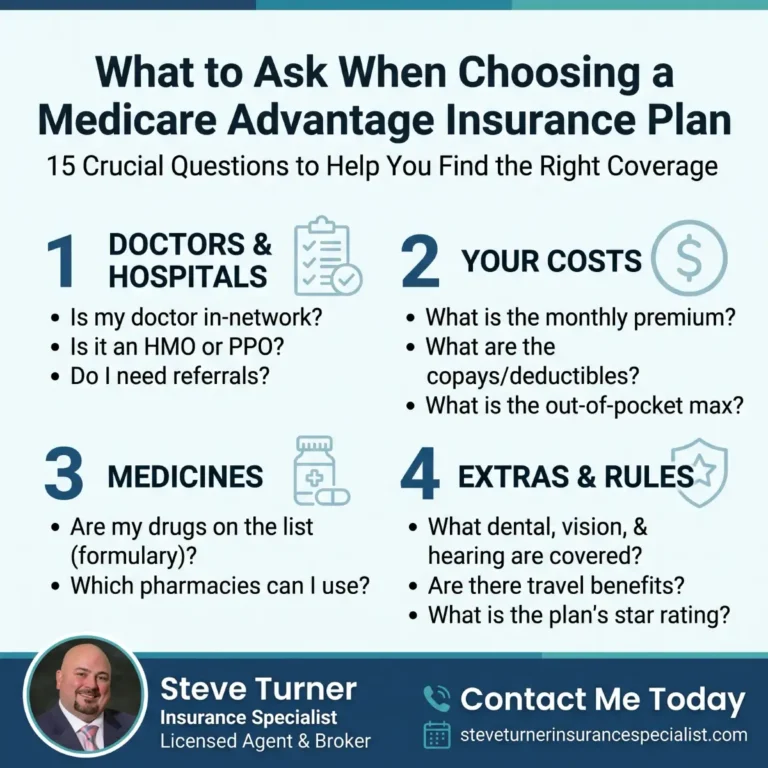
15 questions to ask before choosing a Medicare Advantage plan: doctor networks, HMO vs PPO, out-of-pocket max, drug coverage, extras & red flags to avoid. -
Medicare Supplement vs. Advantage: Which Is Best in 2027?
By Steve Turner
• 2026-10-16
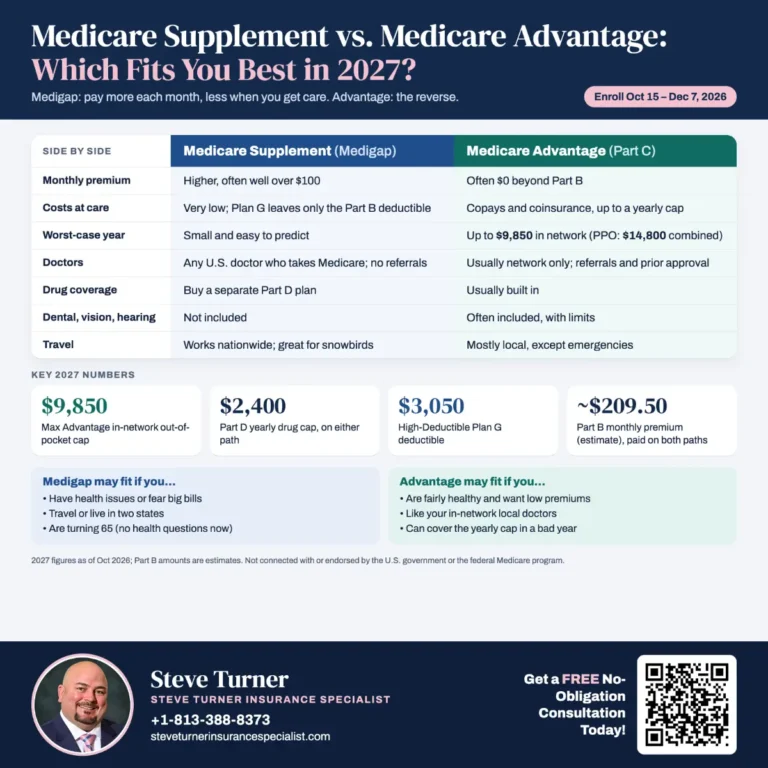
Medicare Supplement vs. Medicare Advantage in 2027: compare costs, doctor choice, out-of-pocket caps, and pros and cons to find the plan that fits you best. -
Does Medicare Advantage Insurance Cover Part A Deductible?
By Steve Turner
• 2026-06-21
Does Medicare Advantage cover the Part A deductible? Learn how Part C plans replace your hospital costs with set copays to help you save money in 2026.
Medicare plan availability differs by state and county. Steve Turner is licensed in AL, CO, FL, GA, NC, SC, TN, and TX.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
MEDICARE DISCLAIMER
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
Steve Turner
Steve Turner, CLU®, REBC® is licensed in AL, CO, FL, GA, NC, SC, TN, and TX · NPN 18030539 · Florida License W333468
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals NABIP®. Steve holds the Registered Employee Benefits Consultant® (REBC®) designation. Steve also holds the “Chartered Life Underwriter” designation (CLU®), a professional credential for individuals specializing in life insurance and estate planning, conferred by the American College of Financial Services. Since 2016 (over 10 years), Steve has helped individuals, families, Medicare beneficiaries, and small businesses find the right coverage to meet their needs. Steve has earned 180+ Google reviews from happy clients.
Steve Turner is a licensed agent appointed by Florida Blue in Florida.