

How To Choose Medicare Supplemental Insurance
Choosing Medicare can feel harder than it needs to be.
You are told to learn the parts of Medicare. Then you hear about Medicare Supplement Insurance, also called Medigap. Then you hear about Part D, Medicare Advantage, plan letters, premiums, enrollment windows, and rules that do not repeat every year. It is a lot. Medicare’s own materials show that once you have Original Medicare—that means Part A for hospital insurance and Part B for medical insurance—you may also shop for a Medigap policy to help with your out-of-pocket costs. (Medicare)
That leads to one of the most useful Medicare questions of all:
How do you choose Medicare Supplemental Insurance?
The short answer is this:
You choose Medicare Supplemental Insurance by first deciding whether you want to keep Original Medicare, then comparing Medigap plan letters, prices, pricing methods, enrollment timing, and company quality. Medicare says Medigap policies are standardized by letter in most states, which means the same letter has the same basic benefits no matter which company sells it. Medicare also says the price is the only difference between same-letter plans sold by different companies, so once you choose the right letter, you still need to compare insurers carefully. (Medicare)
That may sound simple, but people still make big mistakes.
Some choose the lowest premium and ignore how it may rise later. Some buy too late and lose their strongest federal protections. Some assume Medigap covers things it usually does not, such as most dental care, routine vision, hearing aids, or prescription drugs. Medicare says your one-time 6-month Medigap Open Enrollment Period starts the first month you have Part B and are 65 or older. After that period, you may not be able to buy a policy, or it may cost more. Medicare also says Medigap plans sold after 2005 do not include prescription drug coverage. (Medicare)
So the real answer is more complete:
The best way to choose Medicare Supplemental Insurance is to match the right level of cost protection to your budget, health needs, doctor-choice preferences, and timing—then compare companies selling the same plan letter in your area. This article will walk you through that step by step in plain English. Everything below is based on official Medicare sources. (Medicare)
The short answer in plain English
If you want the fastest practical answer before reading the full guide, here it is.
Start by asking whether you want to keep Original Medicare. If you do, Medicare says you can also shop for and buy supplemental coverage that helps pay your out-of-pocket costs. That supplemental coverage includes Medigap. If you don’t want Original Medicare and instead want a bundled private plan, you are usually comparing Medicare Advantage, not Medigap. (Medicare)
If you decide to keep Original Medicare, then choose Medigap in this order:
First, pick the plan letter that gives the protection level you want,
Then compare prices among companies selling that same letter,
Then check how the company prices the plan over time,
Then decide which insurer to choose. Medicare says same-letter plans have the same basic benefits, but premiums can vary widely between companies. (Medicare)
Also, do not ignore timing. Medicare says your 6-month Medigap Open Enrollment Period is usually the best time to buy because companies cannot deny you coverage for pre-existing health problems during that protected window. After it ends, you may not be able to buy a policy, or it may cost more. (Medicare)
That is the heart of the whole process.
First, know what Medigap is
Before you can choose Medigap well, you need to know what it actually is.
Medicare says Medicare Supplement Insurance (Medigap) is extra insurance you buy from a private insurance company to help pay your share of out-of-pocket costs in Original Medicare, like copayments, coinsurance, and deductibles. Medicare also says you can only buy Medigap if you have Original Medicare, which generally means Part A and Part B. (Medicare)
That means Medigap is not a replacement for Medicare. It is not a separate full health plan. It does not stand on its own. It works with Original Medicare. Medicare’s Medigap coverage page says Medigap plans help cover your share of costs for services that are covered by Original Medicare Part A and Part B. (Medicare)
This is important because many people start shopping with the wrong idea. They think “supplement” means “covers everything Medicare does not.” Medicare’s own wording is much narrower. Medigap mainly helps with cost-sharing for Medicare-covered hospital and medical services. (Medicare)
So when you choose Medigap, you are not choosing a whole new health system. You are choosing how much help you want with the bills that Original Medicare can leave behind.
Step 1: Decide whether you want Original Medicare or Medicare Advantage
This is the first real fork in the road.
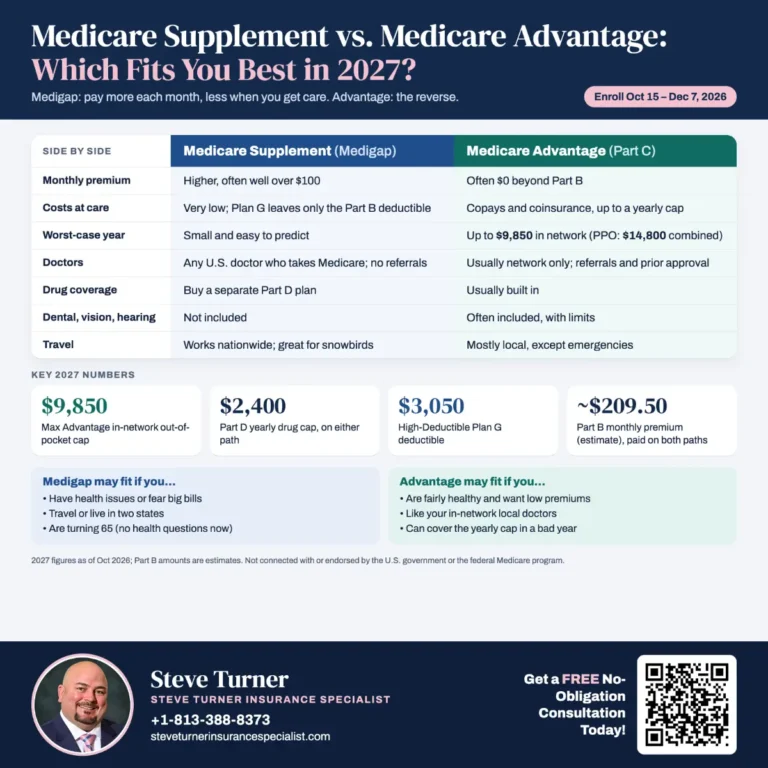
Medicare lets you get coverage in two main ways. One way is Original Medicare, where you keep Part A and Part B and can add a Medigap policy and a separate Part D drug plan. The other way is Medicare Advantage, also called Part C, which provides your Medicare coverage through a Medicare-approved private plan. (Medicare)
This matters because Medigap only works with Original Medicare. Medicare says a Medigap policy is different from a Medicare Advantage Plan. When you are getting started, you can either buy Medigap or enroll in a Medicare Advantage Plan, but you generally can’t have both in the normal way. (Medicare)
So the first Medigap decision is actually not about Medigap at all. It is about your bigger Medicare path.
If you want broad provider freedom and a supplement to reduce cost-sharing under Original Medicare, Medigap may be a good fit. Medicare says that with Original Medicare, you can use any doctor or hospital that takes Medicare anywhere in the U.S., and you can also shop for supplemental coverage that helps pay your out-of-pocket costs. (Medicare)
If you would rather have a single bundled plan that usually includes drug coverage and often extra benefits like dental, hearing, or vision, you may be comparing Medicare Advantage instead. Medicare says most Medicare Advantage plans include Part D drug coverage. (Medicare)
So before you choose Medigap, make sure it’s the right category for you.
Step 2: Understand what Medigap can and cannot do
Once you know you want Original Medicare, the next step is to clarify what Medigap is meant to do.
Medicare’s Medigap comparison chart shows that Medigap plans may help with benefits such as Part A coinsurance and hospital costs, Part B coinsurance or copayment, blood, Part A hospice cost-sharing, skilled nursing facility coinsurance, the Part A deductible, Part B excess charges in some plans, and foreign travel emergency costs in some plans. (Medicare)
That is why many people buy Medigap. It helps reduce financial surprises from approved Medicare hospital and medical services.
But Medicare also says Medigap generally does not cover long-term care, vision or dental services, hearing aids, eyeglasses, private-duty nursing, or prescription drugs in plans sold after 2005. (Medicare)
This matters when choosing a plan because your expectations must align with the product.
If your top goal is lowering hospital and outpatient medical cost-sharing, Medigap may be a strong fit. If your top goal is routine dental care, hearing aid coverage, or prescription drug coverage, Medigap alone will usually disappoint you. Medicare says if you want prescription drug coverage, you can join a separate Medicare drug plan, which is Part D. (Medicare)
So before comparing prices, be honest about what you are really shopping for. Medigap is best at smoothing out Medicare cost-sharing. It is not an all-purpose “everything else” plan.
Step 3: Pick the right plan letter first
This is where good Medigap shopping really begins.
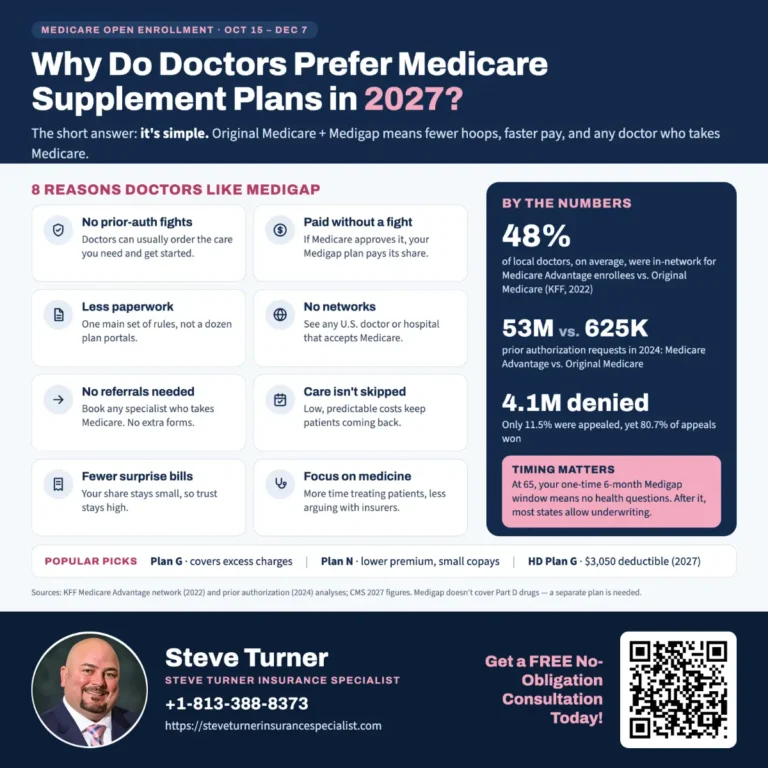
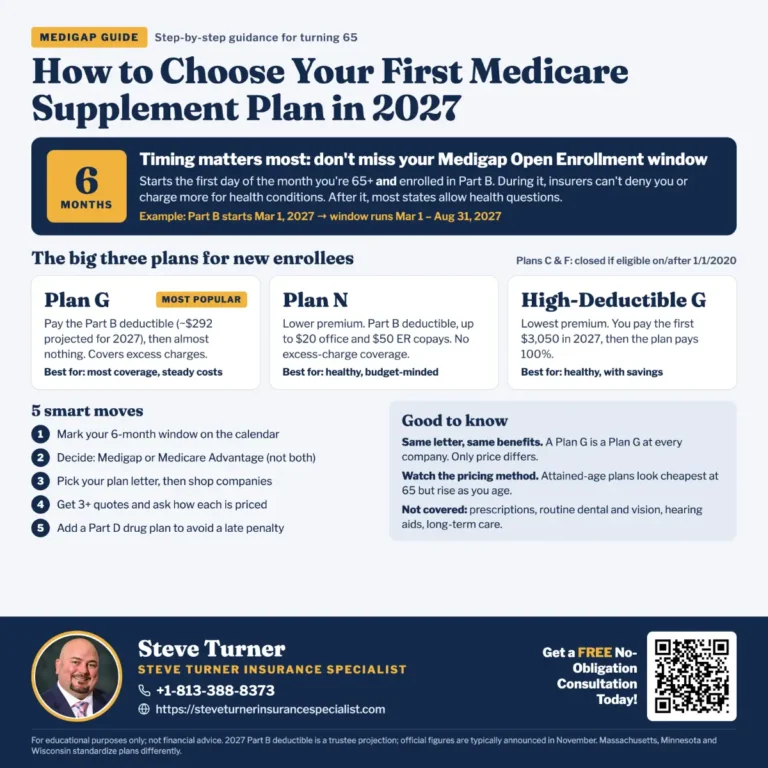
Medicare says that in most states, there are 10 Medigap plan types, designated by letters A–D, F, G, and K–N. It also says policies with the same letter offer the same basic benefits, no matter where you live or which insurance company sells them. Price is the only difference between the same-letter plans sold by different companies. (Medicare)
This means the smartest shopping order is:
Choose the letter first,
Then compare companies.
Many shoppers reverse that order. They start with the company or the premium ad they saw online. That is backward. The company only matters after you know which level of protection you want. Medicare’s own guidance says to compare plans with the same letter when looking at price. (Medicare)
So how do you choose the right letter?
Look at the official Medigap benefit chart and ask yourself how much risk you want to keep. Medicare’s chart shows that some plans fully cover more benefits, while Plans K and L cover some benefits only partially and have out-of-pocket limits. Some states offer high-deductible versions of Plans F and G. (Medicare)
In simple terms:
- Richer plans usually leave you with fewer surprise bills,
- leaner plans usually leave more cost-sharing with you,
- And high-deductible versions can lower monthly premiums but raise what you pay before the policy starts helping much. (Medicare)
So choosing the letter is really about making a trade-off between the monthly premium and future out-of-pocket risk.
Step 4: Compare same-letter plans across companies
Once you know the letter you want, then you compare insurers.
This is one of the most important Medigap rules, and Medicare states it very clearly: the benefits in each lettered plan are the same, no matter which insurance company sells it. The only difference between policies with the same plan letter sold by different companies is price, and premiums can vary widely. (Medicare)
That means if you decide you want Plan G, you should compare Plan G from several companies. Don’t compare Plan G from one company with Plan N from another unless you are still unsure about the letter itself.
This is where shoppers can save real money. Medicare says to compare plans with the same letter because premiums can vary widely for the same basic coverage. (Medicare)
That also means the brand name alone is not enough. A famous company is not automatically the cheapest or best value. Since the basic benefits are standardized by letter, your comparison should focus on:
- monthly premium,
- pricing method,
- company reputation and service,
- discounts,
- and how stable the pricing seems over time. Those are the practical differences Medicare’s cost guidance points toward. (Medicare)
So a smart Medigap shopper does not stop after finding the right plan letter. That is only half the job.
Step 5: Learn how Medigap pricing methods work
This is one of the most overlooked parts of choosing Medigap, and one of the most important.
Medicare’s official Choosing a Medigap Policy guide says insurance companies can price policies in three ways:
community-rated, issue-age-rated, and attained-age-rated. (Medicare)
These terms sound technical, but the ideas are not too hard.
With community-rated pricing, Medicare generally charges the same premium to everyone, regardless of age or gender. The premium may still go up due to inflation and other factors, but not because of your age. (Medicare)
With issue-age-rated pricing, Medicare says the premium is based on your age when you buy the policy. People who buy younger usually start with a lower premium, and the premium does not rise because they get older, though it can still rise due to inflation or other factors. (Medicare)
With attained-age-rated pricing, Medicare says the premium is based on your current age, so it goes up as you get older. Medicare also says these policies may be the least expensive at first, but can eventually become the most expensive. (Medicare)
This matters because the lowest premium you see today may not remain the lowest.
So when choosing Medigap, do not ask only:
“What is the price now?”
Also ask:
How is this policy priced, and how is that likely to affect me later? Medicare’s own guidance shows why that question matters. (Medicare)
Step 6: Think beyond premium and look at the total Medicare cost
Many shoppers focus only on the Medigap premium and stop there.
That is understandable, but incomplete.
Medicare says that when you buy a Medigap policy, you pay a monthly premium to the private insurance company. Medicare also says you still have to pay your monthly Medicare Part B premium, and Medicare does not pay your Medigap premium. Premium amounts typically increase each year. (Medicare)
Medicare’s 2026 handbook says the standard Part B premium for 2026 is $202.90 per month, and the Part B deductible is $283. (Medicare)
If you also want prescription drug coverage, Medicare says you can add a separate Part D plan to Original Medicare. That means many people on the Medigap path may pay:
- the Part B premium,
- the Medigap premium,
- and a separate Part D premium. (Medicare)
So when you choose Medigap, look at the full setup:
Part B + Medigap + Part D, not just the Medigap ad price.
That gives you a much more accurate picture of what your monthly Medicare plan will actually cost.
Step 7: Decide how much medical risk you want to keep
This is the heart of the Medigap decision.
You are not just buying a letter plan. You are deciding how much uncertainty you want in your future medical bills.
Medicare’s 2026 handbook says that with Original Medicare, you can use any doctor or hospital that accepts Medicare anywhere in the U.S. Still, it says you can shop for supplemental coverage to help pay your out-of-pocket costs, such as your 20% coinsurance. (Medicare)
That means Medigap appeals most to people who value:
- broad provider freedom,
- more predictable bills,
- and protection from repeated cost-sharing. (Medicare)
If you are comfortable with more risk and want a lower monthly premium, a limited-benefit plan or a high-deductible option may be more appealing. If you want lower cost-sharing when you use care, a richer letter plan may make more sense.
There is no single “best” plan for everyone. The right plan depends on your comfort with risk, your budget, and how often you expect to use medical care.
Step 8: Do not forget Part D
This step matters because many people focus so much on Medigap that they forget prescriptions.
Medicare says Medigap plans sold after 2005 do not include prescription drug coverage. If you want drug coverage and keep Original Medicare, you can join a separate Medicare drug plan, which is Part D. (Medicare)
This means a good Medigap decision usually goes hand in hand with a good Part D decision.
If you skip Part D because you assume your supplement covers drugs, Medicare warns that you may face a late enrollment penalty later if you go too long without creditable drug coverage and then try to enroll. (Medicare)
So when choosing Medigap, do not treat drug coverage as a side issue. It is part of the full Part D setup.
Step 9: Buy during your best enrollment window if possible
This is one of the most important practical tips in the whole article.
Medicare says your one-time Medigap Open Enrollment Period starts the first month you have Part B and are 65 or older. During this period, you can enroll in any Medigap policy, and the insurance company can’t deny you coverage due to pre-existing health problems. After this period, you may not be able to buy a Medigap policy, or it may cost more. Medicare also says this open enrollment period does not repeat every year. (Medicare)
That means timing matters when you buy Medigap.
Even a perfect letter plan can become harder or more expensive to get if you wait too long.
Medicare’s guide says that in most cases it makes sense to sign up for Part B and buy a Medigap policy when you are first eligible, though there are exceptions for people with employer coverage. (Medicare)
So if you are near your Medigap Open Enrollment Period, do not treat the choice casually. That is usually your strongest federal buying window.
Step 10: Compare company quality, not just company name
Medicare’s official materials focus heavily on benefits and price, but the company still matters.
Since the same-letter plans have the same basic benefits, your company comparison is really about things like:
- price,
- pricing method,
- stability,
- customer service,
- billing ease,
- and discounts. Medicare’s cost page directs you to compare companies and contact them for accurate quotes. (Medicare)
This means the “best” Medigap company is not simply the biggest one or the one with the most ads.
The best company for you is usually the one offering:
- the letter plan you want,
- at a price you can live with,
- under a pricing method you understand,
- With service you trust. (Medicare)
So choose the plan letter first, then judge the company on the practical things that remain.
Step 11: Use Medicare and SHIP help instead of guessing
You do not have to do all of this alone.
Medicare’s materials repeatedly point people toward official comparison tools and counseling help. The Choosing a Medigap Policy guide refers people to the State Health Insurance Assistance Program, or SHIP, for help. SHIP is free, state-based counseling for Medicare questions. (Medicare)
This matters because Medigap is one of those choices where a small misunderstanding can cost you money for years.
If you are unsure about:
- whether Medigap fits you,
- which letter plan to compare,
- how the pricing method works,
- or whether you should delay because of employer coverage,
Then, using official Medicare tools and SHIP help is a smart move. Medicare itself points people there for exactly that reason. (Medicare)
What a smart Medigap shopping process looks like
By now, you can probably see that choosing Medigap isn’t a single decision. It is a sequence.
A strong process looks like this:
First, decide whether you want Original Medicare or Medicare Advantage. Medicare says these are different paths. (Medicare)
Second, if you want Original Medicare, decide whether you want a supplement to reduce cost-sharing. Medicare says Medigap is designed for that purpose. (Medicare)
Third, compare Medigap plan letters using Medicare’s official chart to determine how much protection you want. (Medicare)
Fourth, compare several companies offering the same letter plan in your area, as prices can vary widely even for identical basic benefits. (Medicare)
Fifth, check the pricing method and ask how premiums may rise over time. Medicare’s guide explains why community-rated, issue-age-rated, and attained-age-rated pricing lead to different cost paths. (Medicare)
Sixth, remember the full cost picture: the Part B premium, the Medigap premium, and often the Part D premium, too. (Medicare)
Seventh, act during your best enrollment window if you can. Medicare says the 6-month Medigap Open Enrollment Period is usually the easiest and safest time to buy. (Medicare)
That is the buyer’s guide in one flow.
Common mistakes people make
One common mistake is choosing a Medigap plan before deciding whether they even want Original Medicare. Medicare says Medigap works only with Original Medicare, not as a regular add-on to Medicare Advantage. (Medicare)
Another mistake is comparing different letter plans across companies before they understand the differences in benefits between the letters. Medicare says the same letter offers the same basic benefits no matter which company sells it, so choose the letter first. (Medicare)
Another big mistake is shopping only on the monthly premium. Medicare’s guide shows that the pricing method can dramatically affect what you pay later, especially with attained-age-rated policies. (Medicare)
Another common mistake is forgetting the Part B premium and possible Part D premium when calculating total cost. Medicare says you still have to pay Part B, and if you want drug coverage with Original Medicare, you can add Part D. (Medicare)
Another mistake is expecting Medigap to cover things it usually does not, like most dental, vision, hearing aids, long-term care, or prescription drugs. Medicare says Medigap generally doesn’t cover those things. (Medicare)
And one of the biggest mistakes is waiting too long. Medicare says your Medigap Open Enrollment Period is one-time and doesn’t repeat every year. After it ends, buying may be harder or more expensive. (Medicare)
A simple checklist
If you want a very simple checklist before you buy, use this:
Do I want Original Medicare, not Medicare Advantage? Medicare says Medigap is for Original Medicare. (Medicare)
Do I understand what Medigap covers and what it usually does not cover? Medicare says it mainly helps with cost-sharing for Parts A and B. (Medicare)
Have I picked the right letter plan for my risk level? Medicare says letter plans differ in benefits. (Medicare)
Have I compared several companies selling the same letter plan? Medicare says prices can vary widely, even for the same coverage. (Medicare)
Do I know how the policy is priced over time? Medicare explains the three rating methods in its Medigap guide. (Medicare)
Have I included Part B and, if applicable, Part D in my total budget? Medicare says you still pay those separately. (Medicare)
Am I still in my best enrollment window? Medicare says your 6-month Medigap Open Enrollment Period is usually the best time to buy. (Medicare)
That checklist alone will help you make a far better decision than most people make.
Frequently asked questions
How do I choose the best Medicare Supplement plan?
Start by deciding whether you want Original Medicare. If you do, use Medicare’s official Medigap chart to compare plan letters first, then compare prices among companies selling the same letter. Medicare says same-letter plans have the same basic benefits, but premiums can vary widely. (Medicare)
Should I choose the cheapest Medigap premium?
Not automatically. Medicare’s guide shows that pricing method matters, and some policies that start cheaper may become more expensive later, especially attained-age-rated policies. (Medicare)
Is Plan G the same for every company?
The basic benefits are the same. Medicare says policies with the same letter offer the same basic benefits, no matter which company sells them. Price is the only difference between the same-letter plans sold by different companies. (Medicare)
Do I need Part D if I buy Medigap?
Usually, you should think about it separately. Medicare says Medigap plans sold after 2005 do not include prescription drug coverage, and if you want drug coverage, you can join a separate Part D plan. (Medicare)
When is the best time to buy Medigap?
Medicare says your best federal protection is usually during your one-time 6-month Medigap Open Enrollment Period, which starts the first month you have Part B and are 65 or older. (Medicare)
Can I buy Medigap later if I skip it now?
Maybe, but Medicare says after your Medigap Open Enrollment Period ends, you may not be able to buy a policy, or it may cost more. (Medicare)
Does Medigap cover dental, vision, and hearing?
Medicare says Medigap generally does not cover long-term care, vision or dental services, hearing aids, eyeglasses, private-duty nursing, or prescription drugs. (Medicare)
Final answer
So, how do you choose Medicare Supplemental Insurance?
You choose it by first deciding whether you want to keep Original Medicare, then choosing the right Medigap letter plan for your risk level, then comparing several companies selling that same letter in your area, and finally checking the pricing method, discounts, enrollment timing, and your full Medicare budget. Medicare says same-letter plans have the same basic benefits, but prices can vary widely. Medicare also says your 6-month Medigap Open Enrollment Period is usually your strongest federal buying window, and after it ends, buying may be harder or cost more. (Medicare)
The clearest plain-English answer is this:
Pick the right Medicare path first, pick the right Medigap letter second, and pick the right company third. Do not choose Medigap by premium alone.
That is the simplest way to make a strong decision.
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, LICENSED INSURANCE AGENT & BROKER
Questions? Call, text, or book a time below; I answer calls and emails 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
EMAIL ME: 24×7
OFFICE LOCATION
Address: 14502 N Dale Mabry Hwy, Suite 200, Tampa, FL 33618
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
MEDICARE SUPPLEMENT POSTS
INSURANCE OFFERINGS
How To Choose Medicare Supplemental Insurance?
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please get in touch with Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can use the Medicare Plan Finder at Medicare.gov to research plans available in your Florida county, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.
Steve Turner
Steve Turner, CLU®, REBC® Licensed Florida health insurance agent · License W333468
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals NABIP®, the preeminent organization for health insurance and employee benefits professionals, and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services. Steve also holds the prestigious Registered Employee Benefits Consultant® (REBC®) designation. Steve also holds the “Chartered Life Underwriter” designation (CLU®), a professional credential for individuals specializing in life insurance and estate planning. The American College of Financial Services confers it. For over 10 years, Steve has helped individuals, families, Medicare beneficiaries, and small businesses find the right coverage to meet their needs. Steve has earned 180+ Google reviews from happy clients.
Steve Turner is a licensed agent appointed by Florida Blue.