

How Much Does Medicare Advantage Cost in 2027? Premiums, Copays and Limits
Reviewed by Steve Turner, CLU, REBC · Florida License W333468 · NPN 18030539 · November 2026
Date Published: 2026-07-05
Updated: 2026-11-21
Most Medicare Advantage plans in Florida have a $0 monthly premium, but Medicare Advantage isn’t free. In 2027, most people will still pay the Part B premium of $209.40 a month, plus copays and coinsurance when you get care. Those costs are capped each year: plans can’t make you pay more than $9,850 for in-network medical care in 2027, and many set a much lower limit. Drug costs have their own $2,400 cap. In a light year, many people pay about $2,700, including Part B. In a bad year, it can be several thousand more. Here’s how each cost works for Medicare Advantage plans in Tampa, with real examples.
Key takeaways
- Part B premium: $209.40 a month in 2027 for most people ($2,512.80 a year). You pay it with any Medicare Advantage plan, unless Medicaid or a Medicare Savings Program pays it for you.
- Plan premium: most Florida plans are $0. The national average is about $12 a month for 2027.
- Copays: you pay set amounts for visits, hospital stays and tests, such as $0 for primary care and $30–$50 for a specialist.
- Yearly cap: in-network medical costs are capped at up to $9,850 in 2027 (up to $14,800 in and out of network combined). Drug costs are capped at $2,400.
- Total cost depends on your health. Compare plans on a light year and a bad year, not just the premium.
The costs of Medicare Advantage in 2027
| Cost | What it is | 2027 amount |
|---|---|---|
| Part B premium | What you pay Medicare for Part B; you keep paying it with Medicare Advantage | $209.40/month for most people; higher if your income is above certain limits |
| Plan premium | What the plan charges each month, if anything | Often $0 in Florida; varies by plan |
| Medical deductible | What you pay before the plan starts paying for some services | Many plans have none; some do |
| Copays | A set amount for a service | For example, $0–$15 primary care, $30–$50 specialist, $250–$400 per day for the first several days of a hospital stay |
| Coinsurance | A percentage of the cost, often for equipment, some drugs and Part B drugs like chemotherapy | Often 20% |
| Drug costs | Deductible, copays and coinsurance for prescriptions | Drug deductible up to $700; drug costs capped at $2,400 |
| Out-of-pocket limit | The most you pay for covered medical care in a year | Up to $9,850 in-network ($14,800 combined); many plans set less |
Copay examples are typical ranges, not quotes. I compare actual plans in your ZIP code.
Plan premiums: why most are $0
Medicare pays each Medicare Advantage plan a monthly amount to cover your care. In competitive markets like Tampa Bay, plans use some of that money to bring premiums down to $0. About 9 in 10 Florida Medicare Advantage plans (not counting Special Needs Plans) have a $0 premium for 2027. Nationally, CMS projects the average premium will drop to about $12 a month, down from $14.37 in 2026.
Plans that charge a premium usually offer something in return, such as a lower out-of-pocket limit, lower copays, a broader PPO network, or richer dental coverage.
A $0 premium is not the same as free. It just means the plan doesn’t add a monthly charge. You still pay the Part B premium and your share of care costs.
The Part B premium you still pay
Everyone with Medicare Advantage must keep Part B and pay its premium:
- 2027 standard premium: $209.40 a month, up from $202.90 in 2026
- Higher earners pay an income-related surcharge (IRMAA) on Part B, and on drug coverage if their plan includes it
- A Part B giveback plan pays part of this premium for you. See Medicare Advantage give money back
- If Medicaid or a Medicare Savings Program pays your Part B premium, you don’t pay it at all (see Medicare & Medicaid help)
Copays, coinsurance and deductibles
These are the costs you pay when you get care. Every plan sets its own, so two $0-premium plans can cost very different amounts to use. Look closely at:
- Hospital stays: usually a daily copay for the first several days, then $0
- Specialist visits: the copay you’ll pay most often if you have a chronic condition
- Imaging: MRIs and CT scans often have a separate copay of $100 to $400
- Outpatient surgery: often a copay of a few hundred dollars
- Skilled nursing: often $0 for the first 20 days, then a daily copay
- Part B drugs: drugs given in a doctor’s office, like chemotherapy or infusions, often cost 20% coinsurance
Drug costs
Most Medicare Advantage plans include Part D drug coverage. For 2027:
- Drug deductible: up to $700, though many plans charge less or none, and some waive it for lower-cost generics
- Drug cap: once you’ve paid $2,400 for covered drugs, you pay nothing more for them that year
- Insulin: no more than $35 a month for covered insulins
- You can spread costs out with the Medicare Prescription Payment Plan, which turns big pharmacy bills into monthly payments
Drug costs depend on whether your drugs are on the plan’s formulary, which tier they’re on, and which pharmacy you use. Always enter your drugs in Medicare Plan Finder. See Medicare Part D for more.
The out-of-pocket limit: your protection in a bad year
The out-of-pocket limit (also called the MOOP) is the most you’ll pay in a year for covered Part A and Part B services. Once you reach it, the plan pays 100% for the rest of the year.
- 2027 federal maximum: $9,850 for in-network care, and $14,800 for in- and out-of-network care combined in PPO plans
- Many plans set lower limits, but average limits are rising for 2027
- What doesn’t count: your premiums, drug costs (they have their own $2,400 cap), and extra benefits like dental
Original Medicare has no out-of-pocket limit, which is why many people on Original Medicare add a Medicare Supplement plan.
What Medicare Advantage costs in real life
Here’s what one person might pay in a year with a $0-premium plan and a $5,900 in-network limit. These are example copays, not a specific plan.
| Light year | Heavy year | Worst case | |
|---|---|---|---|
| Part B premium | $2,512.80 | $2,512.80 | $2,512.80 |
| Plan premium | $0 | $0 | $0 |
| Doctor visits | 4 primary care ($0), 2 specialist ($40 each) = $80 | 12 specialist visits ($40 each) = $480 | — |
| Hospital, tests and therapy | $0 | 5-day hospital stay ($350/day) = $1,750; 1 MRI = $250; outpatient surgery = $500; 12 physical therapy visits ($30 each) = $360 | Reaches the $5,900 limit |
| Prescriptions | 3 generics = $120 | Brand-name drugs = $1,200 | Reaches the $2,400 cap |
| Total for the year | $2,712.80 | $7,052.80 | $10,812.80 |
If a plan uses the federal maximum limit of $9,850, the worst case rises to $14,762.80. That’s why the out-of-pocket limit matters as much as the premium, especially if you have a chronic condition or expect surgery.
What makes one plan cost more than another
- HMO or PPO: PPOs let you see out-of-network providers, but they often have higher copays or premiums.
- Network: a plan that includes your doctors in-network will cost less to use than one that doesn’t.
- Your county: plan options and prices vary by county, even within Tampa Bay.
- Extras: richer dental, vision, or hearing benefits can come with a premium.
- Drug coverage: your drugs’ tiers can make one plan hundreds of dollars cheaper than another.
Help paying Medicare Advantage costs
If your income and savings are limited, you may qualify for:
- Extra Help, which lowers drug costs
- A Medicare Savings Program, which can pay your Part B premium
- Medicaid, and a Special Needs Plan (D-SNP) designed for people with Medicare and Medicaid, often with $0 copays
See Medicare & Medicaid help to check whether you qualify.
How to estimate your own costs
- Start with $2,512.80 for the 2027 Part B premium, unless you get help paying it or have a giveback.
- Add the plan premium times 12.
- Estimate your copays using the plan’s Summary of Benefits and the care you usually use.
- Add your drug costs from Medicare Plan Finder.
- Check the worst case: Part B, plus premiums, plus the out-of-pocket limit, plus the drug cap.
Or let me do it for you, side by side for every plan in your ZIP code.
Medicare Advantage costs in Tampa
Tampa Bay is one of Florida’s most competitive Medicare Advantage markets, so most people can find a $0-premium plan with drug coverage. The biggest differences are in out-of-pocket limits, specialist and hospital copays, and which health systems are in network: Tampa General, BayCare, AdventHealth, HCA Florida, and Moffitt Cancer Center. Several plans changed their costs for 2027, so if you’re already enrolled, read your Annual Notice of Change before December 7. See 2027 Medicare Advantage changes.
How I help
- Compare the total yearly cost of every plan in your ZIP code for a light year and a bad year.
- Check your doctors, hospitals, and prescriptions against each plan.
- Look for savings you may qualify for, like a Part B giveback, Extra Help, or a Medicare Savings Program.
- I’ll enroll you and help with billing questions afterward.
My help costs you nothing. Premiums are the same whether you enroll through me or directly with the plan.
Medicare Advantage cost FAQs
How much does Medicare Advantage cost per month?
Many plans have a $0 monthly premium, but you also pay the Part B premium, which is $209.40 a month for most people in 2027. Some plans charge a premium on top of that.
Are Medicare Advantage plans free?
No. A $0-premium plan doesn’t add a monthly charge, but you still pay the Part B premium and copays or coinsurance when you get care, up to the plan’s yearly limit.
What does a Medicare Advantage plan cost on average?
CMS projects the average Medicare Advantage premium will be about $12 a month in 2027. Most Florida plans have a $0 premium. Your total cost also includes Part B and your copays.
What is the Medicare Advantage out-of-pocket maximum for 2027?
Plans can set it up to $9,850 for in-network care or $14,800 combined for in- and out-of-network care. Many plans set lower limits. Drug costs have a separate cap of $2,400.
Do I still pay the Part B premium with Medicare Advantage?
Yes, unless Medicaid or a Medicare Savings Program pays it for you. Some plans include a Part B giveback that lowers it.
Is Medicare Advantage cheaper than a Medicare Supplement?
Usually, Medicare Advantage has lower monthly premiums, but not always a lower total cost. Medicare Advantage often has lower premiums and higher costs when you use care. A Medicare Supplement has a higher premium and very low costs when you use care. See Medigap vs. Medicare Advantage.
Why are some Medicare Advantage plans more expensive than others?
Plans with a premium often have lower copays, a lower out-of-pocket limit, a broader network, or richer extra benefits. A $0-premium plan can cost more overall if you need a lot of care.
Talk with Steve
Want to know what a Medicare Advantage plan would really cost you in 2027? Call me at (813) 388-8373 or book a free review.
Related: Medicare Advantage plans in Tampa · What does Medicare Advantage cover? · Medicare vs. Medicare Advantage · Medigap vs. Medicare Advantage · Medicare Advantage give money back
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, LICENSED INSURANCE AGENT & BROKER
Questions? Call, text, or book a time below; I answer calls and emails 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
EMAIL STEVE
OFFICE LOCATION
Address: 14502 N Dale Mabry Hwy, Suite 200, Tampa, FL 33618
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
More on Medicare Advantage
-
Does Medicare Advantage Insurance Cover Long-Term Care?
By Steve Turner
• 2026-06-17
Does Medicare Advantage cover long-term care? Usually not. See what Part C pays for (rehab, home health, hospice) and what covers nursing home costs instead. -

Medigap vs. Medicare Advantage
By Kenneth Young
• 2026-11-20
Medigap or Medicare Advantage? Compare 2027 premiums, the $9,850 out-of-pocket limit, networks and Florida’s switching rules, with real scenarios for Tampa retirees. -
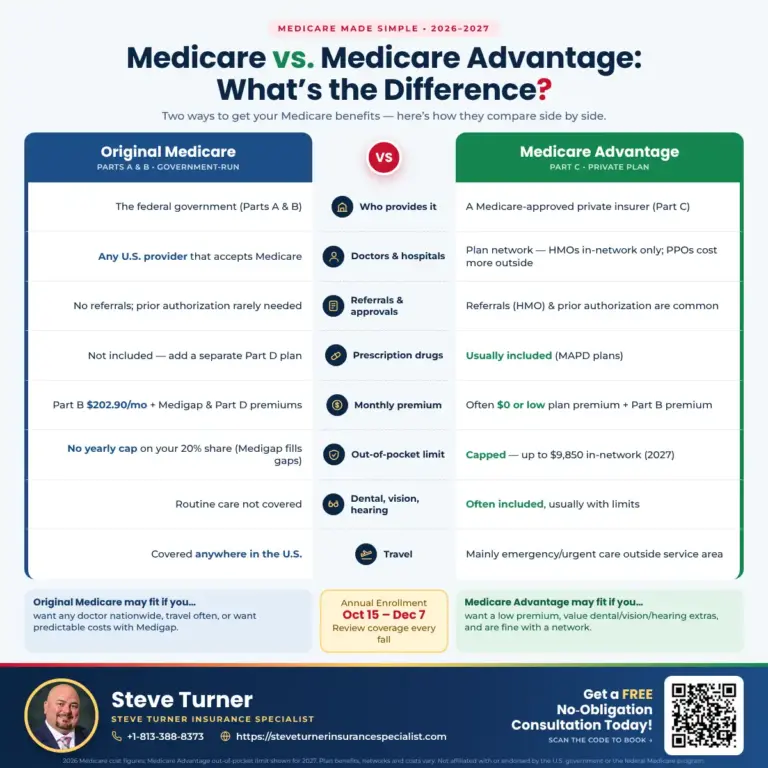
Medicare vs Medicare Advantage in Florida
By Steve Turner
• 2025-06-02
Medicare Advantage is still Medicare, delivered differently. See how Original Medicare and Medicare Advantage compare on costs, networks and 2027 limits. -
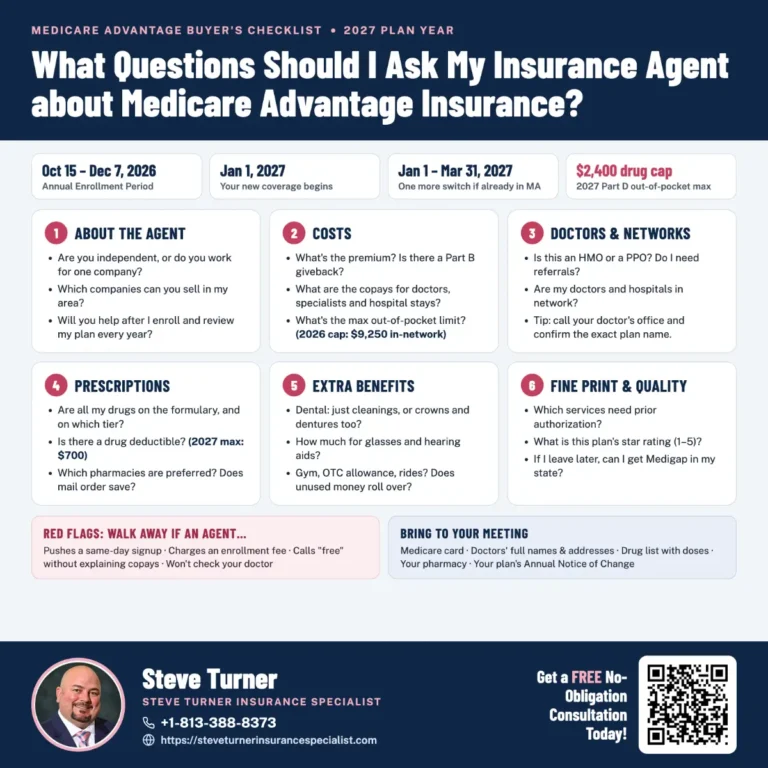
What to Ask Your Medicare Advantage Agent Before Enrolling
By Steve Turner
• 2026-10-13
Shopping for Medicare Advantage? Here are the key questions to ask your insurance agent about costs, doctors, drugs, and benefits before December 7, 2026. -

What Does Medicare Advantage Cover? What’s Included, and What Isn’t, in 2027
By Steve Turner
• 2026-07-01
Medicare Advantage covers all Part A and Part B services except hospice, usually adds drug coverage and extras, and has real limits. Here’s what’s covered and what isn’t in 2027. -
Medicare Advantage 2027 FAQ: 150+ Answers for Florida
By Steve Turner
• 2025-07-10
2027 Medicare Advantage answers from a licensed Florida agent: $2,400 drug cap, $9,850 MOOP, Florida plan cuts, GLP-1 coverage, and how to compare plans.
Medicare plan availability differs by state and county. Steve Turner is licensed in AL, CO, FL, GA, NC, SC, TN, and TX.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
MEDICARE DISCLAIMER
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
Steve Turner
Steve Turner, CLU®, REBC® is licensed in AL, CO, FL, GA, NC, SC, TN, and TX · NPN 18030539 · Florida License W333468
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals NABIP®. Steve holds the Registered Employee Benefits Consultant® (REBC®) designation. Steve also holds the “Chartered Life Underwriter” designation (CLU®), a professional credential for individuals specializing in life insurance and estate planning, conferred by the American College of Financial Services. Since 2016 (over 10 years), Steve has helped individuals, families, Medicare beneficiaries, and small businesses find the right coverage to meet their needs. Steve has earned 180+ Google reviews from happy clients.
Steve Turner is a licensed agent appointed by Florida Blue in Florida.