
Will Disability Insurance Cover My Surgery Recovery?

Will Disability Insurance Cover My Surgery Recovery? Can I Get Paid During Planned Medical Leave?
The short answer: usually yes
Yes, disability insurance will usually cover your surgery recovery. It pays when a doctor says you can’t do your job while you heal, and the surgery was needed for your health.
But there are rules. I wrote this guide to explain them in plain words, because the fine print trips up a lot of people. Here is what decides if you get paid:
- Why you had the surgery: surgery you need for your health is usually covered. Surgery only to change your looks usually is not.
- How long you are out. Every plan has a waiting period. If you heal before it ends, you get nothing.
- When your coverage started, if you signed up after the health problem began, the plan may say no.
- What kind of plan you have. A work plan, a plan you bought yourself, and a state plan all work differently.
One more thing before we start. Disability insurance does not pay your hospital bill. It replaces part of your paycheck. I’ll explain the difference next.
This article is general information, not legal or financial advice. Your own policy has the final word.
What is disability insurance?
Disability insurance is paycheck insurance. If you get sick or hurt and can’t work, it sends you money every week or month.
A lot of people mix it up with health insurance. Here is how I keep the two straight:
| Health insurance | Disability insurance | |
|---|---|---|
| What it pays for | Doctors, the hospital, medicine | Part of your lost paycheck |
| Who gets the money | The hospital and doctors | You |
| What the money is for | Medical bills | Rent, food, gas, anything you need |
So after surgery, you may use both. Health insurance helps with the surgery bill. Disability insurance helps with the bills at home while you can’t work.
The word “disability” scares some people. In insurance, it just means you can’t do your job for a while because of a health problem. You don’t have to be hurt forever. Six weeks of healing after knee surgery can count.
Short-term vs. long-term disability insurance for surgery
There are two main kinds of disability insurance. Most surgery recoveries fall under short-term.
| Short-term disability | Long-term disability | |
|---|---|---|
| Wait before pay starts | About 7 to 14 days | About 90 to 180 days |
| How much it pays | About 40% to 70% of your pay | About 50% to 70% of your pay |
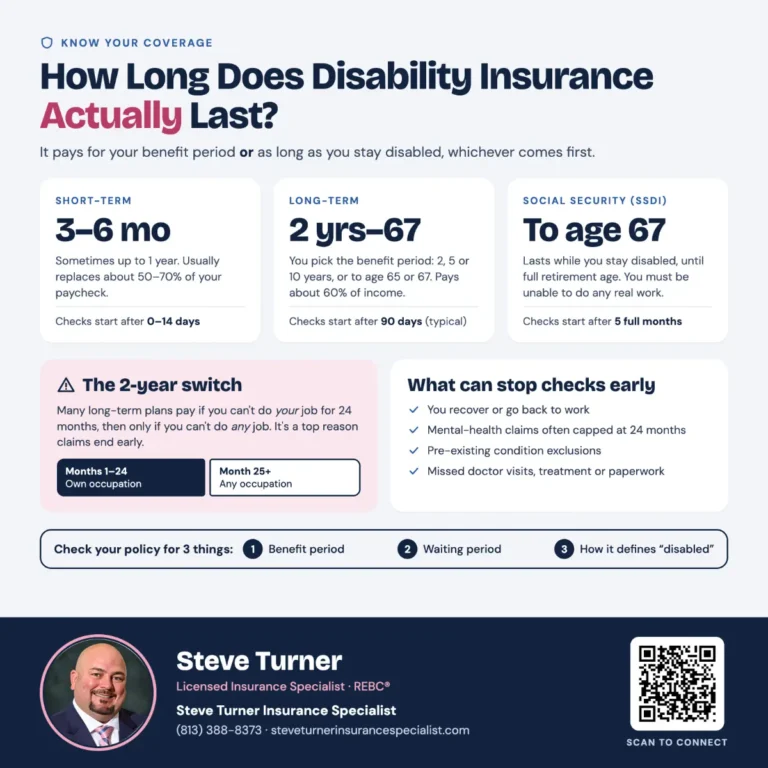
| How long it pays | About 3 to 6 months, sometimes a year | Years, sometimes until you retire |
| Best fit | Most surgeries | Big surgeries with long, hard recoveries |
These are common ranges. Your plan may differ, so check your own documents.
Here is how the two work together. Say you have back surgery, and healing takes much longer than planned. Short-term disability pays for the first few months. If you still can’t work when it runs out, long-term disability can take over. Many jobs set them up so one ends right when the other begins.
What if you only have long-term disability insurance? Then a normal surgery may not be covered at all. A six-week recovery ends long before a 90-day wait does.
9 surgeries disability insurance usually covers
Plans don’t keep a list of “approved” surgeries. They ask two simple questions. Did a doctor say you needed this surgery? And can you do your job while you heal?
These common surgeries usually pass that test:
- Joint surgery, like a knee or hip replacement or a shoulder repair
- Back and neck surgery
- Heart surgery, like a bypass or valve repair
- Cancer surgery, like removing a tumor
- Belly surgery, like taking out a gallbladder or appendix, or fixing a hernia
- C-sections. Most short-term plans treat healing from childbirth as a covered disability.
- Hysterectomy
- Surgery after an accident, like fixing a broken bone (as long as it didn’t happen at work)
- Hand and wrist surgery, like carpal tunnel release
Your job matters as much as your surgery. If you sit at a desk, you might return to work two weeks after knee surgery. If you lift boxes all day, the same surgery could keep you out for three months. The plan looks at what your job asks your body to do.
That is why two people with the same surgery can get very different answers.
6 times disability insurance won’t cover surgery recovery
This is the part I most want you to read before your surgery date. These are the six most common reasons a claim gets turned down.
- The surgery was only for looks. A facelift or tummy tuck that you chose to change how you look is usually not covered. Surgery to rebuild your body after cancer, an accident, or a congenital disability is different. That usually is covered.
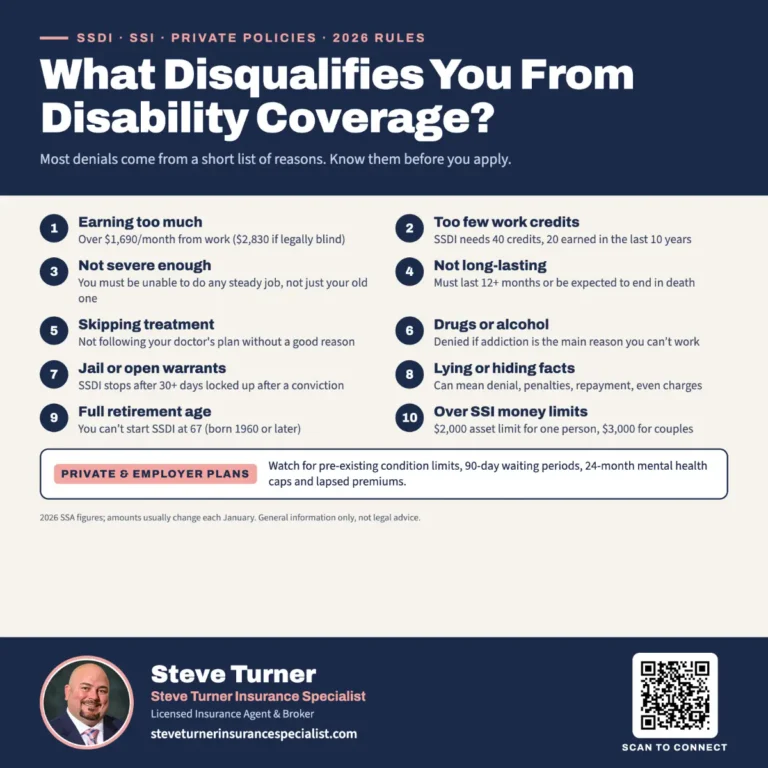
- The problem started before your coverage did. This is called a pre-existing condition, and it is the big one. Many plans look back 3 to 12 months before your coverage began. If you saw a doctor or took medicine for the problem in that time, the plan may not pay for it during your first year.
- You heal before the waiting period ends. If your plan has a 14-day wait and you return to work in 10 days, you get nothing.
- You got hurt at work. That is a job for workers’ compensation, not disability insurance.
- You can still do your job. If your doctor says you can work, the plan won’t pay, even if you are sore and tired.
- Your coverage hadn’t started yet. New workers often wait 30 to 90 days before a work plan kicks in. Surgery during that time is not covered.
Here is an example of number two. You start a new job in March. Your knee has hurt since January, and you saw a doctor about it then. In June, you have knee surgery. The plan may say no, because the knee problem came first.
If you have had your coverage for more than a year, this rule usually can’t hurt you.
The disability insurance waiting period
Every plan makes you wait before it pays. Insurance people call this the “elimination period.” I call it the waiting period.
The wait starts on the first day you can’t work. You get no money from the plan for those days. For short-term disability, the wait is often 7 or 14 days.
Here is what that looks like with made-up but normal numbers:
| Time off work | Waiting period | Weeks the plan pays |
|---|---|---|
| 1 week | 7 days | 0 |
| 3 weeks | 7 days | 2 |
| 10 weeks | 14 days | 8 |
So for a quick surgery, disability insurance may pay little or nothing. For a long recovery, it helps a lot.
Three tips for getting through the wait:
- Save your sick days. Many people use sick time or vacation days to cover the waiting period.
- Ask about your paid time-off rules. Some bosses make you use it before disability pay starts.
- Look for a hospital rule. Some plans waive the waiting period if you are admitted to a hospital. Check your plan for this.
If you know your surgery date, count the days now. That will tell you how many unpaid days to plan for.
How much does disability insurance pay after surgery?
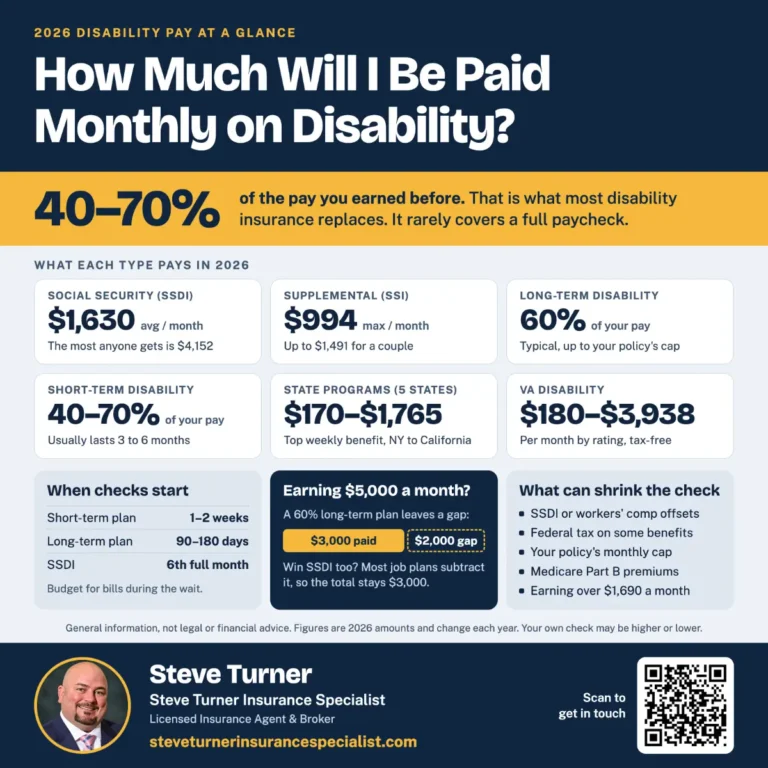
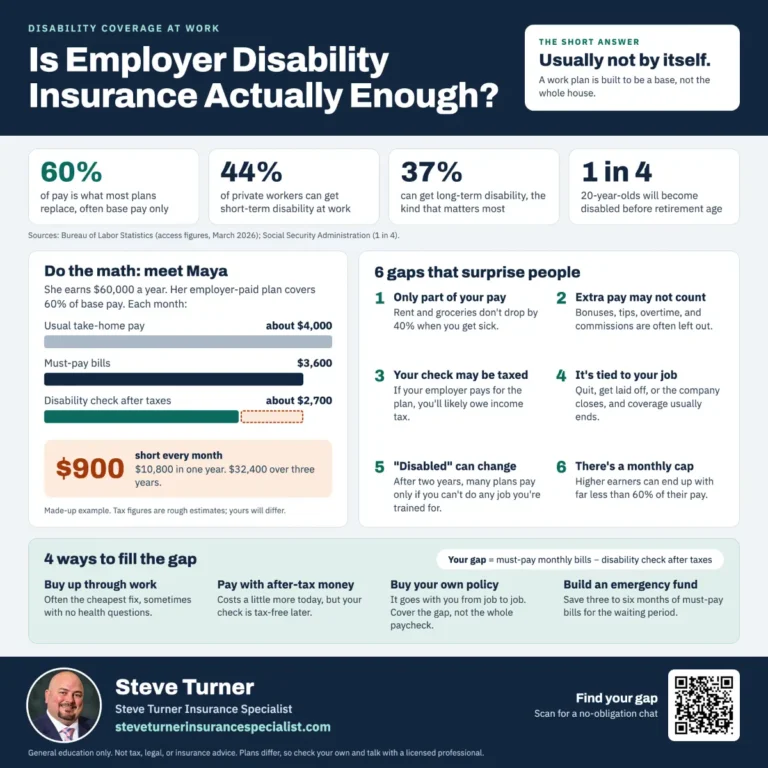
Disability insurance never pays your full paycheck. Most plans pay about 60% of your normal pay, up to a top weekly amount.
Let me walk through an example. Say you earn $1,000 a week. Your plan pays 60% after a 14-day wait. You are out of work for 8 weeks.
- Weeks 1 and 2: $0 (the waiting period)
- Weeks 3 through 8: $600 a week, or $3,600 total
- What you would have earned at work: $8,000
So you bring in less than half of your normal pay for those 8 weeks. That surprises people. It is better to know now than to find out later.
Will I owe taxes on it? It depends on who paid for the plan. If your boss paid the cost, the money you get is usually taxed. If you paid with money that was already taxed, it usually is not.
How long will the payments last? Only as long as your doctor says you can’t work, up to your plan’s limit. If your plan lasts up to 26 weeks but your doctor clears you at week 6, payments stop at week 6.
If you need more time to heal, your doctor must send new notes explaining why. Without those notes, the payments stop.
A plan from work vs. a plan you bought yourself
Where your coverage comes from changes a few things; here is what I would want to know about each kind.
A plan from your job:
- It is often cheap or free, and you usually don’t have to answer health questions to join.
- It has a pre-existing condition rule, and new workers have to wait before it starts.
- It usually ends when you leave the job.
A plan you bought on your own:
- You answer health questions first. The company may leave out a health problem it already knows about.
- It goes with you from job to job.
- You paid for it with your own money, so the payments are usually tax-free.
A state plan:
- If you work in a state that has one, you are most likely already in it. I cover these next.
You can have more than one plan. But you usually can’t get paid twice for the same week. A work plan often lowers its payment by the amount a state plan pays you.
State disability insurance and paid medical leave
Some states run their own plans. If you work in one, you may be covered even if your job offers nothing.
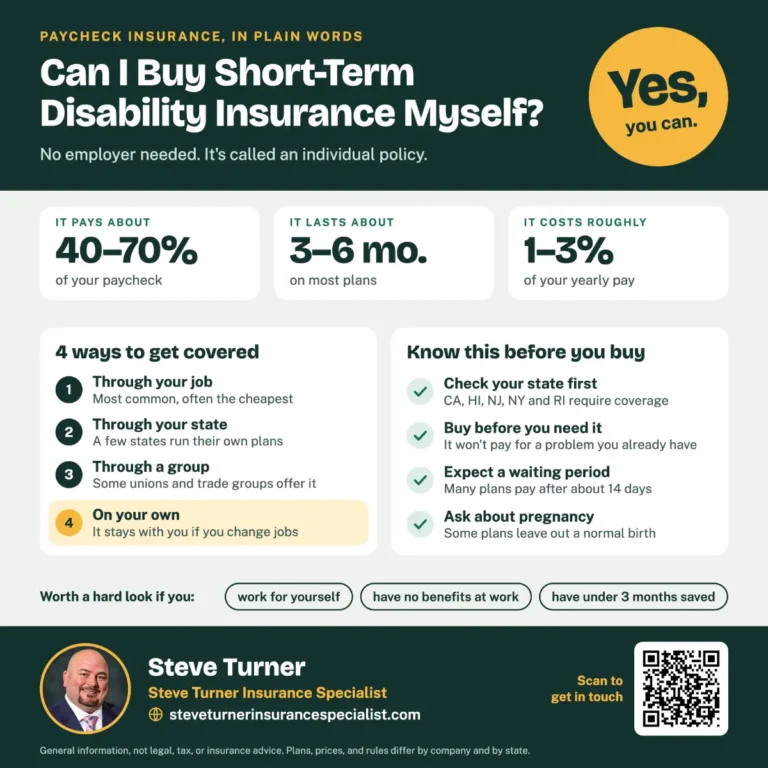
Five states make short-term disability coverage the law:
- California
- Hawaii
- New Jersey
- New York
- Rhode Island
Puerto Rico also has a similar plan.
California is a good example. In 2026, its plan pays 70% to 90% of your wages, up to $1,765 a week, for up to 52 weeks. There is a 7-day wait first. You can check the numbers on the California EDD website.
Other places have paid medical leave programs. These can also pay you while you heal from surgery:
- Colorado
- Connecticut
- Delaware
- Maine
- Massachusetts
- Minnesota
- Oregon
- Washington state
- Washington, D.C.
Delaware, Maine, and Minnesota started paying benefits in 2026. Maryland’s program is set to start paying in 2028.
Each state has its own rules for how much you get and how long it lasts. To find yours, search your state’s name plus “paid medical leave.”
If you live anywhere else, like Florida or Texas, there is no state plan. You need coverage from your job or a plan you buy on your own.
Will Social Security disability cover surgery recovery?
Rarely. This one confuses a lot of people, so I want to be clear.
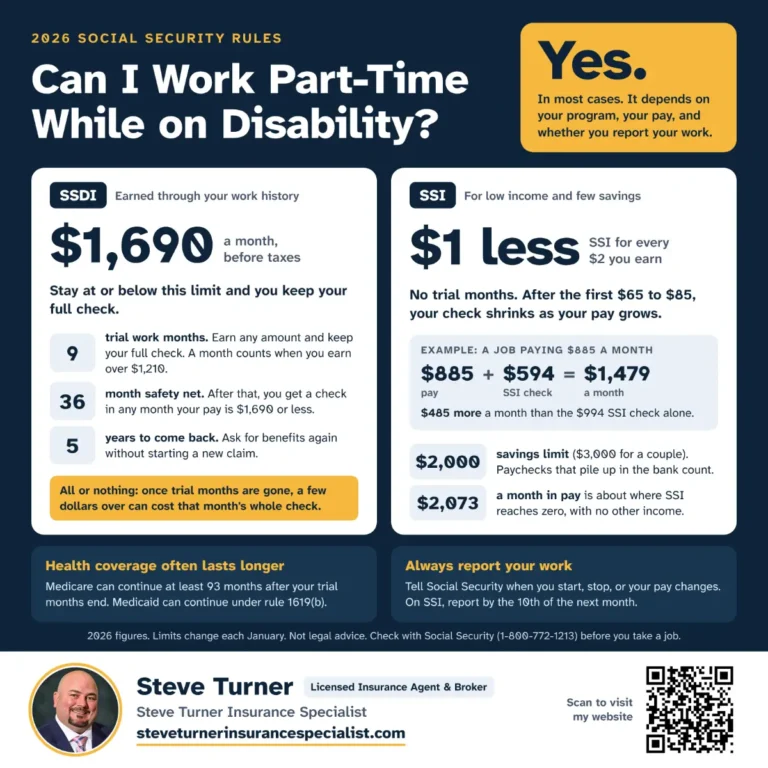
Social Security Disability Insurance (SSDI) is for long, serious health problems. It does not pay for short-term disability. Here are the two rules that rule out most surgeries:
- Your health problem must last, or be expected to last, at least 12 months.
- There is a five-month waiting period. The first payment comes in the sixth full month.
A normal surgery recovery is over long before then. You can read the rules on the Social Security website.
The one time SSDI may fit is when surgery is part of a much bigger health problem that will keep you out of work for a year or more.
How to file a disability claim for surgery in 8 steps
If your surgery is planned, you have a big head start. You can do most of the work before you ever get to the hospital. Here is the order I would do it in.
- Read your plan. Ask your HR office for the plan papers. Look for four things: the waiting period, the percentage of pay, the maximum number of weeks it pays, and the pre-existing condition rule.
- Tell your boss early. For planned surgery, try to give at least 30 days’ notice.
- Get the claim forms. There are usually three parts. One is for you, one is for your job, and one is for your doctor.
- Give the doctor’s part to your surgeon before surgery. Bring it to your pre-surgery visit. Doctor’s offices are busy, and this form is where most delays happen.
- Check what the doctor wrote. It should list your surgery date, the day you must stop working, the day you may return, and what you can’t do, like lifting, standing, or driving.
- File on time. Some plans give you as little as 30 days. Send the forms as soon as your plan allows.
- Keep copies of everything. Write down the name and date each time you call the insurance company.
- Go to every follow-up visit. The plan can ask for proof that you are still healing. Your visit notes are that proof.
What if your surgery was an emergency? Then start at step one as soon as you are able. A family member can call HR and get the forms for you.
7 mistakes that delay or sink a claim
Most claim problems come from small slips, not big ones. Watch out for these:
- Reading the plan after surgery. By then it is too late to plan for the waiting period.
- Thinking the doctor’s office sent the form. Call and check. Then check again.
- A vague doctor’s note. “Patient had surgery” is not enough. The note must say what you can’t do at your job.
- Skipping follow-up visits. No visits means no proof.
- Working on the side. If you do any paid work while you collect, tell the insurance company first.
- Posting the wrong picture. Insurance companies can look at social media. A photo of you hiking while you are “unable to walk” can end a claim.
- Missing a deadline. This applies to filings and appeals.
None of these are hard to avoid. You have to know about them in advance.
What to do if your disability claim is denied
A “no” is not always the end. Many denials happen because a paper is missing, and you can fix that.
- Read the denial letter slowly. It must tell you why they said no and how long you have to appeal.
- Ask for your claim file. For a work plan, you can request a free copy of the documents they used.
- Fix the gap. If the letter says you didn’t provide enough medical proof, ask your surgeon for a longer, clearer note.
- Appeal in writing, on time. Most work plans give you 180 days. Don’t cut it close.
- Get help if you need it. Your state’s insurance office takes complaints. For a work plan, the U.S. Department of Labor can help. A disability lawyer is worth a call for a large claim.
State plans have their own appeal steps. The denial letter will list them.
5 other ways to cover your pay during surgery recovery
Maybe you have no disability insurance. Or maybe 60% of your pay is not enough. Here are a few other things to consider.
- Sick days and vacation days. These pay 100% of your wages. Use them for the waiting period.
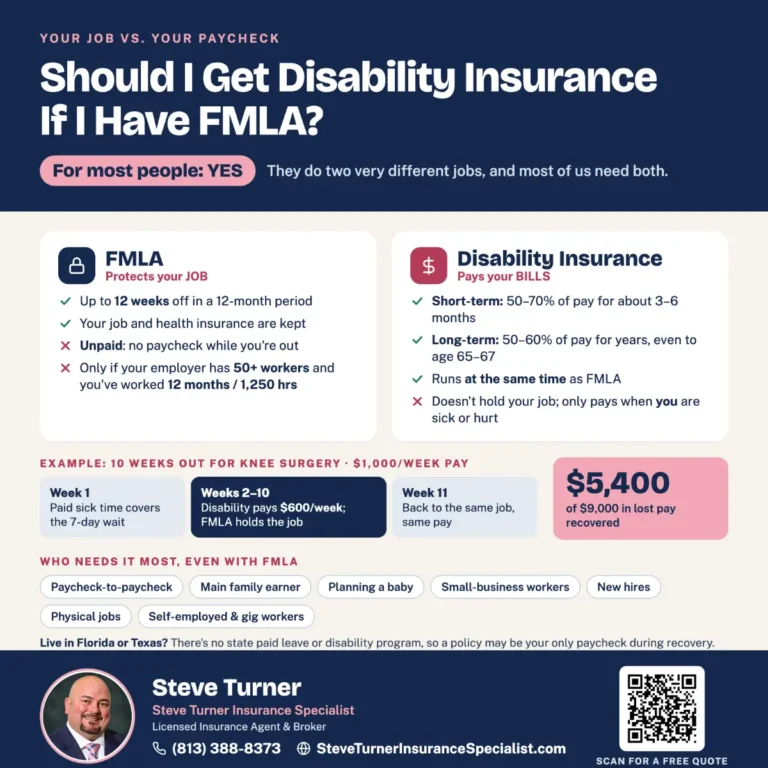
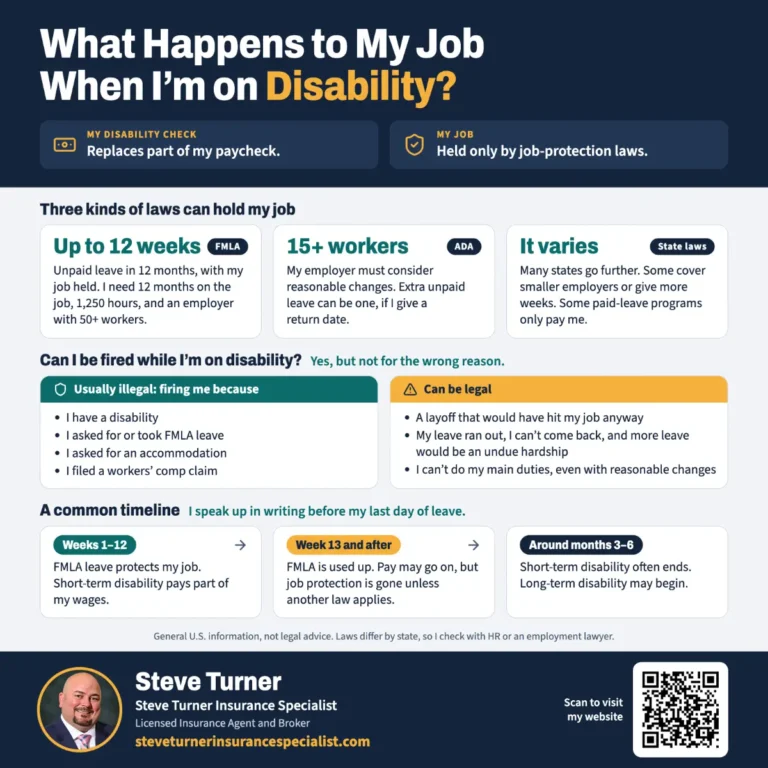
- FMLA leave. The Family and Medical Leave Act gives up to 12 weeks off. It is unpaid, but it protects your job and keeps your health insurance going. You must have worked there for 12 months and 1,250 hours, at a company with 50 or more workers.
- Workers’ compensation. If you need surgery because of a work injury, start here.
- Extra policies. Hospital, accident, or critical illness plans pay cash for certain events.
- Savings. Even a few hundred dollars set aside before surgery helps.
Here is something many people miss. Disability insurance pays you, but it does not save your job. FMLA saves your job, but it does not pay you. That is why many people use both at the same time.
Questions people ask about disability insurance and surgery
Does short-term disability cover elective surgery?
Often, yes. “Elective” means the surgery was planned ahead of time. A planned knee replacement that your doctor says you need is usually covered. Surgery only for looks is usually not.
Can I buy disability insurance right before my surgery?
You can buy it, but it probably won’t pay for that surgery. New plans often leave out health problems you already had. Buy coverage while you are healthy, not after you get a surgery date.
Does disability insurance cover a C-section?
Most short-term plans do. A common amount is about six weeks for a regular birth and eight weeks for a C-section, minus the waiting period.
What if I have problems after surgery and need more time?
You can usually get more weeks, up to your plan’s limit. Your doctor must send notes that explain what went wrong and why you still can’t work.
Can I lose my job while I’m on disability?
Disability insurance alone does not protect your job. FMLA and some state laws do. Ask HR which ones cover you before you go on leave.
Can I go back to work part time?
Some plans pay less while you ease back in. Tell the insurance company before you start, so there are no surprises.
I work for myself. Am I covered?
Only if you bought your own plan or signed up for one; a few states let self-employed people join the state plan.
Does disability insurance pay my medical bills?
No. It pays you, not the hospital. Health insurance handles the medical bills. You can spend your disability check on anything you want, including what you owe the hospital.
How fast will I get my first payment?
Plan on a few weeks from the day we receive all your forms. The first check also comes after the waiting period. I would keep enough cash on hand to cover about a month.
The bottom line
Will disability insurance cover your surgery recovery? Most likely yes, if three things are true:
- The surgery is one your doctor says you need.
- Your coverage started before the health problem did.
- You are out of work longer than the waiting period.
It won’t replace your whole paycheck. And it won’t happen without some work on your part. So here is what I would do this week:
- Ask HR for your plan papers and read them.
- Write down your waiting period and your percent of pay.
- Hand the doctor’s form to your surgeon’s office.
- Count your sick days and vacation days.
- Do the math on how much money will come in each week.
A little homework now lets you spend your recovery resting, not worrying about money.
Why choose Steve Turner Insurance Specialist?
Because I’m an “Insurance Specialist.” An “insurance specialist” is a broad term that includes insurance agents and insurance brokers, but the key difference is who the agent represents versus who the broker represents.
An “insurance agent” works directly for an insurance company and sells its specific policies to clients.
An “insurance broker” acts as an independent intermediary, comparing policies from multiple companies to find the best fit for their client’s needs, essentially representing the client rather than the insurance company.
I am both a licensed Insurance Agent and a licensed Insurance Broker.
My number one goal in life is to help people and ensure, without a shadow of a doubt, that you and your family are secure and protected. I will always be by your side, helping you mitigate risk by providing the industry’s best and most affordable insurance solutions.
I will find insurance plans for the entire family to help cover whatever life throws at you. I can help you save on severe medical emergencies, find a health insurance plan with low- or no-cost doctor visits and affordable prescription medications, and protect your family in the event of an unexpected accident or illness.
Best of all, it doesn’t cost you anything extra to use an experienced Insurance Agent and Broker like me to help you find the Insurance Plans that fit your individual, family, or business needs.
The companies that sell the insurance plans “you choose“ pay me – you don’t pay me. Calling any big insurance company directly won’t get you a lower price, as they will forward your call to the next available insurance agent on their list. You won’t have had any opportunity to learn about the insurance agent you’re speaking with in advance, understand their qualifications or experience level, or make an informed choice about who you want to work with.
Tap the Contact Me text or icon and get in touch by phone or email, or schedule a “No Obligation” chat through my calendar. I look forward to speaking with you!
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, LICENSED INSURANCE AGENT & BROKER
Questions? Call, text, or book a time below; I answer calls and emails 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
EMAIL ME: 24×7
OFFICE LOCATION
Address: 14502 N Dale Mabry Hwy, Suite 200, Tampa, FL 33618
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
DISABILITY INSURANCE POSTS
INSURANCE OFFERINGS
Will Disability Insurance Cover My Surgery Recovery?
HEALTH INSURANCE
MEDICARE ADVANTAGE
MEDICARE SUPPLEMENT
PRESCRIPTION DRUGS
LIFE INSURANCE
DISABILITY INSURANCE
DENTAL INSURANCE
GROUP HEALTH INSURANCE
ACCIDENT INSURANCE
LONG TERM CARE INSURANCE
MEDICAID INSURANCE
MEDICARE INSURANCE
MEDICARE PART A INSURANCE
MEDICARE PART B INSURANCE
MEDICARE PART C INSURANCE
MEDICARE PART D INSURANCE
MEDICARE PLAN G INSURANCE
MEDICARE PLAN N INSURANCE
SERVICE AREA
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please get in touch with Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can use the Medicare Plan Finder at Medicare.gov to research plans available in your Florida county, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.
Steve Turner
Steve Turner, CLU®, REBC® Licensed Florida health insurance agent · License W333468
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals NABIP®, the preeminent organization for health insurance and employee benefits professionals, and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services. Steve also holds the prestigious Registered Employee Benefits Consultant® (REBC®) designation. Steve also holds the “Chartered Life Underwriter” designation (CLU®), a professional credential for individuals specializing in life insurance and estate planning. The American College of Financial Services confers it. For over 10 years, Steve has helped individuals, families, Medicare beneficiaries, and small businesses find the right coverage to meet their needs. Steve has earned 180+ Google reviews from happy clients.
Steve Turner is a licensed agent appointed by Florida Blue.