
Disability Insurance Coverage 2027: What’s Covered & Not
Disability Insurance Coverage 2027: What’s Covered & Not
Disability Insurance Coverage in 2027: What It Covers, What It Doesn’t, and How to Choose the Right Policy
By Steve Turner, CLE® and REBC® · 10+ years advising individuals and business owners
Over my career, I’ve asked thousands of clients the same question: “What is your single most valuable financial asset?” Most say their home, their 401(k), or their investment portfolio. The right answer is more basic. Your most valuable asset is your ability to earn an income.
That income pays the mortgage, funds retirement, and makes investing possible. If a serious illness or injury stops it, every other part of your plan stalls. That’s why I treat disability insurance as the foundation of a financial plan, not an add-on.
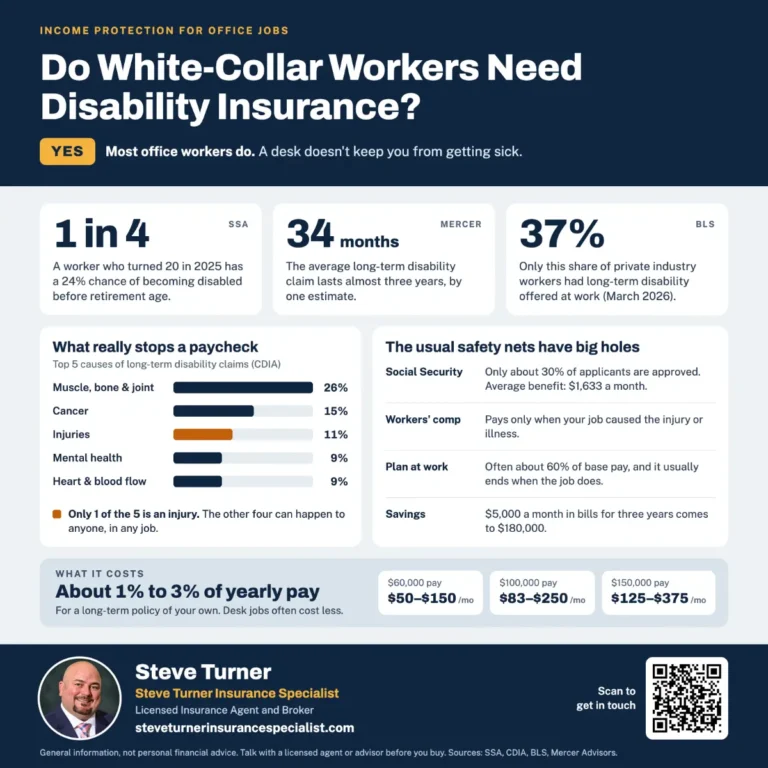
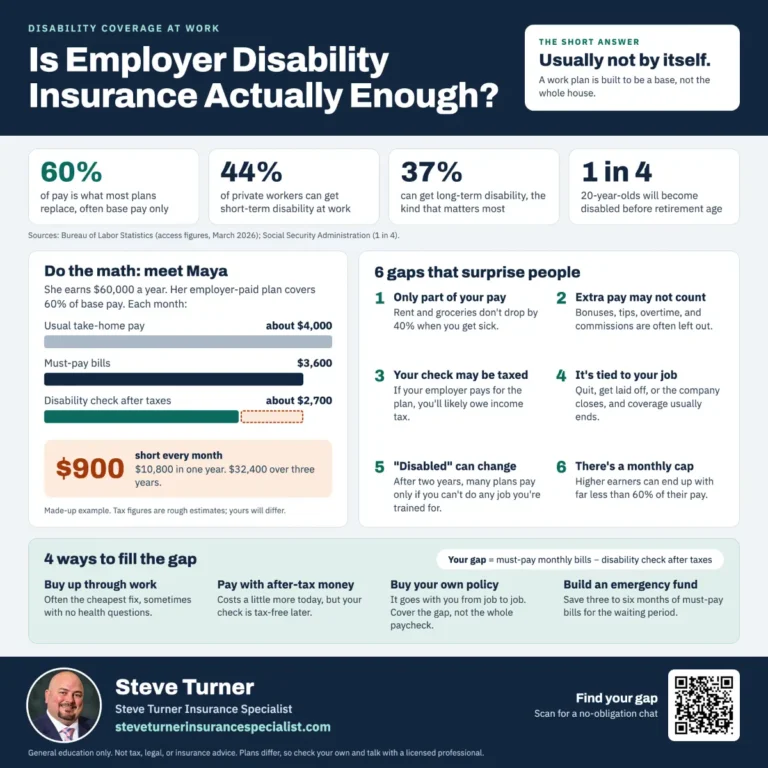
The risk is not remote. According to the Social Security Administration, a 20-year-old worker has about a 1-in-4 chance of developing a disability before reaching full retirement age. And the government safety net is thin: SSA estimates the average Social Security disability check for 2027 at $1,701 a month after the 3.6% cost-of-living adjustment (SSA 2027 fact sheet). For most professionals, that replaces a fraction of their pay.
Since there is no Florida state law requiring private employers to offer disability insurance or regulating uniform elimination periods, waiting periods are determined strictly by individual insurance policy contracts:
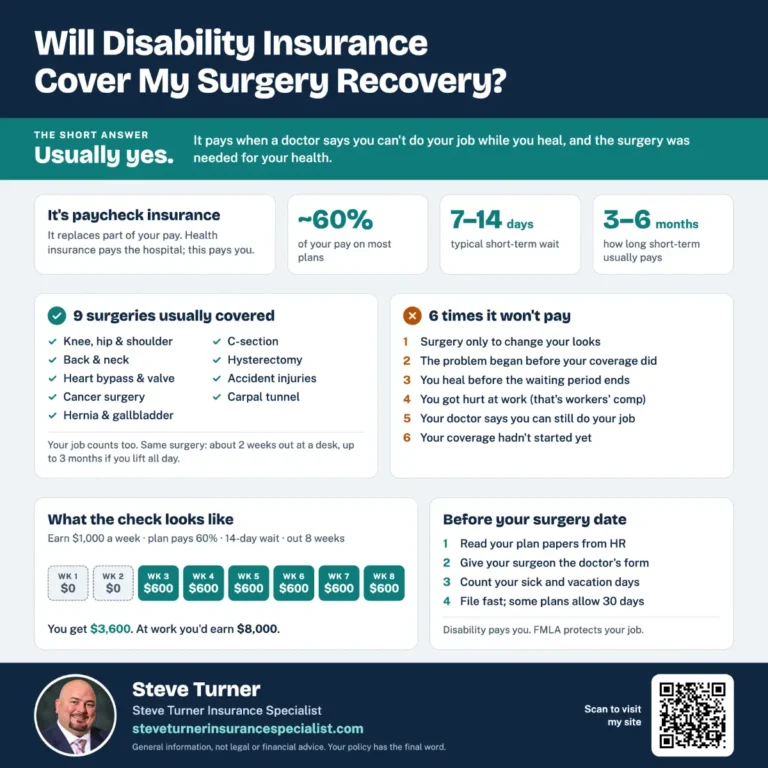
- Short-Term Disability (STD): Typically has a waiting period of 7 to 14 days before benefits begin.
- Long-Term Disability (LTD): Commonly has an elimination period of 90 to 180 days.
- High Authority Overview Source: You can review how private policies operate via the Florida Department of Financial Services. [1, 2, 3, 4]
2. Workers’ Compensation Disability (On-the-Job Injuries)
If your disability is due to a work-related injury or illness, Florida statutory law mandates a 7-day waiting period. [1, 2]
- The 21-Day Exception: You will not receive lost-wage compensation for the first 7 days unless your disability lasts more than 21 days. If it exceeds 21 days, you will be paid retroactively for the first 7 days.
- High Authority Legal Source: This mandate is explicitly written into law under Florida Statute § 440.12(1) on Online Sunshine. [1, 2]
3. Social Security Disability Insurance (SSDI – Federal)
For long-term federal disability, Florida residents fall under federal Social Security rules. [1]
- A mandatory 5-month waiting period applies from your established onset date before cash benefits can begin. (The waiting period is waived if your disability is due to ALS).
- High Authority Government Source: This is detailed directly on the federal Social Security Administration (SSA) Benefits Page.
Disability insurance vs. health and accident insurance
People often confuse these three. They do different jobs:
| Coverage | Who it pays | What it pays for |
|---|---|---|
| Health insurance | Doctors, hospitals, pharmacies | Medical treatment |
| Accident insurance | You, as a lump sum | Costs tied to a specific injury |
| Disability insurance | You, monthly | A share of your lost paycheck while you can’t work |
In short, disability insurance is income protection insurance. Below, I explain what it covers, what it doesn’t, and how it works for both individuals and businesses.
Key takeaways
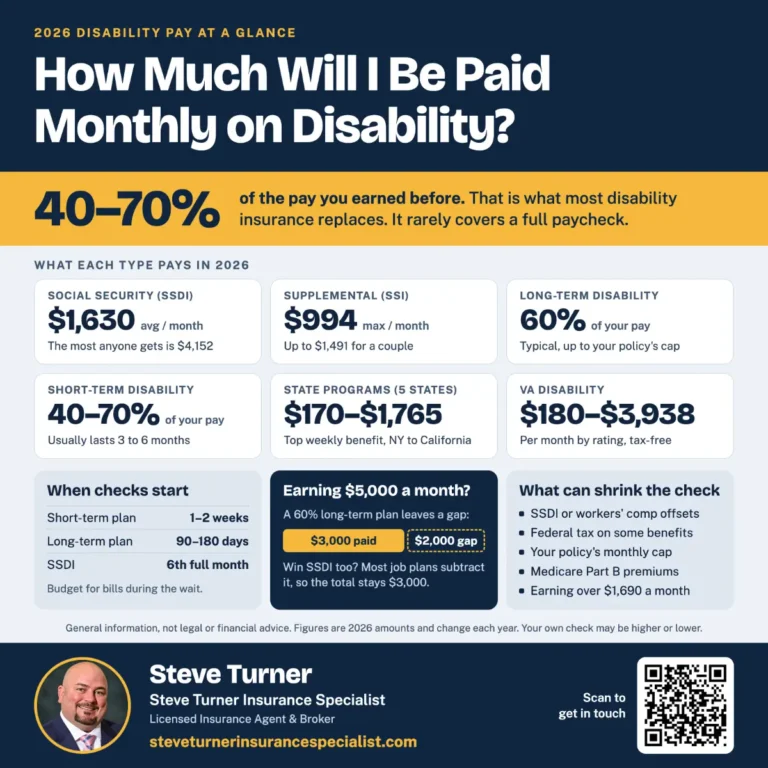
- Disability insurance replaces a portion of your income (typically 50%–70%) when illness or injury keeps you from working.
- The definition of disability, own-occupation or any-occupation, matters more than any other policy clause.
- It does not pay medical bills, cover short absences, cover layoffs, or cover normal maternity leave.
- Business owners can protect the company separately with key person, buy-sell, and overhead expense policies.
Part 1: Disability insurance for individuals
An individual disability policy is a private contract between you and an insurer to protect your personal income. It’s your main defense against a long, career-threatening health crisis. Before looking at what’s covered, you need to know four terms that set the limits of your protection.
1. Elimination period (waiting period)
Think of it as a deductible measured in days, not dollars. It’s how long you must be disabled before benefits start. Common choices are 90, 180, or 365 days. A longer elimination period lowers your premium, but your emergency fund has to cover the gap.
2. Benefit period
This is the longest the policy will pay once you qualify. Options usually include 2 years, 5 years, or to age 65 or 67. For most working professionals, I recommend a benefit period to at least age 65.
3. Definition of disability
This is the most important clause in your policy. It sets the exact test the insurer uses to decide whether you’re “disabled.”
- Own-occupation (“own-occ”): You’re disabled if you can’t perform the material and substantial duties of your specific occupation. A surgeon who develops a hand tremor would collect full benefits, even while earning a living teaching at a medical school. This is the definition I recommend for most professionals.
- Any-occupation (“any-occ”): You’re disabled only if you can’t work in any job you’re reasonably suited for by education, training, or experience. Under this definition, the insurer could deny that same surgeon’s claim because they can still teach.
- Modified or transitional own-occ: Many policies blend the two, for example, own-occ for the first 2–5 years, then any-occ. Read this language closely before you sign.
4. Benefit amount
Individual policies typically replace 50%–70% of pre-disability income, up to an insurer’s maximum. If you pay premiums with after-tax dollars, benefits are generally income-tax-free. If your employer pays, benefits are generally taxable (IRS Publication 525).
From my practice: The clients most disappointed at claim time rarely chose the wrong insurer. They skimmed the definition of disability. Ask your agent to show you that paragraph in the actual contract, not the brochure.
What individual disability insurance covers
Disability insurance doesn’t cover “items” like a broken bone or a hospital stay. It covers lost income from medical conditions that keep you from working. These are the main categories that trigger benefits.
1. Serious and systemic illnesses
These life-altering diagnoses can keep you out of work for months, years, or permanently:
- Cancer and the effects of chemotherapy and radiation
- Heart attacks and strokes requiring long rehabilitation
- Autoimmune disorders such as multiple sclerosis, lupus, and rheumatoid arthritis
- Organ failure (kidney, liver, heart), including transplant recovery
- Neurological disorders such as Parkinson’s disease and ALS
2. Musculoskeletal injuries and disorders
These are among the most common causes of long-term disability claims. Many are degenerative rather than the result of one accident:
- Back and spine conditions (herniated discs, spinal stenosis)
- Joint disorders requiring hip or knee replacement
- Severe arthritis that limits mobility or dexterity
- Repetitive stress injuries, such as advanced carpal tunnel syndrome
3. Mental health conditions
Quality policies recognize that disabling conditions aren’t only physical. Covered conditions can include severe clinical depression, bipolar disorder, PTSD, and severe anxiety disorders.
Check this provision: Many policies cap mental and nervous claims at 24 months unless you’re hospitalized. Some insurers also apply this limit to substance-use claims.
4. Complications of pregnancy
Most individual policies don’t cover a normal pregnancy or standard recovery from childbirth. Unforeseen complications are covered. If your doctor orders months of bed rest for a high-risk condition, your policy would replace income during that time.
5. Long recoveries from accidents
Accident insurance pays cash for the injury itself. Disability insurance protects your income through the recovery. If a car accident keeps you out of work for 18 months, your policy starts paying monthly once your elimination period ends.
6. Partial or residual disability
The best policies include a residual benefit. It pays a partial benefit if you return to work at reduced hours or earnings. For example, if you earn 50% of your prior income, the policy pays roughly 50% of your full benefit while you transition back.
Riders worth considering in 2027
- Cost-of-living adjustment (COLA) rider: Increases benefits during a long claim so inflation doesn’t erode them.
- Future increase option: Lets you buy more coverage as your income grows, without new medical underwriting.
- Non-cancelable and guaranteed renewable: The insurer can’t cancel your policy or raise your premium as long as you pay.
What individual disability insurance does not cover
I spend as much time explaining exclusions as coverage. Knowing them up front prevents unpleasant surprises at claim time.
- Medical bills. Disability insurance doesn’t pay doctors or hospitals; health insurance does. Your disability check pays the mortgage, groceries, and everyday bills. The two policies work together but have different jobs.
- Short absences. With a 90-day or longer elimination period, long-term coverage won’t pay for two weeks of flu, a month off after minor surgery, or a six-week fracture. Those call for an emergency fund or a short-term disability (STD) policy.
- Job loss. Disability insurance isn’t unemployment insurance. It pays nothing if you’re fired, laid off, or your company downsizes.
- Normal pregnancy and maternity leave. A healthy pregnancy isn’t an unforeseen disability. Only complications during pregnancy, or a recovery that runs longer than normal, trigger benefits. (Some states’ paid family and medical leave programs and many employer STD plans do cover childbirth recovery.)
- Pre-existing conditions. Group policies commonly exclude disabilities from conditions treated within a look-back period, often 3–12 months, before coverage started. Individual policies usually handle this at underwriting, by excluding or rating specific conditions. Either way, disclose your full medical history; misstatements can void a claim.
- War, riots, and felonies. Like most insurance, disability policies exclude injuries from acts of war and those sustained while committing a crime. Intentionally self-inflicted injuries are also typically excluded.
Why Social Security disability (SSDI) isn’t a substitute
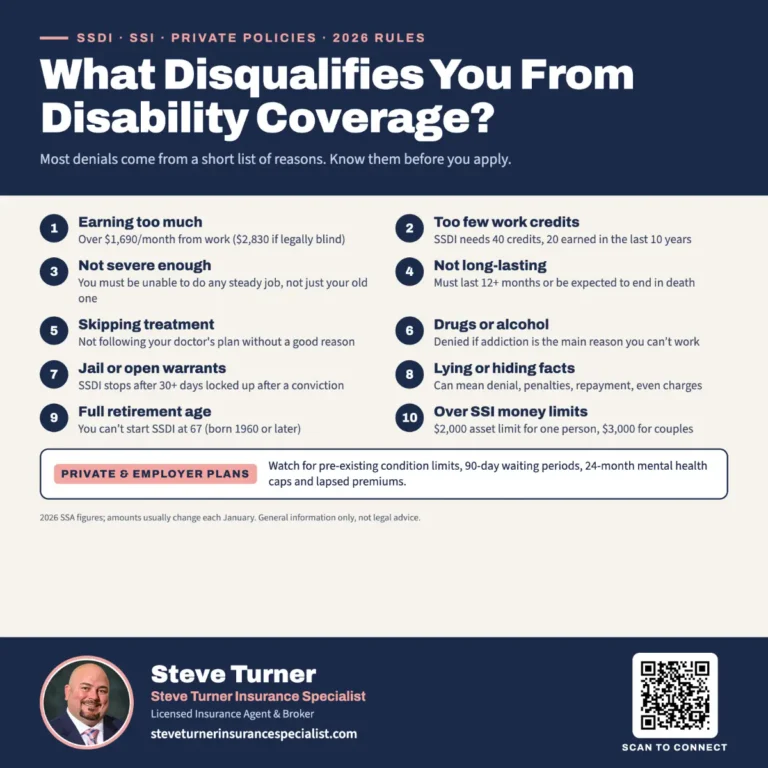
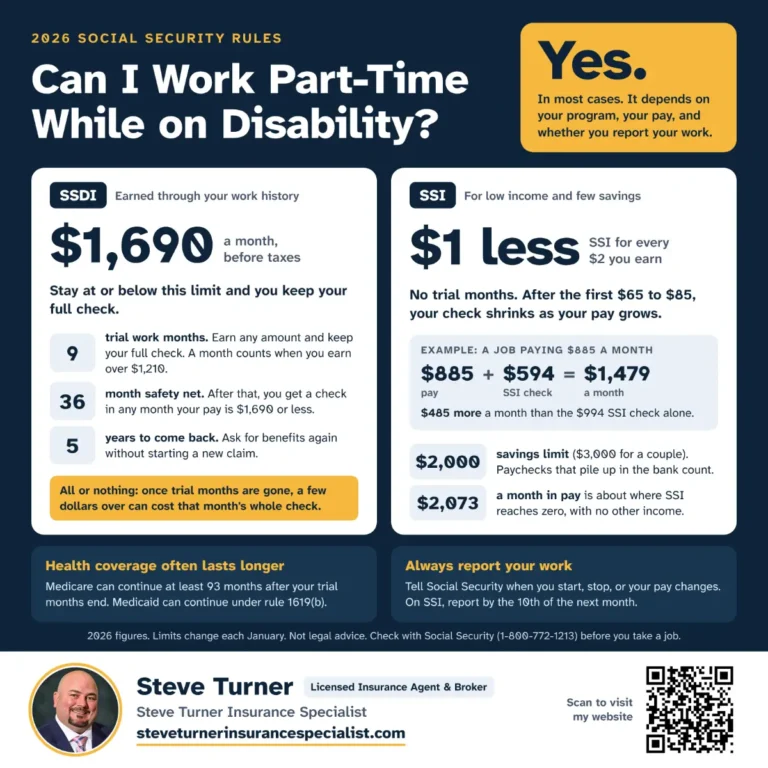
SSDI uses a strict any-occupation-style test: you must be unable to do substantial work of any kind, expected to last at least 12 months or result in death. In 2027, earning more than $1,770 a month ($2,950 if blind) generally counts as substantial gainful activity, which can end eligibility (SSA 2027 fact sheet). Approval can take months, and the average benefit is $1,701 a month. Treat SSDI as a possible floor, not your plan.
Part 2: Disability insurance for businesses
For a business owner, disability insurance is also a continuity tool. It protects the company from the financial shock of an owner or key employee being unable to work. Business disability insurance isn’t one product but four, each built for a different risk.
| Policy | Protects | Who receives benefits | What the money is for |
|---|---|---|---|
| Key person disability | The business | The company | Replacing lost revenue, recruiting and training a replacement |
| Disability buy-out (buy-sell) | The partners | The remaining owners (or the business) | Buying the disabled partner’s stake at a pre-agreed price |
| Business overhead expense (BOE) | The owner’s business | The business | Rent, staff salaries, utilities, taxes, leases |
| Group STD / LTD | Employees | Each employee | Replacing part of the employee’s paycheck |
1. Key person disability insurance
The business insures an employee whose loss would hurt revenue: a lead surgeon, a top engineer, or a salesperson who brings in half of sales. If that person becomes disabled, the company receives the benefits. Typical uses include hiring and training a replacement, offsetting lost profits, and reassuring lenders and clients.
2. Disability buy-out insurance
Most partnerships have a buy-sell agreement covering death or departure. A disability buy-out policy funds that agreement when a partner becomes long-term disabled. After a long waiting period, often 12–24 months, it pays a lump sum or installments so the remaining partners can buy the disabled partner’s share. That gives the disabled partner fair value and the business a clean transition.
3. Business overhead expense (BOE) insurance
BOE is built for small businesses where the owner’s work generates the revenue. It doesn’t replace the owner’s salary. It pays the business’s fixed operating costs, such as rent or mortgage, employee salaries and benefits, utilities, property taxes, insurance premiums, and equipment leases. BOE benefit periods are usually short, often 12–24 months, giving the owner time to recover or sell.
4. Group short-term and long-term disability
This is the coverage employers offer as a benefit.
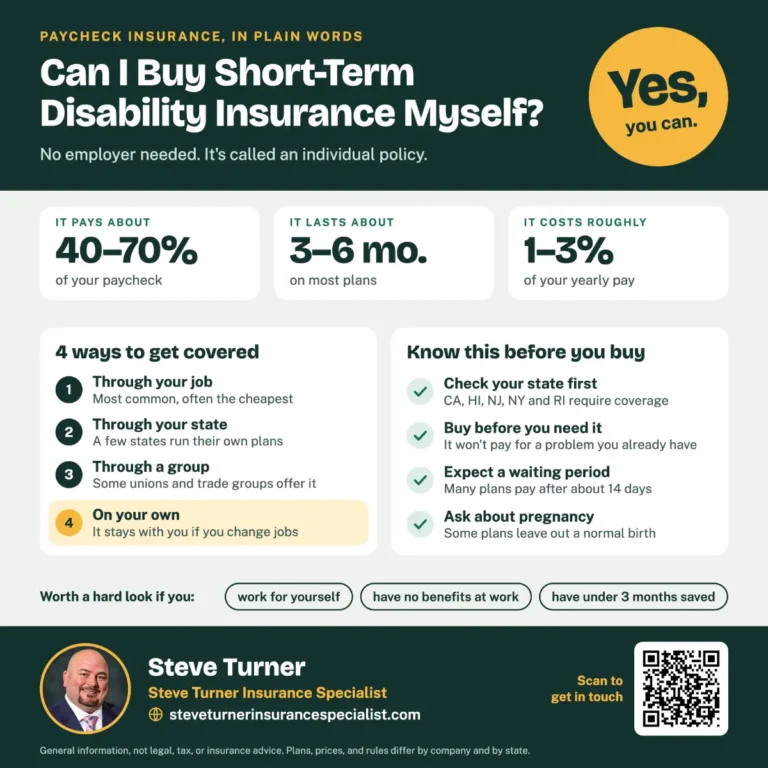
- Short-term disability (STD): Typically starts after 1–14 days and lasts 3–6 months.
- Long-term disability (LTD): Starts when STD ends and can run for years or to retirement age.
Group plans are valuable but often weaker than individual policies. They frequently use any-occ definitions after 24 months, cap benefits, offset SSDI payments, and end when you leave the job. Many professionals pair group LTD with an individual policy.
What business disability insurance does not cover
- The owner’s personal salary under BOE. BOE pays only the business’s bills. Owners need a separate individual policy for their own income.
- Business failure or bankruptcy. These policies trigger only with a qualifying medical disability, not a downturn or poor performance.
- Double recovery with workers’ compensation. Workers’ comp covers job-related injuries and illnesses. Group LTD usually covers disabilities on or off the job, but reduces its benefit by any workers’ comp you receive—the two coordinate rather than stack.
- Partnership disputes or voluntary exits. Buy-out coverage pays only for a qualifying long-term disability, not a disagreement, resignation, or retirement.
- Benefits beyond the policy’s purpose. Key person benefits are meant to offset the cost of losing that person. Confirm how your contract and accountant treat them, since tax treatment depends on who pays the premium.
Frequently asked questions
What does disability insurance cover? It replaces part of your income, usually 50%–70%, when an illness or injury keeps you from working. Covered causes include cancer, heart disease, back injuries, mental health conditions, and pregnancy complications.
What is the difference between own-occupation and any-occupation disability insurance? Own-occupation pays if you can’t do your specific job. Any-occupation pays only if you can’t do any job you’re reasonably suited for. Own-occupation is stronger and costs more.
Is employer disability insurance enough? Often not. Group LTD commonly caps benefits, may be taxable, and usually ends when you leave the employer. An individual policy fills those gaps.
Are disability insurance benefits taxable? If you pay premiums with after-tax money, benefits are generally tax-free. If your employer pays, they’re generally taxable income.
Does disability insurance cover maternity leave? Not a normal pregnancy or standard recovery. It does cover disabling complications, and some employer STD plans and state programs cover childbirth recovery.
How much is the average SSDI benefit in 2027? SSA estimates $1,701 a month for all disabled workers after the 3.6% COLA.
Final thoughts
Your ability to earn an income drives your financial life, and disability insurance protects it. For your family, it guards your lifestyle. For your business, it guards your legacy. Review your current coverage, read your policy’s definition of disability, and close any gaps before you need them.
About the author
Steve Turner, CLE® and REBC®, has spent 10+ years helping individuals, physicians, and small-business owners build income-protection plans.
This article is for educational purposes only and isn’t individualized financial, tax, or legal advice. Policy terms vary by insurer and state; review your contract and consult a licensed professional.
Sources
- Social Security Administration, 2027 COLA Fact Sheet (SGA thresholds, average disabled-worker benefit)
- Social Security Administration, Disability Benefits (EN-05-10029) (1-in-4 disability odds)
- IRS Publication 525, Taxable and Nontaxable Income (tax treatment of benefits)
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
Richard Steven Turner’s official Florida state insurance license number (operating as Steve Turner Insurance Specialist) is W333468
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
DISABILITY INSURANCE POSTS
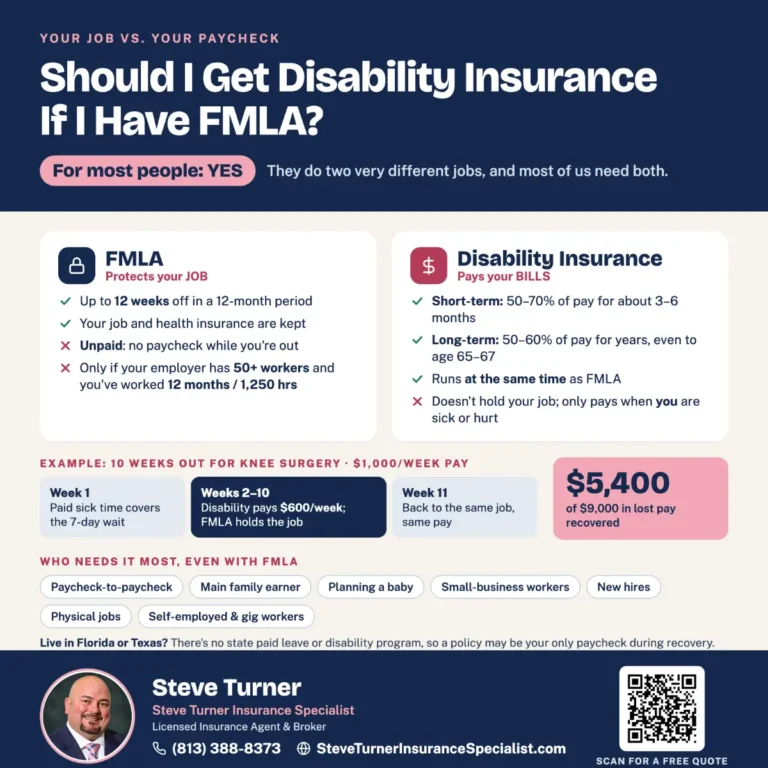
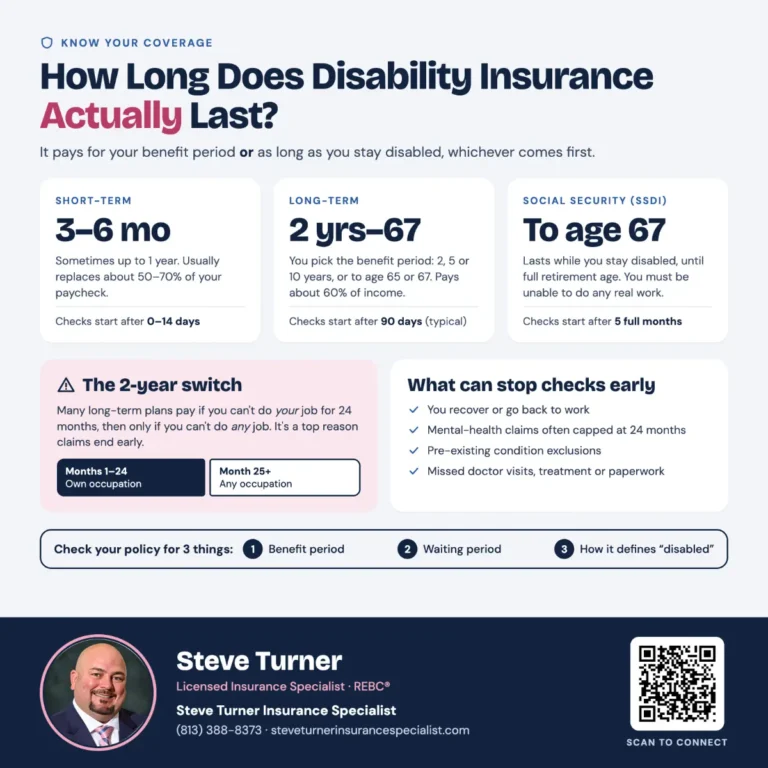
MEDICARE STATEMENT
We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please get in touch with Medicare.gov or 1-800-MEDICARE for information on all your options.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can use the Medicare Plan Finder at Medicare.gov to research plans available in your Florida county, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.
Steve Turner
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® (REBC®) designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.