
How to Verify Your Health Insurance Agent is Licensed

How to Verify Your Health Insurance Agent is Licensed
The short answer
You can verify that your health insurance agent is licensed in about five minutes, and it is free. Here is what I do:
- I ask the agent for their full legal name and license number.
- I look them up on my state insurance department’s website.
- I make sure the license is active, covers health insurance, and is valid in my state.
If all three check out, I keep talking. If even one does not, I stop and walk away.
That is the whole idea. But the details matter, because a fake agent can sound just as friendly as a real one. When I buy health insurance, I share my Social Security number, my income, and my health history. I only want to hand those to someone my state has approved.
In this guide, I will show you:
- Why a license check is worth your time
- What a health insurance license really is
- The exact steps I follow to look someone up
- How to read what the search shows you
- Warning signs of a fake agent
- What to do if something looks wrong
Why I always check the license
A license shows me my state has vetted the person selling me a plan. To get one, an agent has to pass a state exam. Most states also run a background check and require classes. Selling insurance without a license is illegal in every state.
Here is why that matters to me:
- Someone is watching. The state can fine a licensed agent or take the license away. That gives the agent a strong reason to treat me fairly.
- My private details stay safer. An agent sees my Social Security number, my income, and my health needs. A fake agent can use those to steal my identity.
- My money stays safer. A scammer can take my first payment and never sign me up.
- My coverage is real. People without a license often sell things that only look like insurance. I might not find out until a hospital bill shows up.
- I have a place to turn. If a licensed agent treats me badly, I can file a complaint with my state. The state knows who they are and where to find them.
A license does not promise that an agent is nice or gives great advice. It does tell me the person is real, trained, and allowed to sell to me. That is the least I should expect.
What a health insurance license is
A health insurance license is permission from a state to sell health plans to the people who live there. Each state gives out its own licenses. No single license covers the whole country.
A few words come up again and again when I look someone up. Here is what they mean:
| Word | What it means |
|---|---|
| Agent | A person who sells plans for one or more insurance companies. |
| Broker | A person who shops many companies for me. Brokers need a license too. |
| Producer | The word states used to refer to agents and brokers together. |
| License number | The number a state gives the agent. It can differ by state. |
| National Producer Number (NPN) | One ID number that follows an agent across every state. |
| Resident license | The license from the state where the agent lives. |
| Non-resident license | A license from another state where the agent also sells. |
| Line of authority | The kind of insurance the agent may sell, such as health, life, or auto. |
Two rules matter most to me:
- The agent needs a license in my state. It is not enough to be licensed where they live. An agent who lives in Texas needs an Ohio license to sell me a plan in Ohio.
- The license has to cover health insurance. A person licensed only for car insurance cannot sell me a health plan. On a search page, the health line may be called “Health,” “Accident and Health,” or “Accident and Health or Sickness.”
What I ask the agent for first
A real agent hands over these details without a fuss. I ask for them before I share anything private:
- Full legal name. I want the name on the license, not a nickname. A license for “Robert” may not show up under “Bobby.”
- State license number. This is my state number.
- National Producer Number (NPN). This one number works in every state.
- Home state. This tells me where the agent’s main license is.
- Agency name. This is the business the agent works for. Agencies hold licenses too.
- Insurance companies they sell for. I can call one of those companies later to check.
I ask for all of this in writing. A text or an email works fine. That way I am not guessing at the spelling later.
How the agent reacts tells me a lot. Good agents are proud of their license. Many put the number on a business card, an email, or a website. If someone gets annoyed, changes the subject, or says “you don’t need that,” I treat it as a warning sign.
How to verify a health insurance agent’s license, step by step
I can check a license in six steps. Most of the time, the first search gives me my answer.
Step 1: Find my state insurance department
Every state has an office that licenses agents. The name changes from place to place. It may be called the Department of Insurance, the Division of Insurance, or the Office of the Insurance Commissioner.
To make sure I land on the right site, I start with the NAIC list of state insurance departments. The NAIC is the national group for state insurance regulators. Its page has a “Find an Insurance Agent” box. I pick my state, and it points me to the right place.
Step 2: Open the license search
On my state’s site, I look for a link with a name like:
- License Lookup
- Licensee Search
- Agent Search
- Producer Search
Many states share one lookup tool built by the NAIC so that the page may look the same from state to state. The search is free.
Step 3: Search by number, not just by name
I type in the license number or the NPN. A number points to one person. A name can match dozens of people.
If all I have is a name, I enter the last name and the first name. Then I use the city to narrow the list.
Step 4: Make sure it is the same person
A scammer can borrow a real agent’s name and number. So I compare the state record with what the agent told me:
- Does the full name match?
- Does the city or business address match?
- Does the agency name match?
If the record lists a phone number or an email, I use it to reach the agent. Then I know I am talking to the person who holds the license.
Step 5: Check three things on the record
- Status. It should say “Active.”
- State. The license should be for the state where I live.
- Line of authority. It should include health insurance.
I explain each of these in the next section.
Step 6: Save proof
I take a screenshot or print the page. I make sure the date shows. If there is ever a problem, I can prove that I checked.
Bonus step: Call the insurance company
Before I pay for a plan, I call the insurance company. I use the phone number on the company’s own website, not one the agent gave me. I ask, “Is this agent allowed to sell your plans?” Companies keep a list of the agents who may sell for them.
Stuck? If the website confuses me, I call my state insurance department. The staff there can look up the agent for me.
How to read the license search results
The search page can look crowded. I only need to read a few lines.
License status
| Status | What it means | What I do |
|---|---|---|
| Active | The license is good right now. | Keep going. |
| Inactive, expired, or lapsed | The agent stopped or did not renew. | Stop. The agent cannot sell to me until it is fixed. |
| Suspended | The state has put the license on hold. | Walk away. |
| Revoked | The state took the license away. | Walk away and report any sales pitch. |
| Canceled or surrendered | The license has ended. | Stop. |
States use slightly different words, but “Active” is the one I want to see.
Other lines worth reading
- License type. It may say resident or non-resident. Either is fine as long as the license is from my state.
- Lines of authority. I look for health. If I only see lines like property, casualty, or auto, this agent cannot sell me a health plan.
- Expiration date. I make sure the date has not passed. A date coming up soon is normal. Agents renew on a regular schedule.
- Actions against the license. Some states list fines or orders. I read them. A late-paperwork fine from years ago is different from lying to customers or misusing their money.
- Company appointments. Some states list the insurance companies the agent may sell for. I check that the company behind my plan is there.
What if no record shows up?
No record does not always mean the agent is fake. Before I decide, I try this:
- Check my spelling.
- Search the legal name instead of a nickname.
- Search by license number or NPN.
- Make sure I picked the right state.
- Call the state insurance department and ask.
Until a record turns up, I do not share private details or pay anything.
Extra checks for Marketplace and Medicare agents
A state license is the first test. Marketplace and Medicare plans each add one more.
Marketplace (HealthCare.gov) plans
An agent who sells plans through HealthCare.gov needs more than a state license. The agent must also register with the Marketplace and complete training each plan year.
Here is how I check:
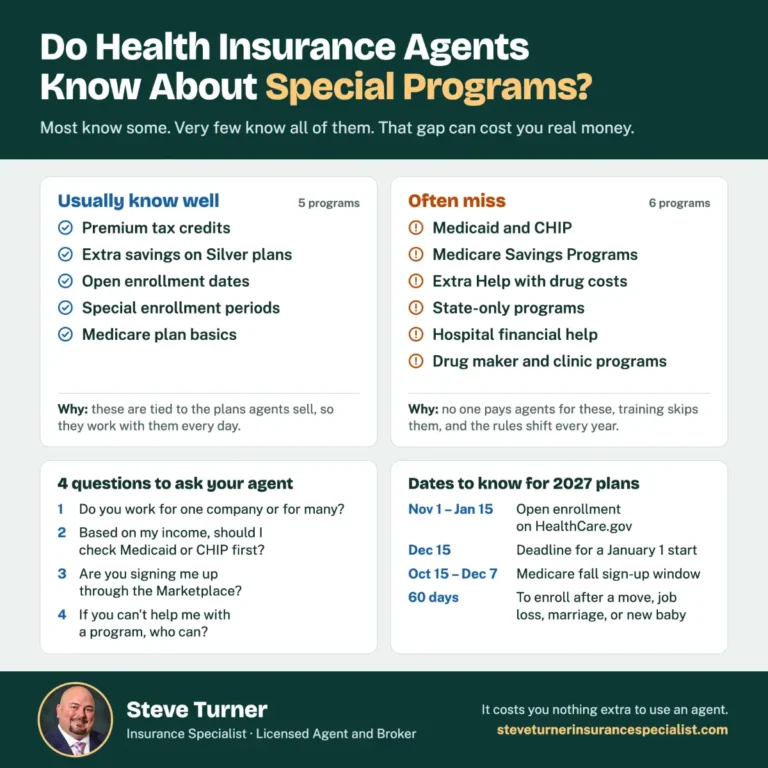
- Search Find Local Help. I go to Find Local Help on HealthCare.gov and type in my ZIP code. The agents and brokers shown there are registered with the Marketplace. Agents choose whether to be listed, so a missing name doesn’t prove a problem.
- Look at the public registration list. The government posts a list of agents and brokers who finished Marketplace registration. I look for my agent’s NPN.
- Call the Marketplace Call Center. If I am still not sure, I call 1-800-318-2596 and ask.
Some states run their own marketplace instead of using HealthCare.gov. If mine does, I use the “find help” page on my state’s marketplace site.
One more thing I keep in mind: I pay my premium to the insurance company, never to the agent. HealthCare.gov says the same.
Medicare plans
Medicare.gov says the state must license independent agents and brokers who sell Medicare plans. So I run the same state license search.
Then I watch how the agent acts. People who represent Medicare plans are not allowed to:
- Come to my home uninvited
- Call me, unless I am already a member or I said they could
- Offer me cash or gifts worth more than $15 to join
- Charge me a fee to process my enrollment
- Ask me to pay over the phone or online. The plan must send a bill.
If an agent breaks these rules, I call 1-800-MEDICARE (1-800-633-4227).
Why timing matters
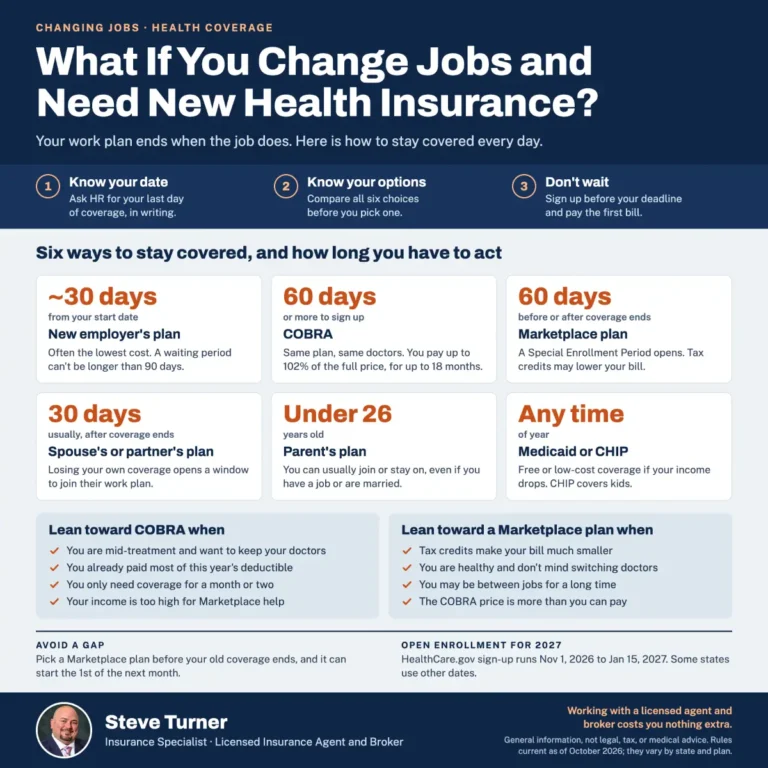
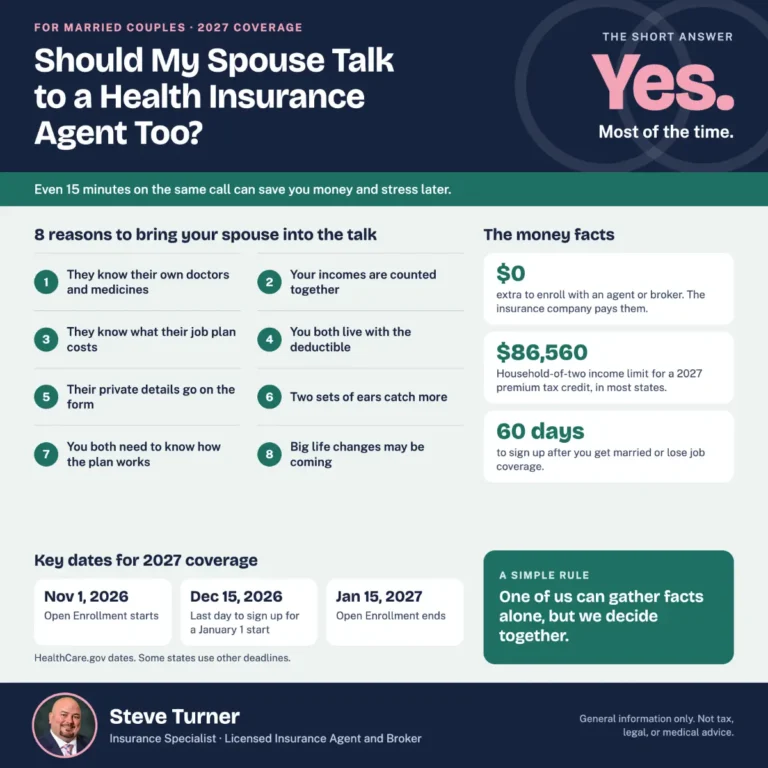
Medicare Open Enrollment runs from October 15 to December 7 each year. Marketplace Open Enrollment starts November 1 in most states. Sales calls pick up during those weeks, so that is when I am most careful.
10 red flags of a fake or unlicensed agent
One red flag makes me slow down. Two make me hang up.
- They will not give a license number. A real agent shares it right away.
- The record does not match. The name, city, or agency on the state site is different from what they told me.
- They rush me. I hear things like “this price ends today” or “I need your answer right now.”
- They want me to pay them directly. They ask for cash, gift cards, a payment app, or crypto. Real premiums go to the insurance company.
- They charge a fee to sign me up. No one should charge me to apply for a Marketplace plan or to join a Medicare plan.
- They say they are from the government. They call or text out of nowhere and claim to be from Medicare or the Marketplace.
- They offer cash or gifts. HealthCare.gov warns about ads that promise money, gifts, or other rewards for signing up.
- They want my private numbers first. They ask for my Social Security or bank number before they tell me who they are.
- They ask for my HealthCare.gov password. A real agent works from their own account and does not need mine.
- They will not put it in writing. They dodge when I ask for plan papers that show the insurance company’s name.
The plan itself can be a red flag too. If the price is far lower than everything else I have seen, I ask more questions before I agree to anything.
What to do if the license does not check out
If I cannot confirm a license, I stop and follow these steps in order.
- Stop sharing. I do not give out more details, sign anything, or pay.
- Check my own work. I run the search again with the correct spelling and state.
- Ask the agent one time. I say, “I could not find your license. Can you send me the number and the state?” An honest agent clears this up fast.
- Call my state insurance department. I ask the staff to confirm the license. If the person is not licensed, I report it. The NAIC website has a “File a Complaint” box that sends me to my state.
- Report it to the right place. For any scam, I report it to the Federal Trade Commission at ReportFraud.ftc.gov. For a Marketplace plan, I call the Marketplace Call Center at 1-800-318-2596. For a Medicare plan, I call 1-800-MEDICARE.
If I already shared my information
I act quickly:
- I call the insurance company and ask if my plan is real and active.
- I log in to my HealthCare.gov account and look for changes I did not make.
- I watch my bank and credit card statements.
- I tell my bank if I gave out an account number.
- I report it to the FTC and my local police, as HealthCare.gov suggests.
Reporting helps more than just me. It can keep the same person from fooling my neighbors.
Common questions about checking an agent’s license
How long does it take to verify a health insurance agent’s license?
About five minutes. It goes fastest when I have the license number or the NPN.
Does it cost anything to look up a license?
No. State license searches are free.
Is an agent the same as a broker?
Not quite. An agent sells for one or more insurance companies. A broker shops many companies for me. Both need a state license, and I check them the same way.
Can an agent in another state sell me a plan?
Yes, if the agent holds a non-resident license in my state. I look the agent up on my state’s site, not theirs.
Do navigators need an insurance license?
Navigators and assisters are not agents. HealthCare.gov describes them as people trained and certified by the Marketplace to give free help. I find them through Find Local Help. Some states also show them in the license search.
Where do I find an agent’s NPN?
I ask the agent. The number often shows on the state license record too.
Does an active license mean the agent is good?
No. It means the agent is real and allowed to sell in my state. I still compare plans, ask questions, and read the plan papers myself.
How often should I check?
Once a year, before I sign up or renew; a license can expire or be taken away.
Do I have to pay an agent?
Usually not. HealthCare.gov says the insurance companies generally pay agents and brokers.
What if I am talking to a call center or a website?
The same rules apply. The person helping me still needs a license in my state. I ask for that person’s own name and license number, not just the company’s.
Can I check a license by phone?
Yes. I call my state insurance department and give the agent’s name and license number. Staff can tell me whether the license is active. This helps when I do not have a computer nearby.
Is a business card or a certificate enough proof?
No. Cards and certificates are easy to fake. They also cannot show if a license was taken away last month. The state website shows what is true today.
My quick license checklist
Before I share private details or pay for a plan, I make sure I can say yes to each of these:
- I have the agent’s full legal name, license number, and NPN in writing.
- I found the agent on my state insurance department’s website.
- The license status is active.
- The license is for the state where I live.
- The license covers health insurance.
- The name, city, and agency match what the agent told me.
- For a Marketplace plan, the agent is registered with the Marketplace.
- I saved a dated screenshot of the record.
The bottom line
Verifying that a health insurance agent is licensed takes about five minutes. Cleaning up after a fake agent can take far longer. So I check every time, even when the agent seems kind and the price sounds great. A real agent will not mind. In fact, most are glad I asked.
Why choose Steve Turner Insurance Specialist?
Because I’m an “Insurance Specialist.” An “insurance specialist” is a broad term that includes insurance agents and insurance brokers, but the key difference is who the agent represents versus who the broker represents.
An “insurance agent” works directly for an insurance company and sells its specific policies to clients.
An “insurance broker” acts as an independent intermediary, comparing policies from multiple companies to find the best fit for their client’s needs, essentially representing the client rather than the insurance company.
I am both a licensed Insurance Agent and a licensed Insurance Broker.
My number one goal in life is to help people and ensure, without a shadow of a doubt, that you and your family are secure and protected. I will always be by your side, helping you mitigate risk by providing the industry’s best and most affordable insurance solutions.
I will find insurance plans for the entire family to help cover whatever life throws at you. I can help you save on severe medical emergencies, find a health insurance plan with low- or no-cost doctor visits and affordable prescription medications, and protect your family in the event of an unexpected accident or illness.
Best of all, it doesn’t cost you anything extra to use an experienced Insurance Agent and Broker like me to help you find the Insurance Plans that fit your individual, family, or business needs.
The companies that sell the insurance plans “you choose“ pay me – you don’t pay me. Calling any big insurance company directly won’t get you a lower price, as they will forward your call to the next available insurance agent on their list. You won’t have had any opportunity to learn about the insurance agent you’re speaking with in advance, understand their qualifications or experience level, or make an informed choice about who you want to work with.
Tap the Contact Me text or icon and get in touch by phone or email, or schedule a “No Obligation” chat through my calendar. I look forward to speaking with you!
OUR CLIENT REVIEWS


CONTACT STEVE TURNER INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a longstanding member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable Healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7 a.m. to 8 p.m.
Tuesday: 7 a.m. to 8 p.m.
Wednesday: 7 a.m. to 8 p.m.
Thursday: 7 a.m. to 8 p.m.
Friday: 7 a.m. to 8 p.m.
Saturday: 7 a.m. to 8 p.m.
Sunday: 7 a.m. to 8 p.m.
SOCIAL FOLLOW + SHARE
Insurance Agent
MEDICARE STATEMENT
The Medicare Annual Enrollment Period is October 15th to December 7th. Steve Turner is not connected with or endorsed by the United States Government or the Federal Medicare Program. Some plans may not be available in your area, and any information I provide is limited to those offered. Please contact Medicare.gov or 1-800-MEDICARE for information on all your options.
There’s no one-size-fits-all answer. Carefully evaluate your health status, anticipated medical needs, prescription drug usage, budget, preferred doctors and hospitals, and tolerance for network rules. During the Medicare Annual Enrollment Period (October 15th to December 7th), research the specific plans available in your Florida county using the Medicare Plan Finder on Medicare.gov, compare costs and benefits, and consider free, personalized counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program.