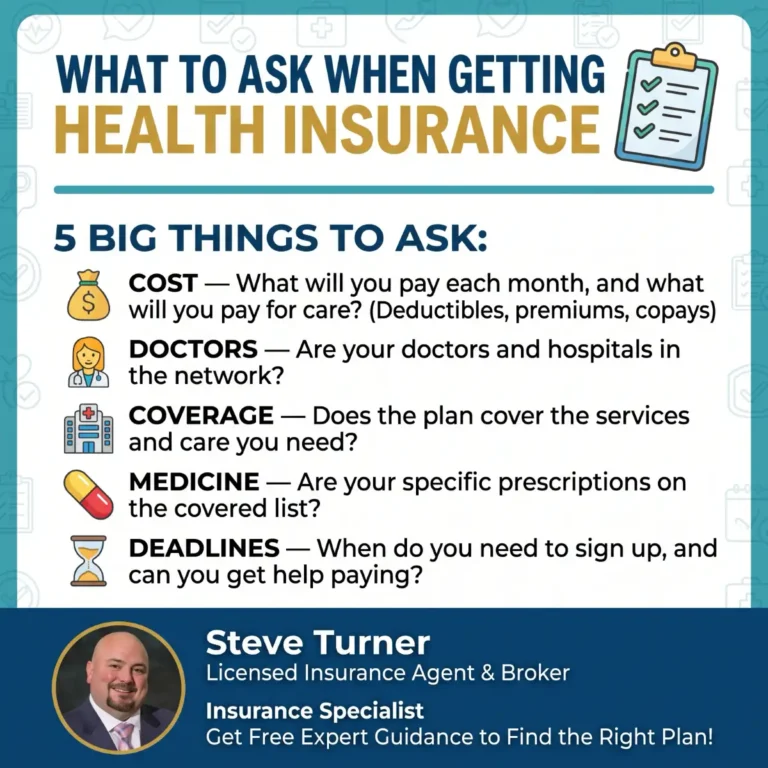
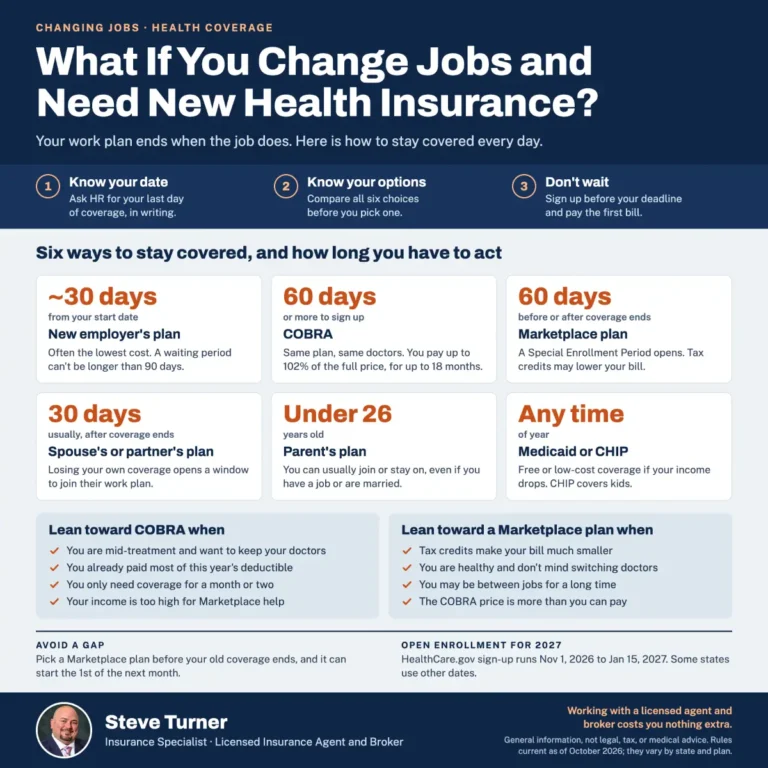
|⏳ HEALTH INSURANCE AGENCY |⏳ INSURANCE ENROLLMENT KEY DATES |⏳ MEDICARE PLANS: Annual Enrollment Period (AEP): October 15 – December 7 each year. During this time, you can switch to a different Medicare plan. Initial Enrollment Period (IEP): Around your 65th birthday. |⏳ INDIVIDUAL & FAMILY ACA MARKETPLACE PLANS: Generally November 1 – January 15 for the following year’s coverage. December 15: Deadline for coverage to start January 1. January 1: Coverage begins for those who enrolled by the December 15 deadline. January 15: The final deadline to enroll for coverage that typically begins February 1. |⏳ EMPLOYER SPONSORED PLANS: Enrollment periods are set by your employer and often occur in the fall. |⏳ MEDICAID & CHILDREN’S HEALTH INSURANCE PROGRAM (CHIP): You can enroll at any time of the year. |⏳ SPECIAL ENROLLMENT PERIODS (SEPs): You may qualify for an SEP outside the regular Open Enrollment Period if you have certain qualifying life events, such as getting married, having a baby, or losing other health coverage. |⏳ DON’T WAIT! ASK US YOUR QUESTIONS EARLY! |⏳

4 Common Health Insurance Plans

4 MOST COMMON HEALTH INSURANCE PLANS

4 Common Health Insurance Plans

Best 4 Most Common Health Insurance Plans

Navigating health insurance options can be overwhelming. Plans vary significantly. Some offer complete doctor choice (PPOs), while others restrict you to a network (HMOs). Costs also vary: some individuals have higher monthly premiums, while others incur higher out-of-pocket expenses. Finding the right plan for your family requires careful consideration and planning. HMOs often cost less monthly, but you must see doctors in the plan’s network. You may need a referral to see a specialist.

PPOs let you see any doctor you want. You can see doctors in or out of network, but out-of-network care usually costs more. EPOs are like a mix of HMOs and PPOs. They offer some freedom and cost less than PPOs, but you may not need a referral to see a specialist. POS plans are similar to PPOs. They let you see doctors outside the network, but you’ll pay more. [4 Most Common Health Insurance Plans]

Here’s a more in-depth look.

HMO (Health Maintenance Organization)

The Network:

  • HMOs have a network of doctors, hospitals, and other healthcare providers who have agreed to provide services at a specific cost to HMO members. [4 Most Common Insurance Plans]
  • When you join an HMO, you’re essentially joining this “club” and agreeing to get your care exclusively from these providers. [4 Most Common Health Insurance Plans]

Your Guide (PCP):

  • You choose a primary care physician (PCP) from the HMO’s network. This doctor becomes your main point of contact for all your healthcare needs.   [4 Most Common Health Insurance Plans]
  • Your PCP is like your guide within the HMO system. They provide routine checkups, treat common illnesses, and coordinate your care if you need to see a specialist.   [4 Most Common Health Insurance Plans]

Getting a Pass (Referral):

  • If you need to see a specialist, such as a cardiologist or dermatologist, you usually need a referral from your PCP.   [4 Most Common Health Insurance Plans]
  • This referral acts like a “pass” to see the specialist within the network. It helps ensure you see the appropriate specialist for your condition and helps control costs. [4 Most Common Health Insurance Plans]

Staying Within the Club (No Out-of-Network Coverage):

  • Besides emergencies, HMOs generally don’t cover any services you receive from providers outside their network.   [4 Most Common Health Insurance Plans]
  • You’ll pay the full cost if you go outside the network for non-emergency care. [4 Most Common Health Insurance Plans]

Keeping Costs Down:

  • HMOs often have the lowest monthly premiums among health insurance plans because they negotiate lower rates with their network providers and emphasize preventive care to help you stay healthy.   [4 Most Common Health Insurance Plans]
  • You’ll typically have copayments for doctor visits and prescriptions.   [4 Most Common Health Insurance Plans]

Here’s an example of how an HMO works:

Let’s say you have an HMO and sprain your ankle. You would first see your PCP, who might treat you directly or refer you to an orthopedist within the HMO network. If you decide to see an orthopedist outside the network without a referral, you’ll likely have to pay the full cost of the visit yourself. 4 Most Common Health Insurance Plans]

In a nutshell, HMOs focus on:

  • Cost-effectiveness: Lower premiums and copayments.  Most Common Health Insurance Plans]
  • Preventive care: Regular checkups and screenings.  [ Most Common Health Insurance Plans]
  • Coordinated care: Your PCP guides your healthcare journey.  [4 Most Common Health Insurance Plans]

PPO (Preferred Provider Organization)

A PPO, or Preferred Provider Organization, is a type of health insurance plan that offers much flexibility when choosing your doctors and hospitals. Think of it like a VIP pass to a network of healthcare providers, with the freedom to go outside it.  [4 Most Common Health Insurance Plans]

Here’s how it works: 

The Network:

  • PPOs have a network of doctors, hospitals, and other healthcare providers who have agreed to provide services to PPO members at discounted rates.   [4 Most Common Health Insurance Plans]
  • These providers are considered “preferred” because you pay less when you use them.   [4 Most Common Health Insurance Plans]

Freedom of Choice:

  • Unlike HMOs, you don’t need a primary care physician (PCP) or referrals to see specialists. You can go directly to any doctor or hospital you want, whether they’re in-network or not.   [4 Most Common Health Insurance Plans]
  • PPOs allow you to choose your preferred providers and seek specialized care.   [4 Most Common Health Insurance Plans]

Cost Variations:

  • While you can see any provider, you’ll pay less when you stay within the PPO’s network. In-network: You’ll typically have copayments or coinsurance for services.   [4 Most Common Health Insurance Plans]
  • Out-of-network: You’ll usually pay a deductible and a higher percentage of the cost. The PPO will still cover some expenses, but you’ll have higher out-of-pocket costs.   [4 Most Common Health Insurance Plans]

Premiums and Deductibles:

  • PPOs tend to have higher monthly premiums than HMOs or EPOs because they offer greater flexibility and coverage.   [4 Most Common Health Insurance Plans]
  • Deductibles can vary, but they may be lower than EPOs.  [4 Most Common Health Insurance Plans]

Here’s an example:

Imagine you have a PPO and need to see a dermatologist. You can see a dermatologist within your PPO’s network and pay a lower copay. Or, you can see a dermatologist outside the network. The PPO will still cover some of the cost, but you’ll likely pay a deductible and a higher percentage of the bill.   [4 Most Common Health Insurance Plans]

In essence, PPOs offer:

  • Flexibility: See any doctor or specialist, with or without a referral. 
  • Choice: Access to a vast network of providers. 
  • Coverage: Some coverage for out-of-network care. 
  • Higher Costs: Higher premiums and potentially higher out-of-pocket costs for out-of-network services.

EPO (Exclusive Provider Organization)

The Network:

  • EPOs have a network of doctors, hospitals, and other healthcare providers they’ve contracted with. 
  • You must get your care from within this network to cover your expenses. 
  • This network is usually larger than an HMO network but smaller than a PPO network.

Choosing a Doctor:

  • Unlike HMOs, EPOs typically don’t require you to choose a primary care physician (PCP). 
  • You can see any specialist within the network directly without a referral, offering more flexibility and faster access to specialized care. 

Out-of-Network Care:

  • EPOs generally don’t cover any services received from out-of-network providers except in emergencies. 
  • You’ll pay the full cost if you go outside the network for non-emergency care. 

Costs:

  • EPOs usually have lower monthly premiums than PPOs, making them a more affordable option. 
  • However, they might have higher deductibles than other plans.
  • You’ll typically have set copayments or coinsurance for in-network services.

Here’s an example of how an EPO works:

Imagine you have an EPO plan and need to see a cardiologist. You can schedule an appointment directly with any cardiologist in your EPO’s network without a referral from a PCP. However, if you see a cardiologist outside the network, your EPO plan won’t cover the cost, and you’ll have to pay the entire bill yourself.   [4 Most Common Health Insurance Plans]

In essence, an EPO offers a balance between cost and flexibility: 

  • Cost Savings: Lower premiums compared to PPOs. 
  • Flexibility: Direct access to in-network specialists. 
  • Restriction: No coverage for out-of-network care (except emergencies).

POS (Point of Service)

A POS (Point of Service) plan is a type of health insurance that combines features of HMOs and PPOs. It offers more flexibility than an HMO but less than a PPO. Think of it as a hybrid plan that lets you choose your approach to healthcare at the “point of service” – when you need care.   [4 Most Common Health Insurance Plans]

Here’s how it works:

The Network:

  • POS plans have a network of doctors, hospitals, and other healthcare providers like HMOs and PPOs.   [4 Most Common Health Insurance Plans]
  • You’ll generally pay less when you use in-network providers.   [4 Most Common Health Insurance Plans]

Your Home Base (PCP):

  • Like an HMO, you usually need to choose a primary care physician (PCP) from the network. 
  • Your PCP coordinates your care and provides referrals if you need to see a specialist. 

Flexibility at the Point of Service:

Here’s where the “point of service” comes in. When you need care, you have a choice:

  • Stay in-network: Follow the HMO model. Get a referral from your PCP to see an in-network specialist. This usually results in lower costs. 
  • Go out-of-network: You can see a specialist outside the network without a referral. This gives you more flexibility but often comes with higher out-of-pocket costs. 

Cost Variations:

  • In-network: You’ll typically have copayments or coinsurance for services. 
  • Out-of-network: Similar to a PPO, you’ll usually pay a deductible and a higher percentage of the cost. However, the POS plan may still cover some of the expenses. 

Premiums and Deductibles:

  • POS plans generally have moderate premiums, falling between HMOs (lower) and PPOs (higher).
  • Deductibles can vary.

Here’s an example:

Let’s say you have a POS plan and need to see a physical therapist. You could ask your PCP for a referral to an in-network physical therapist and pay a lower copay. Or you could see a physical therapist outside the network without a referral, but you’d likely pay a deductible and a larger share of the cost. [4 Most Common Health Insurance Plans]

In essence, POS plans offer:

  • A balance of cost and choice: A middle ground between HMOs and PPOs. 
  • Coordinated care: A PCP to guide your healthcare. 
  • Flexibility: The option to go out of network when needed.

Important Note: These are just the basics. Each plan has its own specific rules and costs. It’s best to compare plans carefully and ask questions to make sure you understand what you’re getting.

Understanding the Complexities of Health Insurance

Navigating the complexities of health insurance can be challenging, with numerous plans and unfamiliar terminology. A health insurance agent can simplify this process by providing clear explanations and answering your questions. This expert guidance will help you make informed decisions and choose the most suitable plan for your family. [4 Most Common Health Insurance Plans]

Navigating the Health Insurance Marketplace

The Health Insurance Marketplace can be a valuable resource for finding health insurance, but the abundance of choices and complex application process can be daunting. To navigate this effectively, consider working with a health insurance agent who can identify plans that match your needs and budget and help with the application. This personalized guidance can save you time and frustration. [4 Most Common Health Insurance Plans]

Finding Plans that Meet Your Specific Needs

Individual healthcare needs vary greatly, whether managing a specific health condition or finding coverage for a large family. A health insurance agent can help you navigate these complexities and find a plan that covers your doctors, prescriptions, and unique requirements. With their expertise, you can secure the appropriate coverage for your circumstances. [4 Most Common Health Insurance Plans]

Getting Help with the Application Process

Many people find the health insurance application process daunting because of complex forms and the potential for errors that can delay coverage. Fortunately, a local health insurance agent can simplify this process by guiding you through the application, ensuring accuracy, and preventing costly mistakes. Their expertise can speed up your application and help ensure timely coverage. [4 Most Common Health Insurance Plans]

Comparing Plans from Different Insurance Companies

The health insurance market is crowded with different companies and plans, making it difficult to compare coverage and costs effectively. Fortunately, a health insurance agent can clarify these options and help you navigate the complexities to find the best plan. Their expertise can save you time and money while ensuring you get coverage. [4 Most Common Health Insurance Plans]

Understanding the Costs of Health Insurance

Health insurance involves various costs, including monthly premiums, deductibles you pay before coverage kicks in, and copayments for doctor visits. To navigate these costs, consider consulting a health insurance agent who can explain them and help you find a plan that fits your budget. [4 Most Common Health Insurance Plans]

Staying Up-to-Date on Changes in Health Insurance

Health insurance regulations and offerings constantly evolve, making it hard to stay informed about the latest changes. A health insurance agent can keep you up to date on relevant updates and ensure your family has the best coverage. Their expertise allows you to adapt to changes and maintain optimal health insurance protection. [4 Most Common Health Insurance Plans]

Getting Help with Claims and Appeals

Dealing with denied health insurance claims can be incredibly frustrating and time-consuming. A health insurance agent can help you understand the reason for the denial and guide you through the appeals process, potentially saving you significant time and money. Their advocacy can be invaluable in resolving claim disputes and ensuring you receive the coverage you deserve. [4 Most Common Health Insurance Plans]

Finding Discounts and Subsidies

Reducing health insurance costs is a priority for many families, and financial assistance programs can help. A local health insurance agent can guide you through the options to help you secure the most affordable coverage for your family and maximize your potential savings. [4 Most Common Health Insurance Plans]

Getting Personalized Advice and Support

A health insurance agent acts as your trusted advisor, providing personalized guidance, answering your questions, and empowering you to make informed decisions about your healthcare coverage. Choosing the right health insurance is crucial for your family’s well-being, and an agent can simplify this process by explaining your options and helping you find the best plan for your needs and budget. [4 Most Common Health Insurance Plans]With financial help,

4 out of 5 customers can find a health plan for $10 or less. I’m here to help! Call me today and get covered for 2025.

OUR CLIENT REVIEWS

Posted on Google Google
Kathy Hanner profile picture
Kathy Hanner
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Steve made our insurance shopping so easy!!a pleasure to work with!
Posted on Google Google
Joan Wallace Germain profile picture
Joan Wallace Germain
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We were completely overwhelmed trying to find health insurance for our daughter as she aged off our plan. There were so many options and we needed something that would keep her current doctors and medical treatments without interruption. Steve was incredibly patient and thorough. He walked us through the different plans, explained the differences clearly, and found a Florida Blue plan that worked for everything we needed. Because of his help, our daughter was able to seamlessly continue treatment with no gap in coverage. We are so grateful for his guidance during a stressful time. Highly recommend!
Posted on Google Google
K DeNisco profile picture
K DeNisco
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Steve Turner helped me tremendously in navigating the complicated Medicare process. He also helped us get a better Dental Insurance package. We would highly recommend his insurance services!
Posted on Google Google
Tammy Mitchell profile picture
Tammy Mitchell
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Excellent experience! Steve was knowledgeable, responsive, and made the process easy. He helped us find a great temporary health insurance plan for our daughter to bridge the gap until open enrollment. I really appreciated his guidance and would highly recommend him.
Posted on Google Google
Rosemary Dragotta profile picture
Rosemary Dragotta
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
So knowledgeable and helpful !!!
Posted on Google Google
Marilyn Wirsz profile picture
Marilyn Wirsz
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Super responsive and easy to work with! He helped me understand my options with the matketplace and we're looking forward to getting set up with my husband's medicare soon. Great agent - you won't regret making the call!
Posted on Google Google
Cheryl Bowman profile picture
Cheryl Bowman
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Steve responded quickly to my call. I had retired and lost my dental insurance coverage for me and my husband. Steve went over all options in a very professional and detailed manner. It was truly a good experience. He does handle other types of insurance. I would recommend him for anyone.
Posted on Google Google
kristin zangrilli profile picture
kristin zangrilli
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Steve makes the painful process of finding a healthcare plan that’s right for you or a loved one easy. Absolutely worth the call.

CONTACT STEVE TURNER, LICENSED INSURANCE AGENT & BROKER

Questions? Call, text, or book a time below; I answer calls and emails 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.

EMAIL ME: 24×7


OFFICE LOCATION

Address: 14502 N Dale Mabry Hwy, Suite 200, Tampa, FL 33618

Website: steveturnerinsurancespecialist.com

Email: [email protected]

Phone and Text: +1-813-388-8373

Business Hours:

Monday: 7:00 a.m. / 8:00 p.m.

Tuesday: 7:00 a.m. / 8:00 p.m.

Wednesday: 7:00 a.m. / 8:00 p.m.

Thursday: 7:00 a.m. / 8:00 p.m.

Friday: 7:00 a.m. / 8:00 p.m.

Saturday: 7:00 a.m. / 8:00 p.m.

Sunday: 7:00 a.m. / 8:00 p.m.

HEALTH INSURANCE POSTS
INSURANCE OFFERINGS
4 Common Health Insurance Plans

PRESCRIPTION DRUGS

PRESCRIPTION DRUG INSURANCE

LIFE INSURANCE

LIFE INSURANCE

DISABILITY INSURANCE

DISABILITY INSURANCE

DENTAL INSURANCE
DENTAL INSURANCE

GROUP HEALTH INSURANCE
GROUP HEALTH INSURANCE

ACCIDENT INSURANCE
ACCIDENT INSURANCE

LONG TERM CARE INSURANCE
Long Term Care Insurance

MEDICAID INSURANCE

MEDICAID INSURANCE

MEDICARE INSURANCE
MEDICARE INSURANCE

MEDICARE PART A INSURANCE
MEDICARE PART A INSURANCE

MEDICARE PART B INSURANCE
MEDICARE PART B INSURANCE

MEDICARE PART C INSURANCE
MEDICARE PART C INSURANCE

MEDICARE PART D INSURANCE
MEDICARE PART D INSURANCE

MEDICARE PLAN G INSURANCE
MEDICARE PLAN G INSURANCE

MEDICARE PLAN N INSURANCE
MEDICARE PLAN N INSURANCE

SERVICE AREA


  • USA

  • Alabama
  • Colorado

  • Florida
  • Alachua County FL
  • Baker County FL
  • Bay County FL
  • Bradford County FL
  • Brevard County FL
  • Broward County FL
  • Calhoun County FL
  • Charlotte County FL
  • Citrus County FL
  • Clay County FL
  • Collier County FL
  • Columbia County FL
  • DeSoto County FL
  • Dixie County FL
  • Duval County FL
  • Jacksonville FL
  • Escambia County FL
  • Flagler County FL
  • Franklin County FL
  • Gadsden County FL
  • Gilchrist County FL
  • Glades County FL
  • Gulf County FL
  • Hamilton County FL
  • Hardee County FL
  • Hendry County FL
  • Hernando County FL
  • Highlands County FL
  • Hillsborough County FL
  • Apollo Beach FL
  • Balm FL
  • Bealsville FL
  • Bloomingdale FL
  • Brandon FL
  • Carrollwood FL
  • Cheval FL
  • Citrus Park FL
  • Dover FL
  • Durant FL
  • East Lake-Orient Park FL
  • Egypt Lake-Leto FL
  • Fish Hawk FL
  • Fuller Heights FL
  • Gibsonton FL
  • Keystone FL
  • Lake Magdalene FL
  • Lithia FL
  • Lutz FL
  • Mango FL
  • Northdale FL
  • Palm River-Clair Mel FL
  • Pebble Creek FL
  • Plant City FL
  • Progress Village FL
  • Riverview FL
  • Ruskin FL
  • Seffner FL
  • Sun City FL
  • Sun City Center FL
  • Sydney FL
  • Tampa FL
  • New Tampa FL
  • Ybor City FL
  • Thonotosassa FL
  • Town ‘n’ Country FL
  • University FL
  • Valrico FL
  • Westchase FL
  • Wimauma FL
  • Holmes County FL
  • Indian River County FL
  • Jackson County FL
  • Jefferson County FL
  • Lafayette County FL
  • Lake County FL
  • Lee County FL
  • Leon County FL
  • Levy County FL
  • Liberty County FL
  • Madison County FL
  • Manatee County FL
  • Marion County FL
  • Martin County FL
  • Miami-Dade County FL
  • Miami FL
  • Monroe County FL
  • Nassau County FL
  • Okaloosa County FL
  • Okeechobee County FL
  • Orange County FL
  • Orlando FL
  • Osceola County FL
  • Palm Beach County FL
  • Pasco County FL
  • Aripeka FL
  • Bayonet Point FL
  • Beacon Square FL
  • Connerton FL
  • Crystal Springs FL
  • Dade City FL
  • Dade City North FL
  • Elfers FL
  • Heritage Pines FL
  • Holiday FL
  • Hudson FL
  • Jasmine Estates FL
  • Lacoochee FL
  • Land O’ Lakes FL
  • Meadow Oaks FL
  • Moon Lake FL
  • New Port Richey East FL
  • New Port Richey FL
  • Odessa FL
  • Pasadena Hills FL
  • Port Richey FL
  • Quail Ridge FL
  • River Ridge FL
  • Saint Leo FL
  • San Antonio FL
  • Seven Springs FL
  • Shady Hills FL
  • Trilby FL
  • Trinity FL
  • Wesley Chapel FL
  • Zephyrhills FL
  • Zephyrhills North FL
  • Zephyrhills South FL
  • Zephyrhills West FL
  • Pinellas County FL
  • Bardmoor FL
  • Bay Pines FL
  • Bear Creek FL
  • Belleair Beach FL
  • Belleair Bluffs FL
  • Belleair FL
  • Belleair Shore FL
  • Clearwater FL
  • Dunedin FL
  • East Lake FL
  • Feather Sound FL
  • Greenbriar FL
  • Gulfport FL
  • Harbor Bluffs FL
  • Indian Rocks Beach FL
  • Indian Shores FL
  • Kenneth City FL
  • Largo FL
  • Lealman FL
  • Madeira Beach FL
  • North Redington Beach FL
  • Oldsmar FL
  • Palm Harbor FL
  • Pinellas Park FL
  • Redington Beach FL
  • Redington Shores FL
  • Ridgecrest FL
  • Safety Harbor FL
  • Saint Petersburg FL
  • Seminole FL
  • South Highpoint FL
  • St. Pete Beach FL
  • Tarpon Springs FL
  • Tierra Verde FL
  • Treasure Island FL
  • West Lealman FL
  • Polk County FL
  • Lakeland FL
  • Putnam County FL
  • Santa Rosa County FL
  • Sarasota County FL
  • Sarasota FL
  • Seminole County FL
  • St. Johns County FL
  • St. Lucie County FL
  • Sumter County FL
  • The Villages FL
  • Suwannee County FL
  • Taylor County FL
  • Union County FL
  • Volusia County FL
  • Wakulla County FL
  • Walton County FL
  • Washington County FL

  • Georgia

  • North Carolina

  • South Carolina

  • Tennessee

  • Texas

MEDICARE STATEMENT

We do not offer every plan available in your area. Currently, we represent 7 organizations that offer 70 products in your area. Please get in touch with Medicare.gov or 1-800-MEDICARE for information on all your options.

Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.

There’s no one-size-fits-all answer. Carefully consider your health status, expected medical needs, prescription drugs, budget, preferred doctors and hospitals, and how comfortable you are with network rules. During the Annual Enrollment Period, you can use the Medicare Plan Finder at Medicare.gov to research plans available in your Florida county, compare costs and benefits, and get free, unbiased counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program at floridashine.org or 1-800-963-5337. You can also call 1-800-MEDICARE (1-800-633-4227; TTY 1-877-486-2048), 24 hours a day, 7 days a week.

SOCIAL SHARE

Steve Turner

Steve Turner Round Headshot V01 1254

Steve Turner, CLU®, REBC® Licensed Florida health insurance agent · License W333468

Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals NABIP®, the preeminent organization for health insurance and employee benefits professionals, and works diligently to ensure all Americans have access to high-quality, affordable healthcare and related services. Steve also holds the prestigious Registered Employee Benefits Consultant® (REBC®) designation. Steve also holds the “Chartered Life Underwriter” designation (CLU®), a professional credential for individuals specializing in life insurance and estate planning. The American College of Financial Services confers it. For over 10 years, Steve has helped individuals, families, Medicare beneficiaries, and small businesses find the right coverage to meet their needs. Steve has earned 180+ Google reviews from happy clients.

Steve Turner is a licensed agent appointed by Florida Blue.

Verify license · Read reviews · About Steve