

How to Choose a Medicare Advantage Plan: 7 Steps to Compare Plans in 2027
Reviewed by Steve Turner, CLU, REBC · Florida License W333468 · NPN 18030539 · November 2026
Date Published: 2026-11-21
Updated: 2026-11-21
To choose a Medicare Advantage plan, start with what can’t change: your doctors and your prescriptions. Narrow your options to plans that include both, then compare what each would cost you in a healthy year and a bad year, and check the rules that affect how you get care. Don’t let a $0 premium or a long list of extras be the deciding factor. Here’s the 7-step process I use with clients comparing Medicare Advantage plans in Tampa, plus 15 questions to ask before you enroll. Annual Enrollment ends December 7.
Key takeaways
- Doctors and drugs first. A plan that doesn’t include your doctors or covers your drugs poorly is the wrong plan, whatever it costs.
- Compare total yearly cost, not just the premium: Part B, premium, copays, drug costs and the out-of-pocket limit.
- Check the rules: HMO or PPO, referrals, prior authorization and travel coverage.
- Extras are a tiebreaker. Dental, vision and OTC benefits matter only if you’ll use them and the dollar limits are meaningful.
- You can fix a mistake. If you’re in a plan on January 1, you get one more change between January 1 and March 31.
Step 1: Decide whether Medicare Advantage fits you
Before comparing plans, make sure Medicare Advantage is the right type of coverage. It usually fits people who:
- Are comfortable using a network of doctors and hospitals
- Want lower monthly premiums and are OK with copays when they get care
- Want drug coverage and extras like dental in one plan
- Spend most of the year in their home area
If you travel a lot, want to see any doctor who takes Medicare, or want predictable costs, also compare a Medicare Supplement plan. See Medigap vs. Medicare Advantage.
Step 2: Make your list
Write down:
- Every doctor you want to keep, including specialists
- The hospitals you’d want to use (Tampa General, BayCare, AdventHealth, HCA Florida, Moffitt, or others)
- Every prescription, with the dose and how often you take it
- Your pharmacy, or whether you’d use mail order
- Care you expect next year, like a planned surgery, therapy, or regular specialist visits
- Where you’ll be: your home ZIP code and any months you spend outside Florida
Step 3: Narrow plans by network
Remove any plan that doesn’t include your must-have doctors and hospitals. Check each plan’s provider directory, then call your doctors’ offices to confirm they’ll accept the plan in 2027. Directories aren’t always up to date, and some 2027 plans have narrower networks than last year’s.
Also decide between plan types:
| HMO | PPO | |
|---|---|---|
| Out-of-network care | Not covered, except emergencies and urgent care | Covered, at a higher cost |
| Referrals to specialists | Usually required | Usually not required |
| Premiums | Often $0 | Sometimes $0, sometimes higher |
| Good fit for | People whose doctors are all in one network | People who want flexibility or spend time out of state |
Step 4: Check your drugs
Enter every prescription in Medicare Plan Finder at Medicare.gov, or have me do it. For each plan, check:
- Is each drug on the formulary (the plan’s drug list)?
- Which tier is it on, and what’s the copay?
- Are there restrictions, like prior authorization or step therapy?
- Is your pharmacy preferred? Preferred pharmacies usually cost less.
In 2027, your drug costs are capped at $2,400 for covered drugs, but a plan with your drugs on lower tiers can save you much more than that. See Medicare Part D.
Step 5: Compare total yearly cost
Add up what each plan would cost you in a healthy year and a bad year:
- Part B premium: $209.40 a month in 2027 for most people, unless a plan’s Part B giveback lowers it
- Plan premium times 12
- Copays for the care you expect: primary care, specialists, labs, imaging
- Drug costs from Plan Finder
- Worst case: add the plan’s out-of-pocket limit (up to $9,850 in-network in 2027)
A $0-premium plan with a $7,000 out-of-pocket limit can cost thousands more in a bad year than a plan with a small premium and a $4,000 limit. See How much does Medicare Advantage cost? For worked examples.
Step 6: Check the plan rules
- Prior authorization: which services need approval first? Ask about anything you expect to need.
- Referrals: Do you need a referral to see a specialist?
- Travel: are you covered for routine care outside Florida, or only emergencies?
- Star rating: Medicare rates plans from 1 to 5 stars on quality and member experience. Higher is better, though a lower-rated plan with your doctors may still be the right fit.
Step 7: Use extras as the tiebreaker
If two plans are close, compare extras you’ll actually use:
- Dental: is it preventive only, or does it cover fillings, crowns, and dentures? What’s the yearly limit?
- Vision and hearing: how much does it cover for glasses or hearing aids?
- OTC allowance, fitness, transportation: will you use them?
- Part B giveback: how much does it lower your Part B premium? See Medicare Advantage give money back.
15 questions to ask before you enroll
Ask these of any plan, or any agent helping you compare:
Doctors and hospitals
- Are my doctors and hospitals in-network for 2027?
- Is it an HMO or a PPO?
- Do I need a referral to see a specialist?
Costs 4. What is the monthly premium? 5. What will I pay for primary care, specialists, labs, and imaging? 6. What is the most I could pay in one year (the out-of-pocket limit)? 7. What does a hospital stay cost, and for how many days?
Prescriptions 8. Are all my medicines on the drug list, and what tier is each one? 9. Which pharmacies are preferred?
Extras 10. What dental, vision, and hearing care is covered, and what are the dollar limits? 11. Which other extras come with the plan, and will I use them?
Rules and quality 12. Which services need prior authorization? 13. What is the plan’s star rating? 14. Am I covered when I travel?
The future 15. If this plan doesn’t work out, when can I change it?
Questions to ask the agent
- Are you licensed in Florida, and which insurance companies are you appointed with? An agent who represents several companies can compare more plans.
- Do I pay anything for your help? You shouldn’t. Agents are paid by the insurance company, and your premium is the same either way.
- Will you help me after I enroll with claims, billing, or denials?
- Will you tell me if a plan you don’t offer would fit me better? You can also check Medicare Plan Finder yourself.
Red flags to watch for
- Pressure to enroll today, or claims that a plan is “only available this week”
- Unsolicited calls offering money, gifts, or “Medicare benefits” you didn’t ask about
- Anyone asking for your Medicare number before you’ve decided to enroll
- Comparing only the premium and extras without checking your doctors and drugs
- Being told you’ll lose Medicare if you don’t switch
What to have ready when you compare plans
- Your red, white and blue Medicare card
- Your list of doctors, hospitals and prescriptions (with doses)
- Your current plan’s Annual Notice of Change, if you have one
- Any letters about Medicaid, Extra Help or a Medicare Savings Program
If you choose the wrong plan
You have more chances to fix it than most people realize:
- Until December 7: change plans as often as you like; the last choice counts
- January 1 to March 31: if you’re in a Medicare Advantage plan on January 1, you can switch once to another Medicare Advantage plan or go back to Original Medicare
- Special Enrollment Periods: if you move, your plan leaves your area, or you qualify for Extra Help, you may be able to switch at other times
See Can I change Medicare Advantage plans? for every enrollment period.
Choosing a Medicare Advantage plan in Tampa
Tampa Bay has dozens of Medicare Advantage plans, so the hard part isn’t finding one; it’s narrowing them down. Networks are the biggest difference here. One plan can include one major health system and exclude another, and several plans changed networks or left Florida counties for 2027. If your plan is ending, see Are Medicare Advantage plans going away? for your deadlines and options.
How I help
- I run your doctors, hospitals, and prescriptions against every plan in your ZIP code.
- Show you the top choices side by side, with total yearly cost for a healthy year and a bad year.
- Answer all 15 questions for each plan, in writing if you’d like.
- Enroll you and help after with claims, billing, and next year’s review.
My help costs you nothing. Premiums are the same whether you enroll through me or directly with the plan.
How to choose a Medicare Advantage plan FAQs
How do I choose a Medicare Advantage plan?
Start with plans that include your doctors and cover your prescriptions. Then compare each plan’s total yearly cost, including the out-of-pocket limit, and check its rules for referrals, prior authorization, and travel. Use extras as a tiebreaker.
How do I compare Medicare Advantage plans side by side?
Use Medicare Plan Finder at Medicare.gov, enter your ZIP code and prescriptions, and compare plans’ premiums, drug costs, out-of-pocket limits, and star ratings. Then check networks with your doctors’ offices. An independent agent can do this for you.
What is the most important thing when choosing a Medicare Advantage plan?
Your doctors and prescriptions. A low-premium plan is a poor choice if your doctors aren’t in network or your drugs cost much more.
Should I choose an HMO or a PPO?
An HMO usually costs less but limits you to its network and requires referrals. A PPO lets you see out-of-network providers, but at a higher cost. PPOs often fit people who travel or want more choice.
Is a $0-premium Medicare Advantage plan a good choice?
It can be, but compare the out-of-pocket limit and copays. You still pay the Part B premium, and a $0-premium plan can cost more overall if you need a lot of care.
How many Medicare Advantage plans should I compare?
Narrow down to 2 to 4 plans that include your doctors and cover your drugs, then compare those in detail.
Does it cost anything to use an agent to choose a plan?
No. Licensed agents are paid by the insurance companies, and your premium is the same whether you enroll through an agent or directly with the plan.
Talk with Steve
Want help comparing Medicare Advantage plans before December 7? Call me at (813) 388-8373 or book a free review.
Related: Medicare Advantage plans in Tampa · How much does Medicare Advantage cost? · Medigap vs. Medicare Advantage · What does Medicare Advantage cover? · Can I change Medicare Advantage plans?
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, LICENSED INSURANCE AGENT & BROKER
Questions? Call, text, or book a time below; I answer calls and emails 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
EMAIL STEVE
OFFICE LOCATION
Address: 14502 N Dale Mabry Hwy, Suite 200, Tampa, FL 33618
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
More on Medicare Advantage
-

Does Medicare Advantage Cover the Part A Deductible? What You Pay Instead in 2027
By Steve Turner
• 2026-06-21
Medicare Advantage replaces the Part A deductible with its own hospital copays. Here’s what you’d pay for a hospital stay in 2027, and how it compares with Medigap. -

Are Medicare Advantage Plans Going Away? What’s Really Changing in 2027
By Steve Turner
• 2025-10-28
Medicare Advantage isn’t going away, but some plans are. Here’s what’s changing for 2027, how many Florida plans are ending, and what to do if yours won’t renew. -

How Much Does Medicare Advantage Cost in 2027? Premiums, Copays, and Limits
By Steve Turner
• 2026-07-05
Medicare Advantage often has a $0 premium, but it isn’t free. Here’s what you’ll pay in 2027: the Part B premium, copays, drug costs and the yearly out-of-pocket limit. -
Medicare Supplement vs. Advantage: Which Is Best in 2027?
By Steve Turner
• 2026-10-16
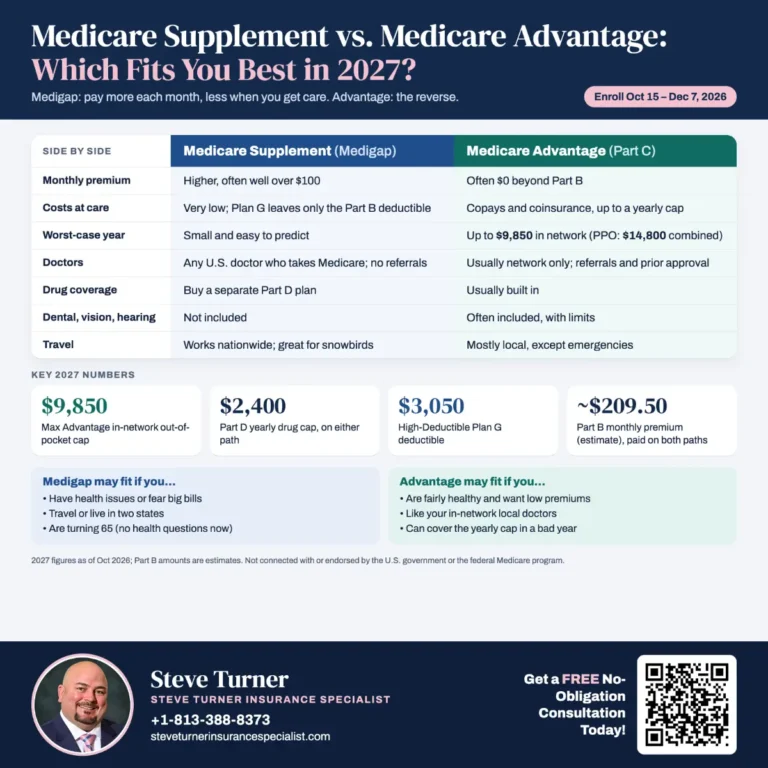
Medicare Supplement vs. Medicare Advantage in 2027: compare costs, doctor choice, out-of-pocket caps, and pros and cons to find the plan that fits you best. -

2027 Medicare Advantage Changes: What Floridians Need to Know
By Steve Turner
• 2026-10-13
Medicare Advantage vs. Original Medicare explained in plain English. Compare 2027 costs, coverage, doctor choice, and pros and cons to pick the right plan. -
Medicare Advantage 2027 FAQ: 150+ Answers for Florida
By Steve Turner
• 2025-07-10
2027 Medicare Advantage answers from a licensed Florida agent: $2,400 drug cap, $9,850 MOOP, Florida plan cuts, GLP-1 coverage, and how to compare plans.
Medicare plan availability differs by state and county. Steve Turner is licensed in AL, CO, FL, GA, NC, SC, TN, and TX.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
MEDICARE DISCLAIMER
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
Steve Turner
Steve Turner, CLU®, REBC® is licensed in AL, CO, FL, GA, NC, SC, TN, and TX · NPN 18030539 · Florida License W333468
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals NABIP®. Steve holds the Registered Employee Benefits Consultant® (REBC®) designation. Steve also holds the “Chartered Life Underwriter” designation (CLU®), a professional credential for individuals specializing in life insurance and estate planning, conferred by the American College of Financial Services. Since 2016 (over 10 years), Steve has helped individuals, families, Medicare beneficiaries, and small businesses find the right coverage to meet their needs. Steve has earned 180+ Google reviews from happy clients.
Steve Turner is a licensed agent appointed by Florida Blue in Florida.