

Medigap vs. Medicare Advantage: How to Choose in 2027
Reviewed by Steve Turner, CLU, REBC · Florida License W333468 · NPN 18030539 · November 2026
Date Published: 2026-11-20
Updated: 2026-11-20
Key takeaways
- Medigap: higher premium, low and predictable costs, any Medicare doctor nationwide, no referrals. You add a separate Part D drug plan.
- Medicare Advantage: low or $0 premium, a network (HMO or PPO), copays as you go, and often drug, dental, vision and hearing coverage in one plan.
- 2027 worst case with Medicare Advantage: up to $9,850 a year for in-network care (up to $14,800 combined in PPOs), plus up to $2,400 for drugs.
- Florida’s switching rules favor choosing carefully at 65. Your 6-month Medigap Open Enrollment is the only time you’re guaranteed a Medigap plan without health questions. Florida has no birthday rule.
- You don’t have to buy Medicare Advantage. It’s optional. Original Medicare alone has no yearly out-of-pocket limit, though, so most people add either Medigap or Medicare Advantage.
When you turn 65, you can choose one of two paths. Medicare Supplement (Medigap) works alongside Original Medicare. You pay a monthly premium, then very little when you get care, and you can see any doctor in the U.S. who accepts Medicare. Medicare Advantage replaces Original Medicare with a private plan. Premiums are often $0, but you use a network and pay copays as you go, up to a yearly limit. Neither one is right for everyone. Here’s how they compare in 2027, with the Florida rules that matter most.
The short answer
- Choose Medigap if you want predictable costs, want to keep any doctor or hospital that takes Medicare, travel, split the year between Florida and another state, or have health conditions that require regular care.
- Choose Medicare Advantage if keeping your monthly premium low matters most, your doctors are in a plan’s network, you’re comfortable with copays and prior authorization, and you value built-in extras like dental and vision.
How Medigap and Medicare Advantage work
Medicare Supplement (Medigap)
You keep Original Medicare (Parts A and B). Medicare pays first, then your Medigap plan pays most or all of what’s left. The plans are standardized by letter. For example, Plan G covers everything except the Part B deductible ($283 in 2026), and Plan N costs less but adds small copays. Medigap doesn’t cover prescriptions, so you add a Part D plan.
Medicare Advantage (Part C)
A private insurance company provides your Part A and Part B benefits under a contract with Medicare. Most plans include Part D drug coverage, and many add dental, vision, hearing, and fitness benefits. You use the plan’s network, pay copays or coinsurance for services, and the plan caps your yearly costs for covered medical care. Learn more about Medicare Part C.
With either path, you still pay your Part B premium ($202.90 a month in 2026 for most people).
Side-by-side comparison for 2027
| Medigap (with Original Medicare) | Medicare Advantage | |
|---|---|---|
| Monthly premium | Medigap premium + separate Part D premium | Often $0 or low (many include drugs) |
| Doctors and hospitals | Any provider in the U.S. that accepts Medicare | Plan network (HMO or PPO). Out-of-network care is limited or costs more |
| Referrals | Not needed | Often needed in HMOs |
| Prior authorization | Rarely (Original Medicare rules) | Common for hospital stays, imaging and specialty care |
| Costs when you get care | Little or none, depending on the plan letter | Copays and coinsurance until you reach the limit |
| Yearly out-of-pocket limit | None needed with Plan G (Plans K and L have their own limits) | Up to $9,850 in-network; up to $14,800 combined (PPO) |
| Drug coverage | Separate Part D plan (2027 cap: $2,400) | Usually included (same $2,400 cap) |
| Dental, vision, hearing | Not included (add a dental plan) | Often included, with limits |
| Travel | Works nationwide; Plans G and N pay 80% of foreign emergencies | Usually emergency-only outside your network area |
| Changes each year | Benefits stay the same; premiums can rise | Networks, copays and benefits can change every January |
| Switching later in Florida | Health questions usually required | Can switch plans every fall |
What your worst-case year looks like
This comparison matters most because premiums tell only half the story.
Medicare Advantage (2027):
- Premium: often $0
- Medical costs: up to your plan’s limit, as high as $9,850 in-network
- Drug costs: up to $2,400
- Worst case: up to about $12,250 plus any premium, every year you have heavy medical needs
Medigap Plan G (2027):
- Premium: higher, and varies by age, ZIP code, and company
- Medical costs: the Part B deductible (2027 amount not yet announced; $283 in 2026)
- Drug costs: up to $2,400 with your Part D plan
- Worst case: your yearly premiums + the Part B deductible + up to $2,400 for drugs, and nothing more for Medicare-covered care
In plain terms: Medicare Advantage costs less in a healthy year. Medigap costs less, and is far more predictable, in a year with a hospital stay, cancer treatment, or a chronic condition. I run both numbers using real quotes for your age and ZIP code.
Real-world scenarios
Healthy 65-year-old, local doctors, tight budget. Medicare Advantage often fits. A $0-premium plan with your doctors in-network keeps monthly costs low, and the out-of-pocket limit caps a bad year.
Florida snowbird, 6 months in Tampa and 6 months up north. Medigap usually fits better. It works with any Medicare provider in both states, while most Medicare Advantage networks are local, so routine care up north may not be covered.
Managing a chronic condition or seeing specialists. Medigap often costs less overall. You avoid repeated specialist copays and prior authorization, and you can see specialists without referrals.
Want dental and vision coverage, see few doctors. Medicare Advantage’s built-in extras can be worth a lot. Compare the dental limits carefully, though. Many cover cleanings but cap major work.
Have both Medicare and Medicaid. A dual-eligible special needs plan (D-SNP) may cover more at little or no cost. See Medicare & Medicaid help.
Medicare Advantage pros and cons
Pros
- Low or $0 monthly premiums
- Drug coverage usually included
- Extra benefits such as dental, vision, hearing, and fitness
- A yearly limit on medical costs
Cons
- Network rules. Your doctor or hospital can leave the network
- Prior authorization and referrals
- Copays add up when you need regular care
- Benefits and networks can change every year
- Limited coverage when you travel
Medigap pros and cons
Pros
- Any doctor or hospital in the U.S. that accepts Medicare
- Predictable costs, with little or nothing owed at the doctor
- No referrals and little prior authorization
- Benefits are standardized and don’t change year to year
- Works when you travel or live in two states
Cons
- Higher monthly premium
- Separate Part D plan needed
- No dental, vision, or hearing coverage
- Hard to buy later in Florida if your health changes
Do I need Medicare Advantage?
No. Medicare Advantage is optional. But Original Medicare has no yearly out-of-pocket limit: you’d pay the Part A deductible ($1,736 per benefit period in 2026) and 20% of most Part B costs, with no cap. That’s why most people add either a Medigap plan or a Medicare Advantage plan, not both. You can’t use Medigap to pay Medicare Advantage costs.
Switching between them in Florida
This is the most important part of the decision.
- Medigap Open Enrollment: 6 months starting the month you turn 65 or older and enroll in Part B. During this window, companies must sell you any Medigap plan at standard rates, regardless of your health.
- After that window, Medigap companies can ask health questions and decline you. Florida has no birthday rule, so you can’t switch Medigap plans each year without health questions.
- Trial rights: if you join Medicare Advantage when you first turn 65 and leave within 12 months, you can buy a Medigap plan without health questions. If you drop Medigap to try Medicare Advantage for the first time, you can generally return to your same Medigap plan within 12 months.
- Other guaranteed-issue situations, such as your Medicare Advantage plan leaving your area, give you 63 days to buy certain Medigap plans without health questions.
- Switching Medicare Advantage plans: you can change plans every year from October 15 to December 7. Between January 1 and March 31, you can switch to a different Medicare Advantage plan or return to Original Medicare once. See when you can change Medicare Advantage plans.
What this means: going from Medigap to Medicare Advantage is easy. Going from Medicare Advantage back to Medigap usually isn’t, unless you’re within a trial or guaranteed-issue window. If you think you’ll want Medigap later, starting with it at 65 keeps your options open.
Five questions to answer before you choose
- Are your doctors and hospitals in the Medicare Advantage plan’s network, and will you be in Tampa year-round?
- Could you comfortably pay up to $9,850 in a bad year?
- How often do you see specialists or need tests?
- How much do you value dental, vision, and hearing benefits?
- If your health changes, will you want the freedom to switch to Medigap later?
How I help Tampa retirees decide
- Check your doctors and drugs against Medicare Advantage networks and Part D formularies.
- Get quotes for Medigap Plans G and N from several companies for your age and ZIP code.
- Compare total yearly costs for a healthy year and a worst-case year, side by side.
- Enroll and review every fall, so you know if your plan’s network or costs change.
My help costs you nothing. Premiums are the same whether you enroll through me or directly with the company. I’m licensed in Florida, Alabama, Colorado, Georgia, North Carolina, South Carolina, Tennessee, and Texas.
Medigap vs. Medicare Advantage FAQs
Is Medigap or Medicare Advantage cheaper?
Medicare Advantage usually has a lower monthly premium. Medigap usually costs less in a year when you need a lot of care. The cheaper option depends on your health, your doctors, and how much risk you’re comfortable with.
Can I have both Medigap and Medicare Advantage?
No. Medigap only works with Original Medicare. It’s illegal for a company to sell you a Medigap policy if you’re in a Medicare Advantage plan unless you switch back to Original Medicare.
Can I switch from Medicare Advantage to Medigap later?
You can apply at any time, but in Florida the company can ask health questions and decline you unless you’re in Medigap Open Enrollment, a 12-month trial, or another guaranteed-issue situation.
What is the Medicare Advantage out-of-pocket limit for 2027?
Plans can’t set a yearly limit above $9,850 for in-network covered services, or $14,800 for in- and out-of-network care combined in PPO plans. Many plans set lower limits. Drug costs count toward a separate $2,400 Part D cap.
Which is better for Florida snowbirds?
Usually Medigap, because it works with any Medicare provider in any state. Most Medicare Advantage plans cover only emergency and urgent care outside the plan’s service area.
Do Medicare Advantage plans include dental and vision?
Many do, but coverage limits vary widely. With Medigap, you can add a standalone dental plan.
When can I change my choice?
You can switch Medicare Advantage plans or return to Original Medicare from October 15 to December 7 each year, and make one change between January 1 and March 31. Buying a Medigap plan outside your open enrollment usually requires health questions in Florida.
Talk with Steve
Not sure which path fits you? Call me at (813) 388-8373 or book a free review. I’ll compare Medigap and Medicare Advantage options based on your doctors, prescriptions, and budget.
Learn More: Medicare Advantage
Related: Medicare Advantage plans in Tampa · Medicare Supplement plans · Medicare vs. Medicare Advantage · 2027 Medicare Advantage changes · Can I change Medicare Advantage plans?
OUR CLIENT REVIEWS


CONTACT STEVE TURNER, LICENSED INSURANCE AGENT & BROKER
Questions? Call, text, or book a time below; I answer calls and emails 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
EMAIL STEVE
OFFICE LOCATION
Address: 14502 N Dale Mabry Hwy, Suite 200, Tampa, FL 33618
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7:00 a.m. / 8:00 p.m.
Tuesday: 7:00 a.m. / 8:00 p.m.
Wednesday: 7:00 a.m. / 8:00 p.m.
Thursday: 7:00 a.m. / 8:00 p.m.
Friday: 7:00 a.m. / 8:00 p.m.
Saturday: 7:00 a.m. / 8:00 p.m.
Sunday: 7:00 a.m. / 8:00 p.m.
More on Medicare Advantage
-

2027 Medicare Advantage Changes: What Floridians Need to Know
By Steve Turner
• 2026-10-13
Medicare Advantage vs. Original Medicare explained in plain English. Compare 2027 costs, coverage, doctor choice, and pros and cons to pick the right plan. -

Are Medicare Advantage Plans Going Away? What’s Really Changing in 2027
By Steve Turner
• 2025-10-28
Medicare Advantage isn’t going away, but some plans are. Here’s what’s changing for 2027, how many Florida plans are ending, and what to do if yours won’t renew. -
How To Choose Medicare Supplemental Insurance?
By Steve Turner
• 2026-06-13
How to choose Medicare Supplemental Insurance? Follow our step-by-step guide to compare Medigap benefits, costs, and carriers for your unique needs. -
Major Medical Vs Supplemental Insurance in Florida
By Steve Turner
• 2021-08-18
Understand the key differences between Major Medical and Supplemental Insurance to bridge coverage gaps and save on costs. Tap to Learn Now! -
Does Medigap Cover Long-Term Care? 2027 Guide
By Steve Turner
• 2026-05-24
No, Medigap doesn’t pay for long-term custodial care. See what Medicare Supplement plans do cover in 2027 and which options actually pay for care. -
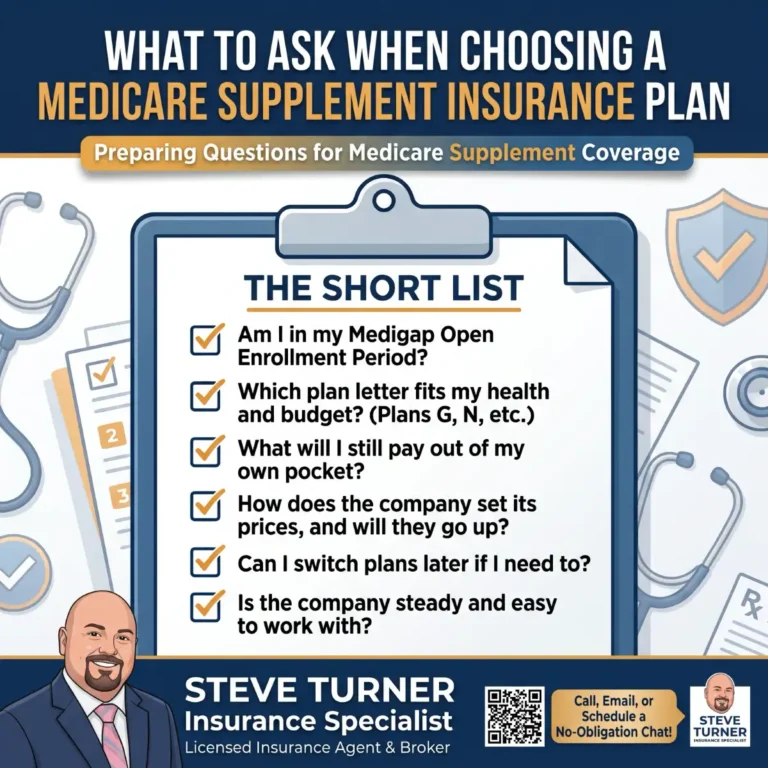
Questions to Ask When Choosing a Medicare Supplement Plan
By Steve Turner
• 2026-10-08
18 questions to ask before buying Medigap: open enrollment, plan letters, costs, and rate hikes. Free checklist from a licensed Tampa, FL Medicare broker.
Medicare plan availability differs by state and county. Steve Turner is licensed in AL, CO, FL, GA, NC, SC, TN, and TX.
Steve Turner is a licensed insurance agent and is not connected with or endorsed by the United States Government or the Federal Medicare Program. The Medicare Annual Enrollment Period is October 15 to December 7.
MEDICARE DISCLAIMER
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
Steve Turner
Steve Turner, CLU®, REBC® is licensed in AL, CO, FL, GA, NC, SC, TN, and TX · NPN 18030539 · Florida License W333468
Steve Turner is a licensed agent and broker and a long-standing member of the National Association of Benefits and Insurance Professionals NABIP®. Steve holds the Registered Employee Benefits Consultant® (REBC®) designation. Steve also holds the “Chartered Life Underwriter” designation (CLU®), a professional credential for individuals specializing in life insurance and estate planning, conferred by the American College of Financial Services. Since 2016 (over 10 years), Steve has helped individuals, families, Medicare beneficiaries, and small businesses find the right coverage to meet their needs. Steve has earned 180+ Google reviews from happy clients.
Steve Turner is a licensed agent appointed by Florida Blue in Florida.