
Why Did My Prescription Drugs Insurance Stop Covering My Medication?

Why Did My Prescription Drugs Insurance Stop Covering My Medication? Customer Confused About Sudden Coverage Denial
I still remember the day it happened. I walked up to the pharmacy counter to pick up a medicine I had taken for years. The pharmacist looked at her screen, frowned, and said, “Your insurance isn’t covering this anymore.” The price she quoted made my stomach drop.
If you are reading this, you may be standing in that same spot. You might be confused, upset, or even scared. I get it. I was all three.
Here is the good news I wish someone had told me that day: in most cases, you can fix this. Insurance plans drop coverage for a handful of common reasons. Once you know which reason applies to you, you can take clear steps to get your medicine covered again or find a cheaper way to buy it.
In this guide, I will walk you through:
- The most common reasons prescription drug insurance stops covering a medication
- What to do right away, while you are still at the pharmacy
- How to ask your plan for an exception or file an appeal
- What people on Medicare need to know, especially during open enrollment
- Ways to save money if your coverage is truly gone
- Answers to the questions I get asked most
I will keep things simple. No confusing insurance talk unless I explain it first. Let’s get started.
9 Common Reasons Your Insurance Stopped Covering Your Medication
Every drug plan has a list of the medicines it pays for. This list is called a formulary (say it like “FOR-myoo-lair-ee”). Most coverage problems come back to this list in some way. Here are the reasons I see most often.
1. Your drug was taken off the formulary
Plans change their drug lists, often at the start of a new year. A plan might drop a drug because it got a better deal on a similar one. If your medicine is no longer on the list, the plan will not pay for it unless you ask for an exception.
2. Your drug moved to a higher “tier”
Most formularies sort drugs into levels called tiers. Lower tiers cost less. Higher tiers cost more. Sometimes a plan still covers your drug but moves it up a tier. It may feel like coverage stopped, but really your share of the cost just went up.
3. Your plan now wants “prior authorization”
Prior authorization means your doctor must get the plan’s okay before the plan will pay. If your plan added this rule, the pharmacy will show the drug as “not covered” until your doctor sends in the paperwork.
4. Your plan added “step therapy”
Step therapy means the plan wants you to try a cheaper drug first. If the cheaper one doesn’t work for you, the plan will pay for the more expensive one. This is sometimes called “fail first.”
5. You hit a “quantity limit”
Some plans only pay for a certain amount of a drug each month. If your doctor raised your dose, or you tried to refill too early, the plan may say no.
6. A generic version came out
When a cheaper generic version of a brand-name drug comes out, many plans stop covering the brand. They will cover the generic instead. The generic has the same active ingredient, so for most people it works the same way.
7. Your insurance plan changed
Maybe you switched jobs, your employer picked a new plan, or you changed plans during open enrollment. A new plan means a new formulary. A drug that was covered before may not be on the new list.
8. Your coverage ended or lapsed
Sometimes the problem is not the drug at all. A missed premium payment, a job loss, or aging off a parent’s plan at 26 can end your coverage. Without active coverage, nothing gets paid.
9. A simple mistake happened
This one surprised me. Errors happen more than you would think. The pharmacy might have the wrong insurance card on file. The doctor’s office might have sent the wrong drug code or dose. Always ask the pharmacist to double-check before you panic.
What I Do First, Right at the Pharmacy Counter
When I hear “not covered,” I try not to walk away empty-handed or confused. Here is my quick checklist:
- Ask for the exact reason. The pharmacist can usually see the insurance company’s rejection message. Ask, “What does the rejection say?” It might say “not on formulary,” “prior authorization required,” or “refill too soon.”
- Make sure they have the right insurance info. Hand over your newest card. Ask them to run it again.
- Ask if there is a covered drug that works the same way. Pharmacists know a lot. They can often name a similar medicine your plan does cover.
- Ask about the cash price and the generic price. Sometimes the generic or cash price is lower than you would expect.
- Ask for a short emergency or transition supply. If you cannot go without your medicine, ask if they can give you a few days’ worth while you sort things out. Many plans allow a one-time “transition fill” when your coverage changes.
- Write it all down. Note the date, the drug name, the rejection reason, and the pharmacist’s name. You will need this later.
My tip: Never just stop taking a medicine because of a coverage problem. Some drugs are risky to stop suddenly. Call your doctor first.
How I Get My Medication Covered Again
Once I know the reason, I can pick the right fix. Here are the main tools you have.
Step 1: Call your insurance plan
The phone number is on the back of your insurance card. When I call, I ask:
- Why is my drug not covered anymore?
- Is there a drug on the formulary that you would cover instead?
- What do I need to do to get an exception?
- How long will a decision take?
I also ask for a copy of the current formulary. Most plans post it on their website, too.
Step 2: Talk to your doctor
Your doctor is your best helper here. Doctors and their staff deal with insurance problems every day. I tell my doctor’s office:
- The name of the drug and the rejection reason
- What the insurance plan told me on the phone
- Whether I have already tried other drugs and how they worked
Your doctor may switch you to a covered drug. Or, if your current drug is the right one for you, your doctor can help you fight for it.
Step 3: Request prior authorization (if needed)
If the plan wants prior authorization, your doctor fills out a form explaining why you need the drug. Many plans decide within a few days. If your health is at risk, your doctor can ask for a faster, or “expedited,” review.
Step 4: Ask for a formulary exception
A formulary exception asks the plan to cover a drug that is not on its list, or to lower its tier. To win, your doctor usually needs to show one of these:
- The covered drugs did not work for you.
- The covered drugs caused bad side effects.
- The covered drugs would be unsafe for you because of another health problem or medicine.
The stronger the doctor’s letter, the better your chances. Ask your doctor to include dates, past drugs you tried, and what happened.
Step 5: Appeal if they say no
A “no” is not the end. You have the right to appeal. Here is how the process usually goes:
- Internal appeal. You ask the insurance company to look at its decision again. Read your denial letter closely. It will tell you how to appeal and the deadline.
- External review. If the plan still says no, you can often ask an independent reviewer outside the company to decide. For many plans, the insurer must follow that decision.
My advice for appeals:
- Act fast. Deadlines matter. Some are as short as 60 days.
- Keep copies of every letter, form, and note.
- Get your doctor’s support in writing.
- Stay polite but firm. Ask for names and reference numbers on every call.
Many people never appeal because they think it won’t work. But appeals do succeed, especially when a doctor explains why you need that exact drug.
If You Have Medicare: What I Want You to Know Right Now
If you get your drug coverage through Medicare Part D or a Medicare Advantage plan, timing is everything. And right now, in October 2026, timing matters.
Read your Annual Notice of Change
Every fall, your plan mails you a letter called the Annual Notice of Change, or ANOC. It lists what will be different next year, including drugs that are being dropped or moved to a new tier. I read mine with a highlighter and look for every drug I take.
Open enrollment is almost here.
Medicare’s open enrollment runs from October 15 to December 7 each year. During this time, you can switch to a different plan that covers your medicines for 2027. If your current plan is dropping one of your drugs, this is your chance to move.
Here is how I check:
- Go to Medicare.gov and use the Plan Finder tool.
- Type in every drug you take, with the right dose.
- Pick the pharmacy you like to use.
- Compare total yearly costs, not just the monthly premium.
The 2027 cost numbers
For 2027, the most anyone with Part D will pay out of pocket for covered drugs is $2,400 for the year, up from $2,100 in 2026. The highest deductible a plan can charge is $700, up from $615. Once you reach the $2,400 cap, you pay $0 for covered drugs for the rest of the year.
That cap only counts drugs your plan covers. This is one more reason to make sure your drugs are on your plan’s list.
Medicare helps with transitions
If you are new to a plan, or your plan changed its list, Medicare plans usually must give you a temporary supply of a drug you were already taking. This gives you and your doctor time to switch drugs or ask for an exception.
Other Medicare help
- Extra Help: A federal program that lowers drug costs for people with limited income. You can apply through Social Security.
- Medicare Prescription Payment Plan: Lets you spread your drug costs into monthly payments instead of paying a lot at once.
- SHIP counselors: Every state has free, unbiased Medicare counselors. They can help you compare plans and appeal denials.
7 Ways I Save Money If My Coverage Is Really Gone
Sometimes, even after all the calls and forms, the answer is still no. When that happens, I don’t give up. I look for other ways to pay less. Here are the ones that have helped people I know and me.
- Switch to a generic. Ask your doctor if a generic version exists. Generics often cost a small fraction of the brand price.
- Try a different drug in the same family. Many health problems can be treated with several different drugs. One of them may be covered or cheaper.
- Use a discount card or app. Free discount programs and apps can lower the cash price at many pharmacies. Compare prices before you buy.
- Check the drug maker’s website. Many drug companies offer copay cards or patient assistance programs. Some give the drug free to people who qualify by income. (Note: copay cards usually can’t be used with Medicare.)
- Shop around. Drug prices can vary widely from one pharmacy to the next, even on the same street. Big-box stores, grocery store pharmacies, and mail-order pharmacies are worth a look.
- Ask for a 90-day supply. Buying three months at once often costs less than three separate one-month fills.
- Look into nonprofit help. Some charities help pay for drugs for certain health conditions. Your doctor’s office or a hospital social worker may know of one.
My tip: Ask your doctor for free samples while you work things out. It doesn’t always work, but it never hurts to ask.
Frequently Asked Questions
Can my insurance stop covering my medication in the middle of the year?
Yes, it can happen. But plans usually have to warn you first. Most big changes happen at the start of a new plan year. If your plan makes a change mid-year, it often lets you keep getting the drug for a while or gives you notice so you can switch.
How do I find out if my drug is covered?
Look up your plan’s formulary. You can find it on your insurance company’s website or by calling the number on your card. You can also ask your pharmacist to check.
What is the difference between a denial and a rejection?
A rejection usually happens at the pharmacy when your claim does not go through. A denial is a formal “no” from your plan after you or your doctor asks for coverage. You can appeal a denial. For a rejection, the first step is usually asking for an exception or prior authorization.
How long does an appeal take?
It depends on your plan and your state. Standard drug appeals often take a few days to a few weeks. If waiting could seriously hurt your health, ask for an expedited review. These are often decided within about 72 hours, and sometimes faster.
Will my doctor charge me to help with prior authorization?
Most doctors do not charge for this. It is a normal part of their work. Still, it’s fair to ask the office if you are worried.
Is a generic drug really as good as the brand?
For most people, yes. In the United States, the FDA requires generics to have the same active ingredient, strength, and way of working as the brand. Some people notice small differences because of the inactive ingredients. If you do, tell your doctor.
What if I can’t afford my medicine?
Talk to your doctor right away. Do not just stop taking it. Your doctor may know of cheaper drugs, samples, or assistance programs. Community health centers can also help people with low incomes.
Can I switch plans to get my drug covered?
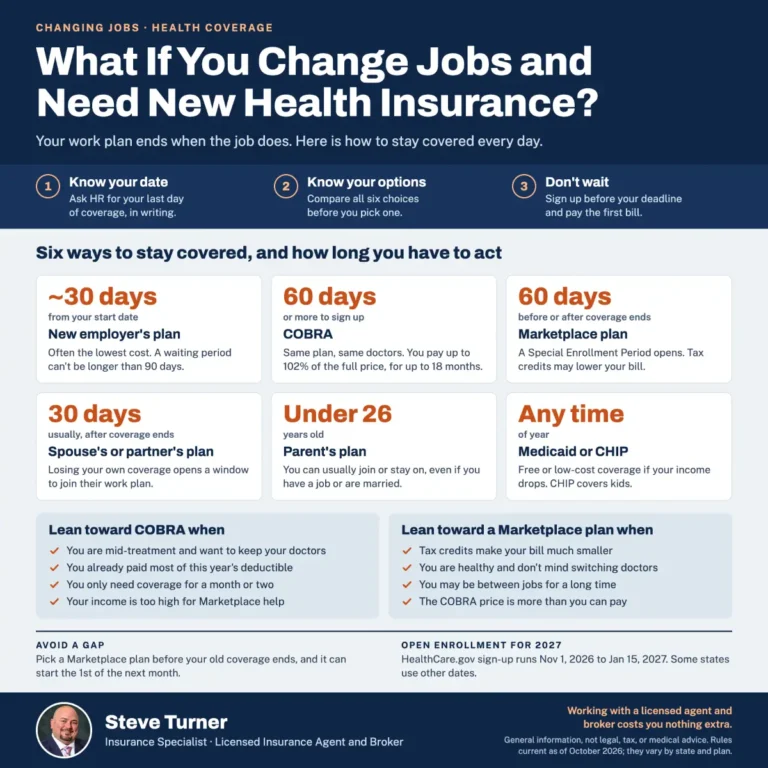
Often, yes, but only at certain times. Medicare has open enrollment each fall. Job-based plans usually have their own enrollment period. Marketplace plans under the Affordable Care Act also have open enrollment. A big life event, like moving or losing other coverage, may let you switch at other times.
My Final Thoughts: You Have More Power Than You Think
That day at the pharmacy, I felt stuck. I thought the insurance company had the final word. It didn’t. I called my plan, talked to my doctor, and asked for an exception. It took about a week, but my medicine was covered again.
Not every story ends that way. But in my experience, most coverage problems have a fix. Sometimes it’s paperwork. Sometimes it’s a new drug that works just as well. Sometimes it’s a better plan or a discount program.
Here is a quick recap of what I want you to remember:
- Find out the exact reason your drug is not covered.
- Never stop a medicine on your own. Call your doctor first.
- Ask your doctor for help with prior authorization or an exception.
- Appeal if your plan says no. Keep notes and meet every deadline.
- Check your plan every year, especially your Annual Notice of Change if you have Medicare.
- Look for savings like generics, discount cards, and drug maker programs.
One more thing: plan. Each fall, I make a list of every medicine I take. Then I check it against my plan’s drug list for the next year. That simple habit has saved me from more than one surprise at the counter.
You deserve to get the medicine you need. Insurance rules can be confusing, but you don’t have to figure them out alone. Lean on your pharmacist, your doctor, and free counselors. Ask questions. Keep pushing politely. More often than not, you’ll find a way through.
This article is for general information only. It is not medical, legal, or insurance advice. Always talk to your doctor before changing or stopping any medication, and check your own plan’s rules for exact details.
Why choose Steve Turner Insurance Specialist?
Because I’m an “Insurance Specialist.” An “insurance specialist” is a broad term that includes insurance agents and insurance brokers, but the key difference is who the agent represents versus who the broker represents.
An “insurance agent” works directly for an insurance company and sells its specific policies to clients.
An “insurance broker” acts as an independent intermediary, comparing policies from multiple companies to find the best fit for their client’s needs, essentially representing the client rather than the insurance company.
I am both a licensed Insurance Agent and a licensed Insurance Broker.
My number one goal in life is to help people and ensure, without a shadow of a doubt, that you and your family are secure and protected. I will always be by your side, helping you mitigate risk by providing the industry’s best and most affordable insurance solutions.
I will find insurance plans for the entire family to help cover whatever life throws at you. I can help you save on severe medical emergencies, find a health insurance plan with low- or no-cost doctor visits and affordable prescription medications, and protect your family in the event of an unexpected accident or illness.
Best of all, it doesn’t cost you anything extra to use an experienced Insurance Agent and Broker like me to help you find the Insurance Plans that fit your individual, family, or business needs.
The companies that sell the insurance plans “you choose“ pay me – you don’t pay me. Calling any big insurance company directly won’t get you a lower price, as they will forward your call to the next available insurance agent on their list. You won’t have had any opportunity to learn about the insurance agent you’re speaking with in advance, understand their qualifications or experience level, or make an informed choice about who you want to work with.
Tap the Contact Me text or icon and get in touch by phone or email, or schedule a “No Obligation” chat through my calendar. I look forward to speaking with you!
OUR CLIENT REVIEWS


CONTACT STEVE TURNER INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a longstanding member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable Healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7 a.m. to 8 p.m.
Tuesday: 7 a.m. to 8 p.m.
Wednesday: 7 a.m. to 8 p.m.
Thursday: 7 a.m. to 8 p.m.
Friday: 7 a.m. to 8 p.m.
Saturday: 7 a.m. to 8 p.m.
Sunday: 7 a.m. to 8 p.m.
SOCIAL FOLLOW + SHARE
Insurance Agent
MEDICARE STATEMENT
The Medicare Annual Enrollment Period is October 15th to December 7th. Steve Turner is not connected with or endorsed by the United States Government or the Federal Medicare Program. Some plans may not be available in your area, and any information I provide is limited to those offered. Please contact Medicare.gov or 1-800-MEDICARE for information on all your options.
There’s no one-size-fits-all answer. Carefully evaluate your health status, anticipated medical needs, prescription drug usage, budget, preferred doctors and hospitals, and tolerance for network rules. During the Medicare Annual Enrollment Period (October 15th to December 7th), research the specific plans available in your Florida county using the Medicare Plan Finder on Medicare.gov, compare costs and benefits, and consider free, personalized counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program.