
How Do I Pick a Medicare Part D Plan?

How Do I Pick a Medicare Part D Plan? Customer Wants Guidance on Selecting Prescription Drug Coverage
Every fall, my mailbox fills up with Medicare ads. Shiny brochures. Phone calls. TV commercials with smiling people on bikes. And every fall, I ask myself the same question: How do I pick a Medicare Part D plan that actually works for me?
If you feel lost, you are not alone. I felt the same way at first. Dozens of plans, and words like “formulary” and “coinsurance” that sound like a foreign language.
The good news is that picking a Part D plan isn’t as hard as it looks. Once I learned what to look for, I could compare plans in about an hour. In this guide, I will walk you through the exact steps I use. I will keep it simple, and I’ll cover the 2027 numbers you need to know.
Let’s get started.
What Is Medicare Part D?
Medicare Part D helps pay for prescription drugs. These are the pills, shots, and inhalers your doctor prescribes that you pick up at a pharmacy.
Original Medicare (Part A and Part B) does not cover most drugs you take at home. That is why Part D exists. Private insurance companies sell Part D plans, and Medicare sets the rules they must follow.
There are two main ways to get Part D coverage:
- A stand-alone Part D plan. You buy this on its own and use it with Original Medicare. Many people also add a Medigap (Medicare Supplement) plan.
- A Medicare Advantage plan with drug coverage. These plans are called MA-PD plans. They bundle your hospital, doctor, and drug coverage into one plan.
In this article, I focus mostly on stand-alone Part D plans. But almost every tip I share also works when you compare the drug coverage inside a Medicare Advantage plan.
When Can I Pick or Change My Part D Plan?
Timing matters a lot. You cannot just switch plans any day you want. Here are the main times you can sign up or make a change:
- Initial Enrollment Period: This is your first chance. It lasts seven months. It starts three months before the month you turn 65 and ends three months after.
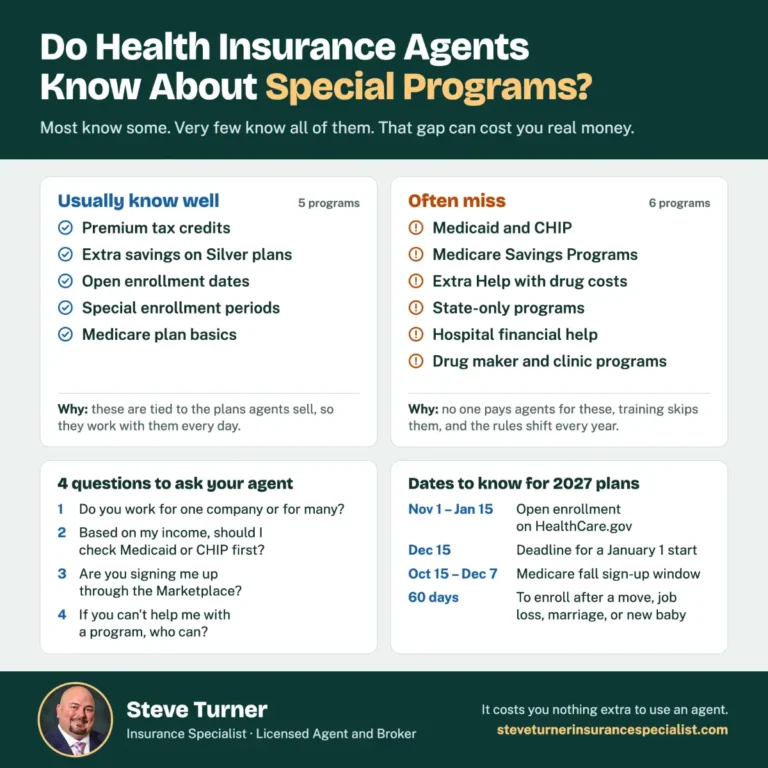
- Medicare Open Enrollment: This runs every year from October 15 to December 7. For 2027 plans, that means October 15 to December 7, 2026—any change you make starts on January 1, 2027.
- Medicare Advantage Open Enrollment: From January 1 to March 31, people already in a Medicare Advantage plan can switch to another Advantage plan, go back to Original Medicare, and pick up a Part D plan.
- Special Enrollment Periods: Some life events let you change plans outside the normal dates. Examples include moving to a new area, losing other drug coverage, or moving into a nursing home.
My tip: Put October 15 on your calendar right now. That is the day the new plans show up, and you can start comparing. Don’t wait until December 6. When I rush, I make mistakes.
What Are the Big Part D Numbers for 2027?
Before I compare plans, I like to know the rules that apply to every plan. Medicare sets these each year. Here are the key numbers for 2027:
- Out-of-pocket cap: $2,400. This is the most you will pay for covered drugs in one year. It went up from $2,100 in 2026. Once you hit $2,400, you pay $0 for covered drugs for the rest of the year.
- Highest deductible allowed: $700. This is up from $615 in 2026. A plan can charge less than $700, or no deductible at all, but it cannot charge more.
- Insulin cost cap: $35 a month. Covered insulin costs no more than $35 for a one-month supply, and you don’t have to meet your deductible first.
- Lower prices on some popular drugs. Starting in 2027, Medicare’s negotiated prices will apply to 15 more drugs, including the diabetes drug Ozempic.
One more thing changed. A federal program that helped keep stand-alone Part D premiums down ended after 2026. That means some plans may charge more per month in 2027. This is a big reason I check my plan every single year, even if I liked it last year.
Step-by-Step: How I Pick My Medicare Part D Plan
Here is the simple process I follow. I do these steps in order, and I take notes as I go.
Step 1: Make a List of Every Drug I Take
This is the most important step. A plan is only good if it covers your drugs.
I grab every pill bottle in my house and write down:
- The exact name of each drug (brand or generic)
- The strength (for example, 10 mg or 20 mg)
- How often I take it (once a day, twice a day, and so on)
- How many I get each month
I don’t forget creams, inhalers, eye drops, or shots. I also ask my doctor if any new drugs might be coming soon. If I know I might start a new medicine next year, I add it to my list.
Pro tip: Your pharmacy can print a list of all your current prescriptions. Just ask at the counter. It saves a lot of time.
Step 2: Write Down the Pharmacies I Like to Use
Next, think about where you fill your prescriptions. Do I like the drugstore down the street? A grocery store pharmacy? Mail order?
This matters because each plan has a pharmacy network. Some pharmacies are “preferred,” which means you pay less there. Others are “standard,” which means you pay more. And some are out of network, which can cost you a lot.
I usually pick one or two pharmacies I’m willing to use and enter them when I compare plans.
Step 3: Use the Medicare Plan Finder
This is the best free tool. The Medicare Plan Finder lives on Medicare.gov. Here is how I use it:
- Go to Medicare.gov and click “Find health & drug plans.”
- Enter my ZIP code. Plans are different in every area.
- Pick “Drug plan (Part D)” if I want a stand-alone plan.
- Type in each drug from my list, with the right strength and amount.
- Add my favorite pharmacies.
- Sort the plans by “Lowest drug + premium cost.”
That last step is the magic part. The tool adds up the monthly premium plus what I’d pay for my drugs all year. That gives me the true cost of each plan.
If I’m not comfortable on a computer, I can call 1-800-MEDICARE (1-800-633-4227). A real person will help me compare plans over the phone.
Step 4: Look at the Total Yearly Cost, Not Just the Premium
This is where many people slip up. I used to think the plan with the cheapest monthly premium was the best deal. It is not always true.
Here is a simple example:
- Plan A costs $0 a month, but my drugs cost $1,800 a year on this plan. Total: $1,800.
- Plan B costs $40 a month ($480 a year), but my drugs only cost $600 a year. Total: $1,080.
Plan B looks more expensive at first. But it saves me $720 over the year!
That is why I always look at the total yearly cost. It includes:
- Monthly premiums × 12
- The deductible
- Copays and coinsurance for my drugs
Step 5: Check the Formulary (the Drug List)
Every plan has a formulary. That’s just a fancy word for the list of drugs the plan covers.
When I check the formulary, I look for three things:
- Is my drug on the list? If not, I may have to pay full price.
- What tier is it on? Most plans sort drugs into tiers, like shelves in a store. Lower tiers cost less. Higher tiers cost more.
- Are there any rules? Some drugs come with extra steps before the plan will pay.
Here is a simple look at common drug tiers:
- Tier 1: Preferred generic drugs. Lowest cost.
- Tier 2: Generic drugs. Low cost.
- Tier 3: Preferred brand-name drugs. Medium cost.
- Tier 4: Non-preferred drugs. Higher cost.
- Tier 5: Specialty drugs. Highest cost.
Every plan sets up its tiers a little differently. The same drug can be Tier 2 on one plan and Tier 4 on another. That is why I compare.
Step 6: Watch Out for Drug Rules
Some plans put rules on certain drugs. These rules can slow you down or cost you money. The three big ones are:
- Prior authorization: My doctor has to get the plan’s OK before the plan will pay.
- Step therapy: I have to try a cheaper drug first. If it doesn’t work, then the plan will cover the drug my doctor wanted.
- Quantity limits: The plan only covers a certain amount of the drug each month.
These rules are not always bad. But if I take a drug with a lot of rules, I look for a plan that has fewer of them. The Medicare Plan Finder shows these rules with little letters or icons next to each drug.
Step 7: Check the Plan’s Star Rating
Medicare rates plans from 1 to 5 stars. More stars mean the plan did a better job with things like customer service, drug safety, and how easy it is to get help.
I like plans with 4 stars or more. A high star rating doesn’t guarantee a perfect plan, but it is a good sign.
Here’s a fun fact: if there is a 5-star plan in your area, you can switch into it once a year, almost any time. You don’t have to wait for Open Enrollment.
Step 8: Read My Annual Notice of Change (If I Already Have a Plan)
If I already have a Part D plan, my plan mails me a letter each fall called the Annual Notice of Change, or ANOC. It usually arrives by the end of September.
This letter tells me what’s changing next year. I look for:
- A higher premium
- A new deductible
- My drugs moving to a higher tier
- My drugs being dropped from the formulary
- My pharmacy leaving the network
I never toss this letter in the trash. Plans change every year. A plan that was great for me in 2026 could be a bad fit in 2027.
Step 9: Make My Choice and Sign Up
Once I find the right plan, I sign up. I can do it:
- On the Medicare Plan Finder at Medicare.gov
- By calling 1-800-MEDICARE
- By calling the plan directly
- On the plan’s website
When I join a new Part D plan, I am automatically removed from my old one. I don’t have to cancel it myself.
After I enroll, I keep my confirmation number and watch for my new member card in the mail.
Quick Checklist: What I Compare Side by Side
When I narrow it down to my top two or three plans, I make a simple chart. Here is what I compare:
- Monthly premium
- Yearly deductible
- Estimated total yearly cost for my drugs
- Are all my drugs covered?
- What tier is each drug on?
- Any prior authorization, step therapy, or quantity limits?
- Is my pharmacy preferred, standard, or out of network?
- Is mail-order available, and does it save money?
- Star rating
- Customer service reviews or experiences from people I trust
This checklist keeps me focused. It stops me from picking a plan just because the ad looked nice.
Common Mistakes I Try to Avoid
I’ve learned a few lessons the hard way. Here are the mistakes I watch out for:
- Choosing a plan just because a friend has it. My friend takes different drugs than I do. Her best plan might be my worst plan.
- Only looking at the premium. As I showed above, the cheapest premium can cost more in the end.
- Not checking every single drug. One missing drug can cost hundreds of dollars a month.
- Ignoring the pharmacy network. If my favorite pharmacy isn’t preferred, my costs can jump.
- Staying in the same plan out of habit. Plans change every year. I check every year.
- Waiting until the last minute. Rushing leads to mistakes, and help lines get very busy in early December.
- Skipping Part D because I don’t take drugs right now. This one can cost me for life. I explain why below.
Questions People Often Ask About Picking a Part D Plan
Q: Do I need Part D if I don’t take any prescriptions right now?
A: In most cases, yes. If you don’t sign up for Part D (or have other good drug coverage) when you first can, you may have to pay a late enrollment penalty. The penalty is added to your monthly premium for as long as you have Part D. It grows by 1% of the national base premium for every month you went without coverage.
When I first joined Medicare, I didn’t take many drugs either. So I picked a low-cost plan just to be safe. That way, I avoided the penalty and had coverage if I got sick.
Q: What if I have drug coverage from my job or union?
A: Ask your employer or union if your coverage is “creditable.” That means it is at least as good as standard Medicare drug coverage. If it is, you can usually keep it and skip Part D without a penalty. Your plan should send you a notice each year telling you if it’s creditable. Save that notice!
Q: What is the $2,400 cap, and how does it help me?
A: In 2027, the most you will pay out of pocket for covered Part D drugs is $2,400 for the whole year. After you reach that amount, you pay $0 for covered drugs until the year ends. This is a big help for people who take expensive drugs. Keep in mind, your monthly premiums don’t count toward this cap.
Q: Can I spread out my drug costs over the year?
A: Yes. The Medicare Prescription Payment Plan lets you pay your drug costs in monthly bills instead of all at once at the pharmacy. It doesn’t lower your total cost, but it can make big bills easier to handle. This can really help if you hit high costs early in the year, like in January. You can ask your plan to enroll you.
Q: What if I can’t afford my drugs?
A: Check if you qualify for Extra Help. This Medicare program helps people with limited income and savings pay for Part D. If you qualify, you can pay a $0 premium and $0 deductible on many plans, plus low copays for your drugs. You can apply through Social Security at SSA.gov or by calling 1-800-772-1213.
Many states also have their own programs that help with drug costs. Your local State Health Insurance Assistance Program (SHIP) can tell you what’s available.
Q: What if my drug isn’t on any plan’s list?
A: You and your doctor can ask your plan for an exception. This means asking the plan to cover a drug that isn’t on its list, or to lower the tier. Your doctor will need to explain why you need that drug. If the plan says no, you have the right to appeal.
Q: Is a Medicare Advantage plan with drug coverage better than a stand-alone Part D plan?
A: It depends on you. Medicare Advantage plans often have low premiums and bundle everything together. But they usually require you to use in-network doctors and hospitals. A stand-alone Part D plan works with Original Medicare, which lets you see any doctor who takes Medicare. I think about which doctors I want to keep and how much I travel before I decide.
Q: Can I get free help picking a plan?
A: Yes! Here are some free, trusted places I go for help:
- Medicare.gov and the Medicare Plan Finder
- 1-800-MEDICARE (1-800-633-4227), open 24 hours a day, 7 days a week
- Your local SHIP office. These counselors are trained and unbiased. They don’t sell plans. You can find yours at shiphelp.org.
- Your pharmacist. Many pharmacists know which plans work well at their store.
Watch Out for Medicare Scams
This time of year, scammers get busy. I protect myself by remembering these rules:
- Medicare will never call me to sell a plan.
- I never give my Medicare number to someone who calls, texts, or knocks on my door out of the blue.
- I’m careful with ads that promise “free” gifts or cash for switching plans.
- If I’m unsure, I hang up and call 1-800-MEDICARE myself.
My Simple Summary: How to Pick a Medicare Part D Plan
If you remember nothing else, remember these five things:
- Start with your drug list. The right plan covers your drugs at the lowest total cost.
- Use the Medicare Plan Finder. Sort by “lowest drug + premium cost.”
- Check your pharmacy. Preferred pharmacies can save you a lot.
- Review your plan every year. Plans change, and 2027 brings a higher deductible and cap.
- Ask for free help. SHIP counselors and 1-800-MEDICARE are there for you.
Picking a Medicare Part D plan used to stress me out. Now, I treat it like a yearly checkup for my wallet. I grab my drug list, sit down with a cup of coffee, and compare. In about an hour, I know I’ve made a smart choice.
Open Enrollment runs from October 15 to December 7, 2026. Don’t wait. Make your list today, and you’ll be ready to pick the best plan for you in 2027.
Why choose Steve Turner Insurance Specialist?
Because I’m an “Insurance Specialist.” An “insurance specialist” is a broad term that includes insurance agents and insurance brokers, but the key difference is who the agent represents versus who the broker represents.
An “insurance agent” works directly for an insurance company and sells its specific policies to clients.
An “insurance broker” acts as an independent intermediary, comparing policies from multiple companies to find the best fit for their client’s needs, essentially representing the client rather than the insurance company.
I am both a licensed Insurance Agent and a licensed Insurance Broker.
My number one goal in life is to help people and ensure, without a shadow of a doubt, that you and your family are secure and protected. I will always be by your side, helping you mitigate risk by providing the industry’s best and most affordable insurance solutions.
I will find insurance plans for the entire family to help cover whatever life throws at you. I can help you save on severe medical emergencies, find a health insurance plan with low- or no-cost doctor visits and affordable prescription medications, and protect your family in the event of an unexpected accident or illness.
Best of all, it doesn’t cost you anything extra to use an experienced Insurance Agent and Broker like me to help you find the Insurance Plans that fit your individual, family, or business needs.
The companies that sell the insurance plans “you choose“ pay me – you don’t pay me. Calling any big insurance company directly won’t get you a lower price, as they will forward your call to the next available insurance agent on their list. You won’t have had any opportunity to learn about the insurance agent you’re speaking with in advance, understand their qualifications or experience level, or make an informed choice about who you want to work with.
Tap the Contact Me text or icon and get in touch by phone or email, or schedule a “No Obligation” chat through my calendar. I look forward to speaking with you!
OUR CLIENT REVIEWS


CONTACT STEVE TURNER INSURANCE AGENT & BROKER
I’m here to take your calls and emails and answer your questions 7 Days a week from 7:00 a.m. to 8:00 p.m., excluding posted holidays.
Steve Turner is a licensed agent and broker and a longstanding member of the National Association of Benefits and Insurance Professionals®. Steve holds the prestigious Registered Employee Benefits Consultant® designation. NABIP® is the preeminent organization for health insurance and employee benefits professionals and works diligently to ensure all Americans have access to high-quality, affordable Healthcare and related services.
Steve Turner is a licensed agent appointed by Florida Blue.
EMAIL ME: 24×7
OFFICE LOCATION
Website: steveturnerinsurancespecialist.com
Email: [email protected]
Phone and Text: +1-813-388-8373
Business Hours:
Monday: 7 a.m. to 8 p.m.
Tuesday: 7 a.m. to 8 p.m.
Wednesday: 7 a.m. to 8 p.m.
Thursday: 7 a.m. to 8 p.m.
Friday: 7 a.m. to 8 p.m.
Saturday: 7 a.m. to 8 p.m.
Sunday: 7 a.m. to 8 p.m.
SOCIAL FOLLOW + SHARE
Insurance Agent
MEDICARE STATEMENT
The Medicare Annual Enrollment Period is October 15th to December 7th. Steve Turner is not connected with or endorsed by the United States Government or the Federal Medicare Program. Some plans may not be available in your area, and any information I provide is limited to those offered. Please contact Medicare.gov or 1-800-MEDICARE for information on all your options.
There’s no one-size-fits-all answer. Carefully evaluate your health status, anticipated medical needs, prescription drug usage, budget, preferred doctors and hospitals, and tolerance for network rules. During the Medicare Annual Enrollment Period (October 15th to December 7th), research the specific plans available in your Florida county using the Medicare Plan Finder on Medicare.gov, compare costs and benefits, and consider free, personalized counseling from Florida’s SHINE (Serving Health Insurance Needs of Elders) program.